


EN
Sysco (SYY) Could Be 15% Undervalued Following Earnings And CFO Appointment
Sysco’s CFO transition and fresh quarterly results
Sysco (SYY) is in focus after appointing long time finance executive Brandon Sewell as Executive Vice President and Chief Financial Officer, alongside reporting first quarter sales of US$21.74b and net income of US$526m.
Sysco’s latest leadership news comes after a mixed stretch for the stock, with the share price rising 2.15% on the day but down 7.29% over the past week. A 5.20% 1 year total shareholder return and 23.96% 3 year total shareholder return point to steadier long term momentum despite recent pressure.
Scan how Sysco’s CFO change and earnings story compares with other potential opportunities by reviewing a curated group of 19 high quality undiscovered gems in similar fundamental territory.
Sysco just paired a softer recent share price patch with fresh earnings and a CFO promotion rooted in long tenure and internal know how. Is that latest move about business strength, or sentiment catching its breath before the next rerating debate?
Most Popular Narrative: 15% Undervalued
Sysco’s most followed valuation story pins fair value around $90.31 per share, compared with the recent $76.86 close. This puts the CFO change into a pricing backdrop that already assumes meaningful upside is on the table.
Sysco is rolling out more than 30 AI and technology projects across sales, supply chain, merchandising and back office, with about US$100 million of in-year savings built into fiscal 2027 guidance and a targeted US$500 million profit improvement by fiscal 2029 that is aimed at higher operating margins and earnings.
See why 78 investors see Sysco as 15% undervalued.
Result: Fair Value of $90.31 (UNDERVALUED)
Still, the whole Sysco story leans on successful Restaurant Depot integration and the delivery of those AI driven profit goals, and either could disappoint investors.
Find out about the key risks to this Sysco narrative.
Another view on Sysco’s valuation
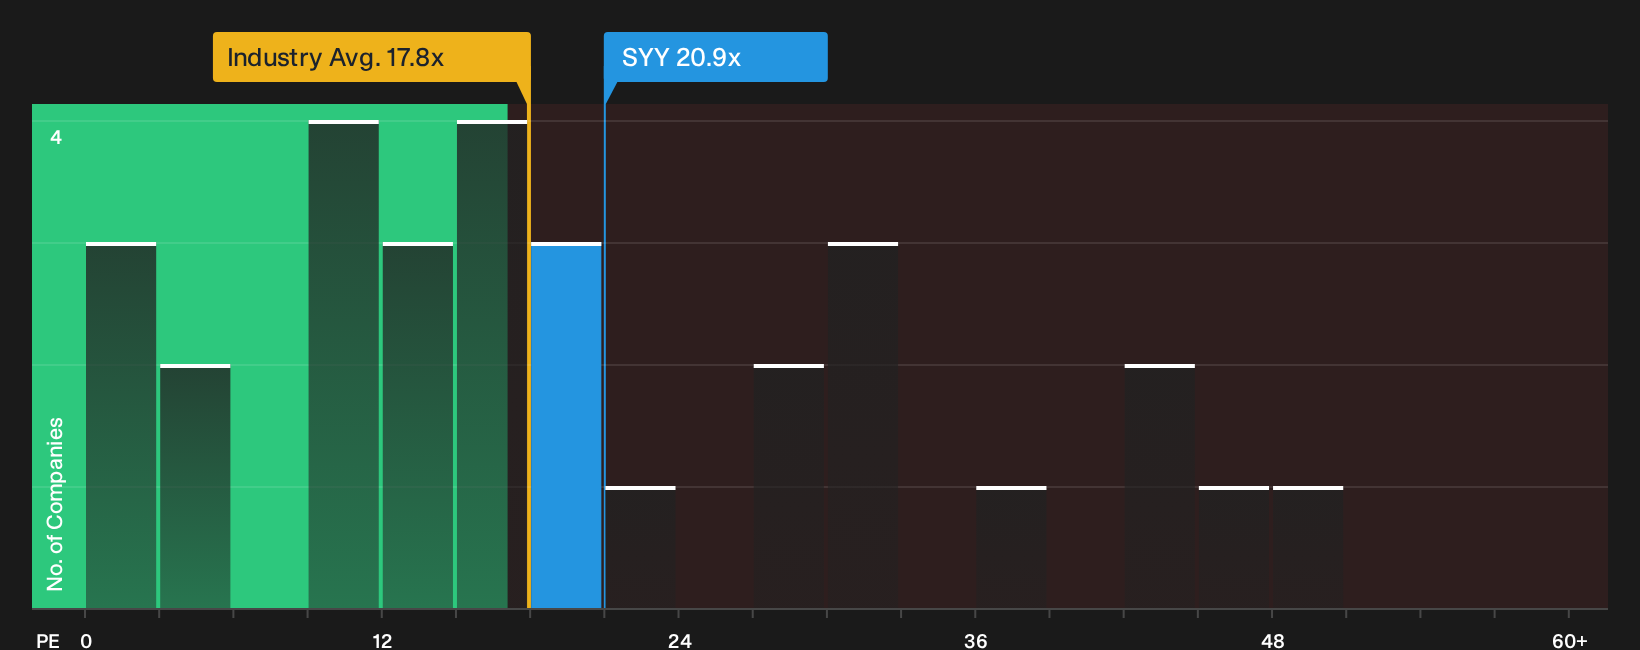
The first story framed Sysco against a $90.31 fair value. A second lens uses its P/E of 20.9x. That is higher than the US Consumer Retailing industry at 17.8x, lower than peers at 37.1x, and still below a 29.9x fair ratio. Is that gap caution or potential?
See what the numbers say about this price in more detail: See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals or early inflection point; either way, Sysco’s set of risks and rewards is clear enough for you to judge for yourself. To weigh that balance directly and decide where you stand, go through the 3 key rewards and 1 important warning sign.
Looking for more Sysco sized investment ideas?
If Sysco has you thinking harder about where to put fresh capital, do not stop here. Cast a wider net now or risk missing tomorrow’s outliers.
- Target resilient compounding by scanning a 31 resilient stocks with low risk scores that may help you focus on businesses with steadier profiles and fewer red flags.
- Zero in on quality at a reasonable price through a 38 high quality undervalued stocks that highlights companies with stronger fundamentals relative to their current tags.
- Hunt for future market favorites by reviewing a 19 high quality undiscovered gems that surfaces under-the-radar stocks before they are widely followed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com