


EN
Is Higher Q3 Sales Altering The Investment Case For PPG Industries Stock (PPG)?
- PPG Industries reported third quarter 2026 results with sales of US$4,353 million, net income of US$451 million, and higher earnings per share from continuing operations compared with the prior year period.
- The nine month figures show sales of US$12,778 million and net income of US$1,270 million, indicating that higher sales have not translated into higher total profits so far this year. This outcome raises questions about cost pressures and product mix.
- We will look at how PPG Industries' investment narrative is influenced by higher third quarter sales alongside steady net income performance.
Scan how PPG Industries compares by size and resilience, and then line it up against our handpicked list of solid balance sheet and fundamentals (25 results) for potential alternatives facing similar earnings pressures.
PPG Industries Investment Narrative Recap
To own PPG Industries, you need to be comfortable with a slow but steady coatings business where pricing, cost control and mix shifts do most of the work. The latest quarter fits that picture. Sales reached US$4,353 million while net income stayed close to last year, so the short term focus stays on execution rather than a sharp reset.
The key near term catalyst is whether management can hold or improve margins while raw material costs and indexed contracts put pressure on pricing. The biggest current risk sits in that same squeeze. If input costs keep moving ahead of contract resets, higher sales may keep translating into fairly flat earnings.
The fresh earnings release for the quarter and nine month period to 30 September 2026 is the clearest reference point for these catalysts. PPG Industries reported year to date sales of US$12,778 million and net income of US$1,270 million, which keeps the story focused on efficiency and mix rather than headline volume alone.
Those figures sit alongside planned cost cuts, plant closures in Europe and capacity additions in aerospace, protective and marine and auto related coatings. Execution on these projects now matters more, because the latest numbers highlight how easily higher revenue can be absorbed by materials, energy and currency headwinds before reaching the bottom line.
Analysts expect PPG Industries to generate about US$18.0b of revenue and US$2.0b of earnings by 2029, which implies forecast revenue growth of roughly 2.6% a year and an earnings increase of about US$0.4b from current earnings of around US$1.6b.
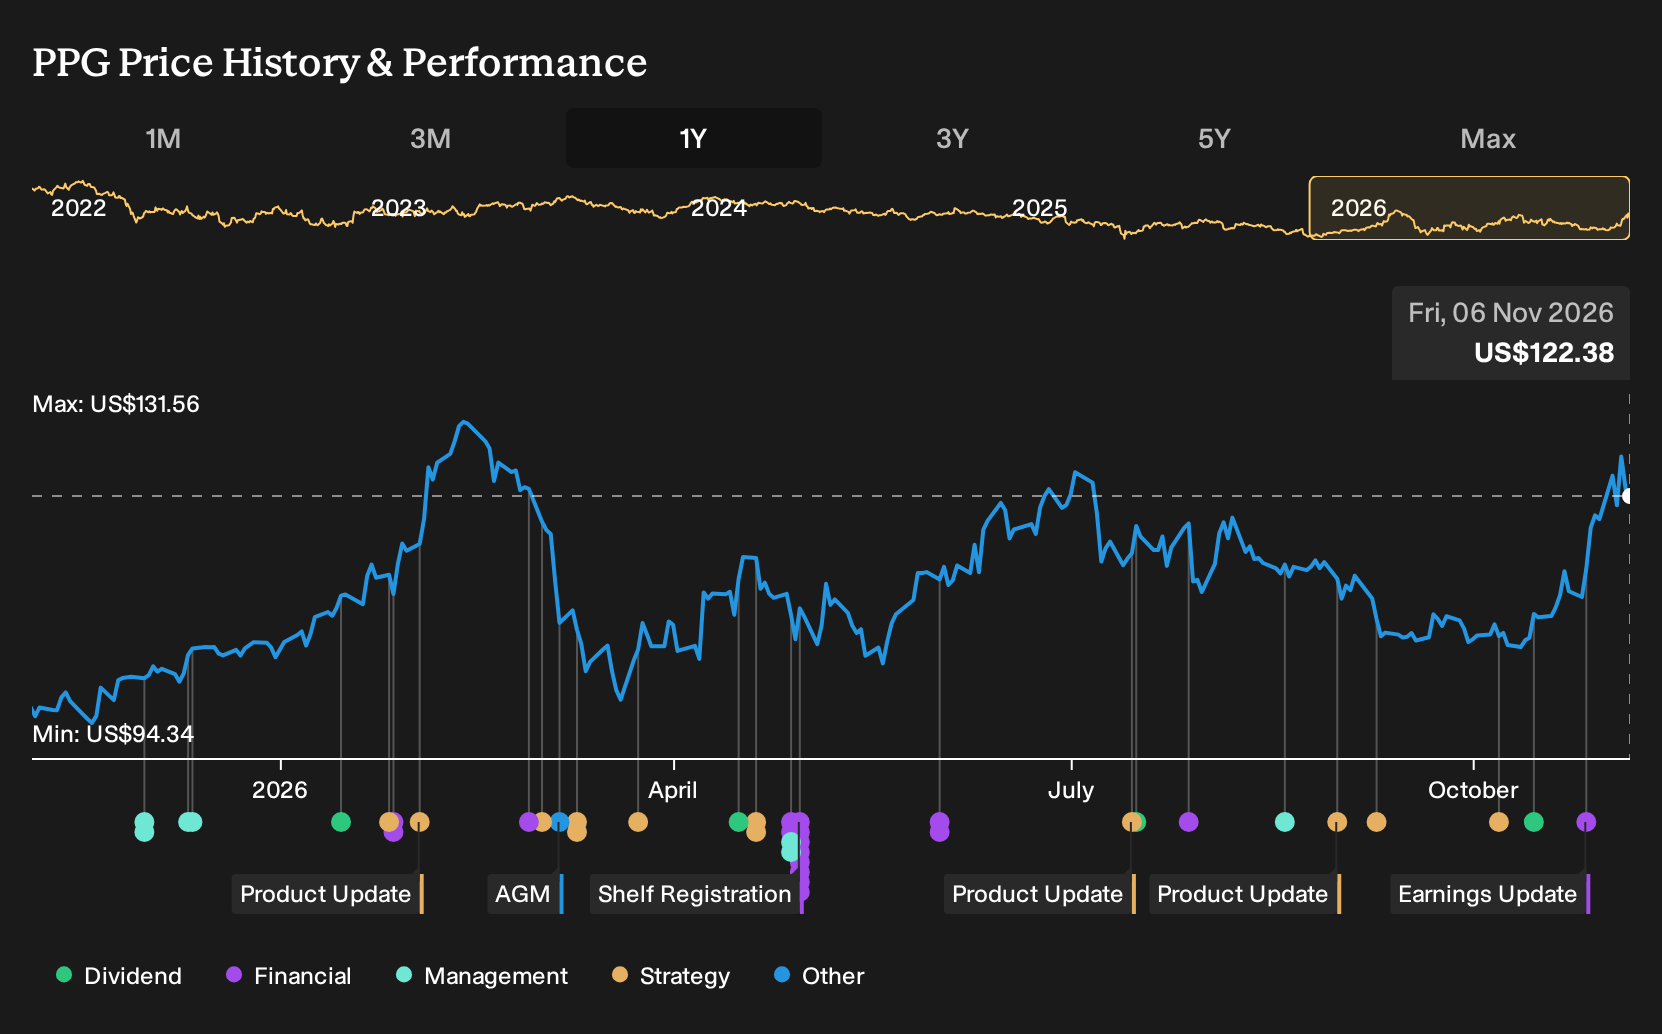
Uncover why PPG Industries' fair value indicates a 6% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Three fair value views from the Simply Wall St Community span roughly US$129 to US$185 per share, so private investors are clearly assigning very different upside and downside to PPG Industries. Those figures were set before the latest earnings release, so you should weigh them against risks around indexed pricing, currency moves and auto production trends.
Explore 2 other PPG Industries fair value estimates, including one that suggests it could be worth just $129.41.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your PPG Industries research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for PPG Industries. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate PPG Industries' overall financial health at a glance.
Looking for more investment ideas beyond PPG Industries?
If PPG Industries has sharpened your view on earnings resilience and balance sheet strength, it can help to compare it with other businesses facing different trade offs on cash flow, debt and dividends.
- For investors who want income to do more of the work, scan high yield opportunities through a curated set of 7 dividend fortresses that pair payout potential with supporting fundamentals.
- If capital protection is your first line of defense, focus on sturdier balance sheets by checking a 31 resilient stocks with low risk scores that filters for companies with more resilient risk profiles.
- When you want to widen the search beyond well known tickers, cast the net over a 19 high quality undiscovered gems that highlights under followed businesses with solid underlying metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com