


EN
What Vale Indonesia Bears Saw Before The Fall
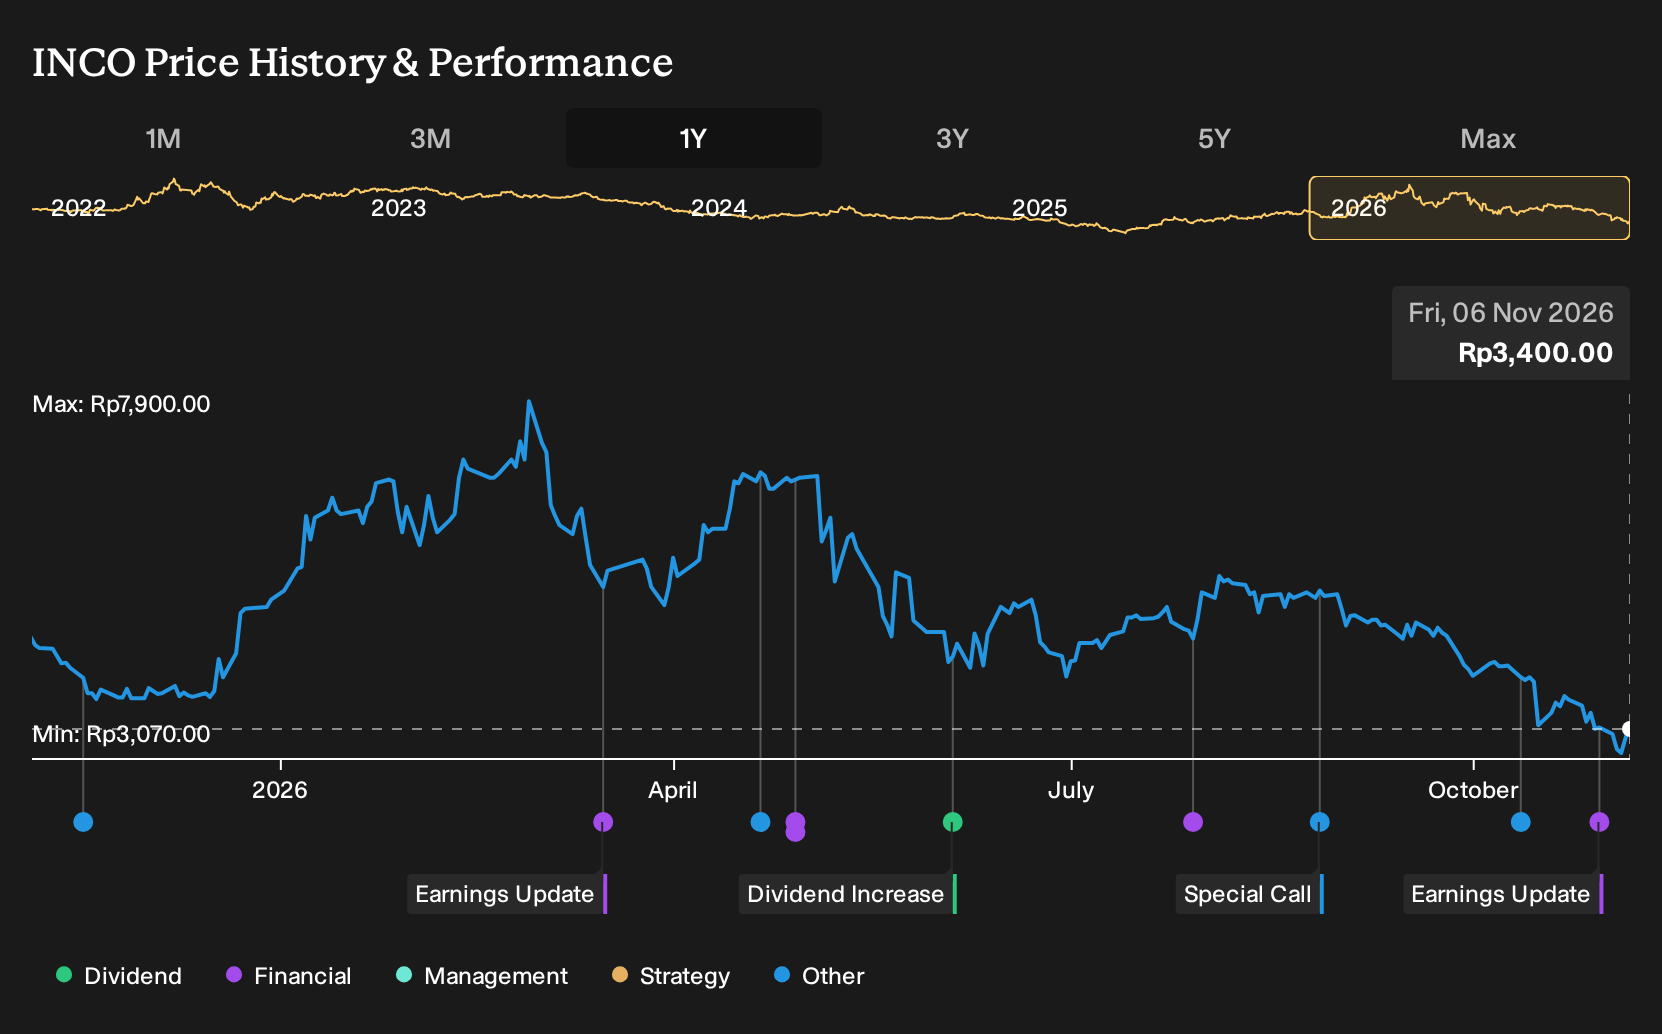
If you had paused on Vale Indonesia in late 2025, watching analysts argue over whether electric vehicle demand or decarbonization rules would matter more, the risk felt mostly theoretical. Holding Vale Indonesia over the past year would have meant a 23.3% loss, including dividends. With that result now on record, which of the published expectations about nickel demand, regulation, or project execution would you want to stress test most carefully at the starting line?
Vale Indonesia has already moved. See which of 225 high quality undervalued stocks still trade below our estimates.
What Investors Were Really Debating On Vale Indonesia
The shares cost IDR4,550 at the start, and anyone looking at Vale Indonesia then had to choose between two very different but plausible stories about where the business could head next.
The bullish narrative pointed to a fair value of IDR5,061, a price implied by expectations that faster Bahodopi and Pomalaa ore volume ramp up could scale revenue and cash generation more quickly than consensus models assumed.
The bearish narrative anchored on a fair value of IDR2,908, based on concerns that Indonesia's push for tighter ownership rules and local content regulation might squeeze margins and restrict Vale Indonesia's future profit pool.
What The Results Changed For Vale Indonesia
The clearest new datapoint for Vale Indonesia was the Q3 2026 report. Total revenue was US$278.65 million in Q3 2025 versus US$353.00 million in Q3 2026, while net income moved from US$27.20 million to US$42.75 million and net margin rose from 9.8% to 12.1%. That combination supported the optimistic case on profitability, although it did not settle longer term demand or regulatory worries.
The useful takeaway is simple. When a thesis hinges on margin resilience and project execution, focus on reported net margin and absolute profit over time, and check whether each new quarter keeps moving those figures toward the original narrative or quietly away from it.
What You Are Paying For In Vale Indonesia Today
Vale Indonesia trades at IDR3,400 today, after the share price declined 23.3% over the past year. The selected Narrative’s Fair Value sits above the current price and rests on the idea that project delivery and cost control matter more than broad nickel demand debates.
On this view, a buyer today is effectively assuming that HPAL projects and new ore operations reach stable, permitted production with cash costs inside management ranges.
"The main requirement is successful execution on the three HPAL joint ventures and associated mines so that Sorowako, Bahodopi, Pomalaa and Sorowako limonite all move from capital-intensive build out into stable, low-cost production with reliable permits and ore quotas."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
Looking Beyond Vale Indonesia
Once you understand Vale Indonesia, it is natural to look sideways. Nickel supports batteries. Another ingredient quietly underpins the food that feeds those drivers.
Crop nutrients have no easy substitute. When supply stumbles or trade routes clog, farmers still need reliable fertilizer.
One smaller miner is trying to produce potash using oil-style horizontal drilling. The method aims for cheaper, modular development with less surface disruption.
Instead of one giant pit, it plans a series of compact stages. Each step is designed to reach production faster and refine the process.
If that approach holds up in the field, the potential impact is straightforward. A different kind of resource project could matter more than its low profile suggests.
That argument has a Narrative and a number behind it. → See the company one Narrative values 45% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com