


EN
Tesla (TSLA) Recasts Its Story Around Robotaxis, But Does The Valuation Fit
Tesla (TSLA) is scrapping Cybertruck production at Gigafactory Texas to free up capacity for the Cybercab robotaxi program. That pivot puts autonomous mobility, AI and software-heavy services firmly in the spotlight.
Recent trading has been choppy for Tesla, with the share price jumping 4.23% in the last session after a 7 day share price return that declined 10.40% and a 30 day move that fell 6.40%, even as news flow has focused on the pivot away from Cybertruck toward Cybercabs, rising Full Self Driving subscriptions and fresh robotaxi launches in Texas.
Over a longer window, momentum has cooled this year, with the year to date share price return down 18.23% and the 1 year total shareholder return down 16.60%. Holders over three years have still seen a 66.89% total shareholder return and a 3.99% total shareholder return over five years, which frames how sharply sentiment has swung around Tesla's transition from hardware heavy pickups to software rich autonomous mobility.
Scan how the Tesla robotaxi pivot compares with other autonomous and AI-focused plays by reviewing the hand picked 40 AI small caps that are already on investors' radar.
Bulls point to Tesla's growing FSD subscriber base and the Cybercab refocus as proof the AI and robotaxi thesis is taking hold. Bears see stretched multiples and political risk. Which story do the current valuation markers support next?
Most Popular Narrative: 40% Undervalued
Tesla’s most followed valuation storyline puts fair value at $600.82 against a last close of $358.22, which is a wide gap that keeps the robotaxi and AI optionality front and center for investors trying to price the Cybercab pivot.
The positive side is that stronger cash generation and improving automotive margins could help support the business while it invests in future technologies. The concern is whether the current business can generate enough sustainable profit to justify the expectations surrounding AI, robotaxis and humanoid robotics.
See why 24 investors see Tesla as 40% undervalued.
Result: Fair Value of $600.82 (UNDERVALUED)
Still, the Tesla narrative could be knocked off course if robotaxi timelines slip or if margins stay thin while the Cybercab build out soaks up capital.
Find out about the key risks to this Tesla narrative.
Another View: Tesla Looks Expensive On Sales
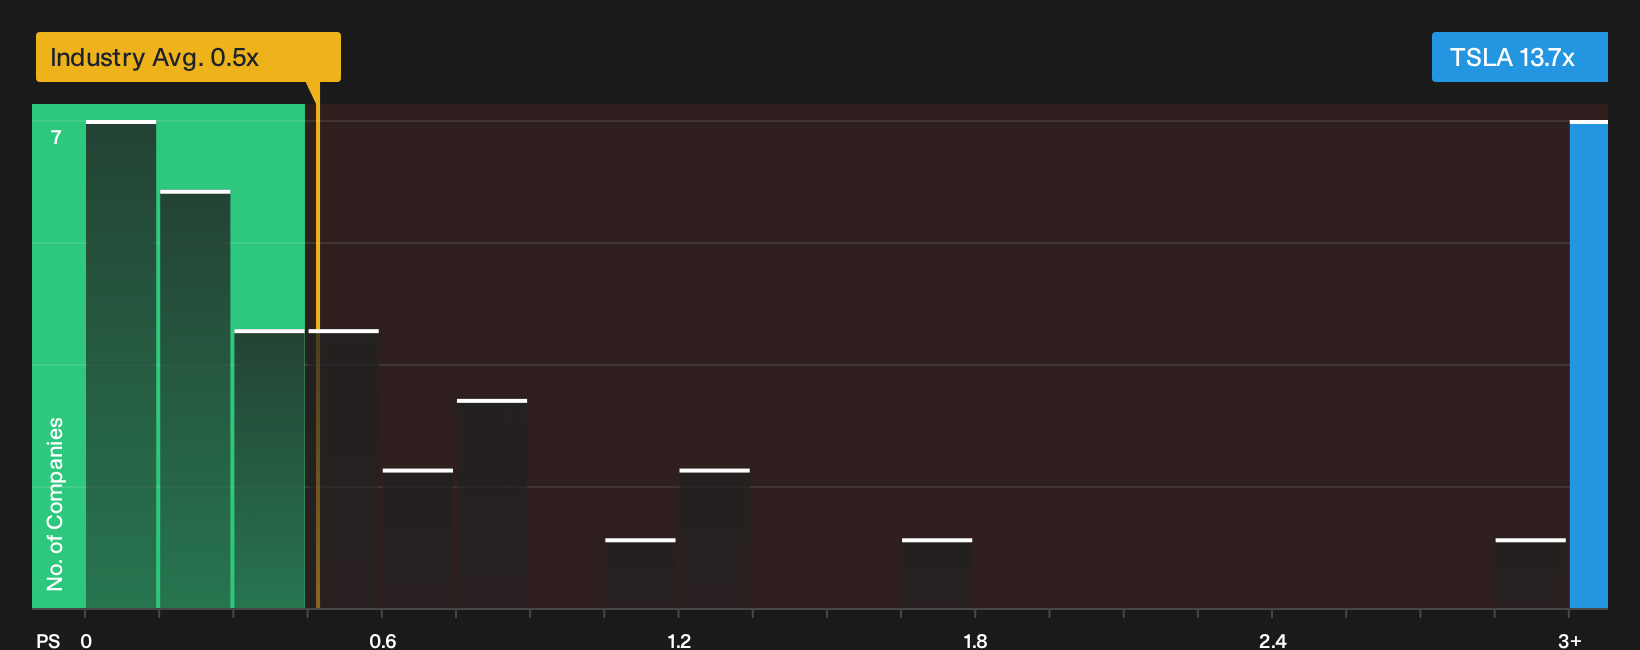
The $600.82 fair value estimate paints Tesla as materially undervalued. A different lens tells a sharper story. On this view, the stock trades on a P/S ratio of 13.7x, while the fair ratio sits at 3.2x and the US Auto industry sits around 0.5x, with peers near 1.1x.
In practical terms, you are paying several times more per dollar of revenue than both the sector and close competitors, and well above where the fair ratio suggests the market could move. That gap can reward investors if Tesla grows into it, or hurt if expectations deflate. Which side of that trade are you really comfortable owning?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Tesla is clearly split, so treat this as your cue to move quickly. Review the data yourself and pressure test both sides of the debate with the 1 key reward and 3 important warning signs.
Looking for more Tesla investment ideas?
If you stop with Tesla, you only see one angle. Broaden your watchlist and pressure test your thesis by comparing it with fresh, data driven opportunities.
- Target potential bargains that pair quality with a discount by scanning the 38 high quality undervalued stocks and seeing which businesses line up with your return goals.
- Strengthen portfolio resilience by focusing on financially sound companies using the list of solid balance sheet and fundamentals (25 results) to filter for robust balance sheets and fundamentals.
- Add sharper growth optionality by reviewing the 19 high quality undiscovered gems that most investors are not watching yet but already screen well on key metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com