


EN
LANXESS (XTRA:LXS) Stock May Trade At A Deep Discount To Sales
LANXESS has seen its share price fall sharply over longer periods, even after some recent short term strength. This puts fresh focus on whether the current valuation can be explained by its sales base. For anyone following the stock, the key issue now is how that market price lines up with the revenue the chemicals group is actually generating.
- Over the past 5 years the share price has declined 75.7%, which puts pressure on the question of how much investors today are really paying for LANXESS' sales.
- The business relies heavily on how efficiently its specialty chemicals portfolio converts sales into cash, so any shift in pricing power, input costs or capacity utilisation can feed directly into what a sales based valuation implies.
- Your read on LANXESS is one view; the desks covering it have another. See what analysts think LANXESS's shares could be worth.
For investors, the debate is whether LANXESS' current share price is properly supported by the level and quality of its sales today.
If you want to test the same “price versus sales” question beyond LANXESS, you can compare it with a wider group using 224 high quality undervalued stocks.
Is LANXESS Still Cheap on Sales?
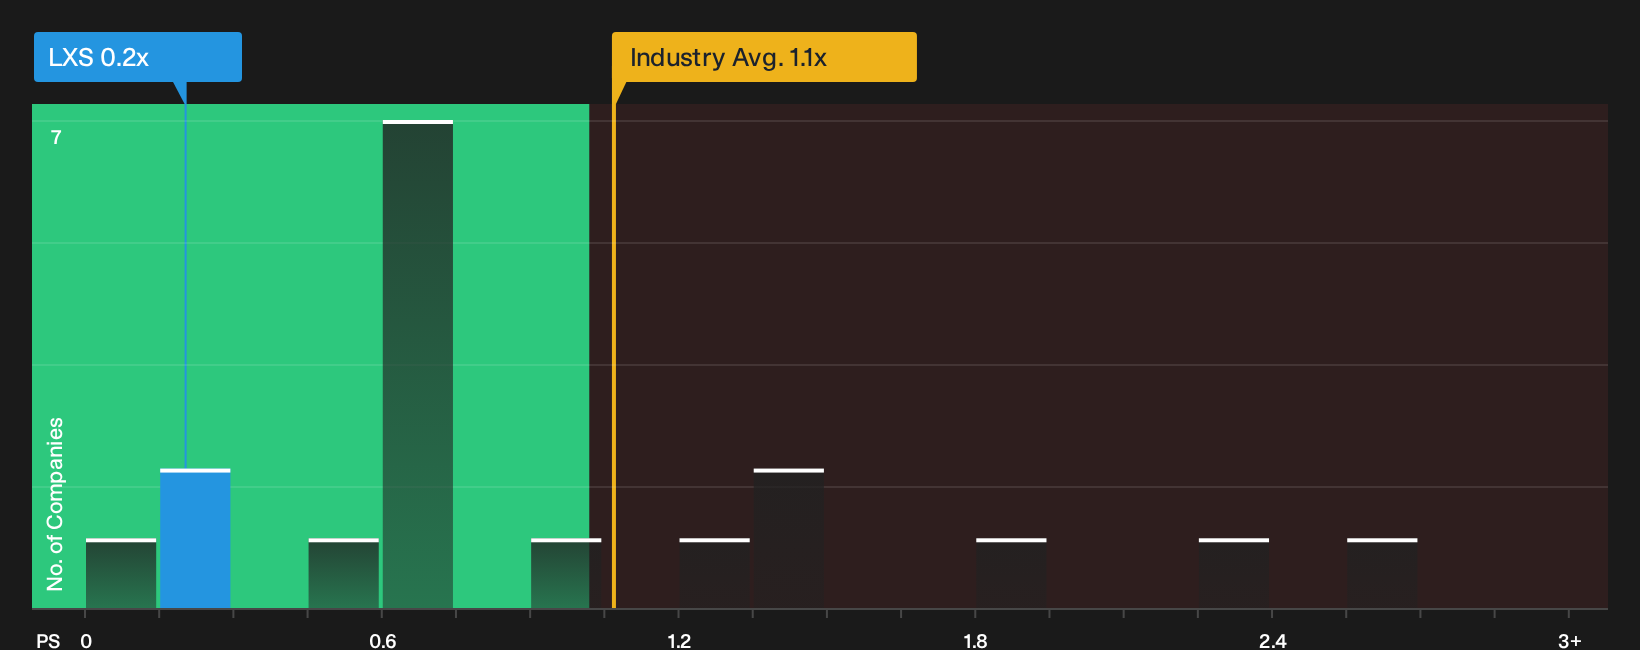
The P/S ratio suits LANXESS because the business is heavily about converting its sales base into value for shareholders. On this metric, the stock trades on a P/S of about 0.2x, which is far below the Chemicals industry average of around 1.2x and also below peers at roughly 1.1x. That is a wide gap between what the market currently pays for each euro of LANXESS revenue and what it pays across the sector.
The tailored fair multiple implied by the valuation work, which folds in LANXESS specific growth profile, margins, size and risk, sits above the current 0.2x level. The present valuation therefore screens as undervalued on a P/S basis, with the share price implying a heavier discount to its sales than that framework would suggest. Readers still need to weigh whether the quality and durability of those revenues justify any portion of that discount, or whether the gap has become too wide. Explore the numbers behind LANXESS's P/S valuation.
The LANXESS Narrative: What Would Justify Today's Price?
Narratives on LANXESS pick up where the valuation question leaves off, spelling out which paths for growth, profitability and earnings would need to unfold for the stock to be worth materially more or less than the current share price on Simply Wall St's Community page. Each narrative ties a specific fair value estimate to a clear storyline about potential catalysts and threats so you can track which version of events is gradually matching reality.
The LANXESS community splits between investors who see restructuring and balance sheet moves as underappreciated, and others who think refinancing and demand risks still weigh too heavily.
Bull case: 14% undervalued
"Execution of the three cost and restructuring waves, targeting a combined €300 million in annual savings through 2028 and including network optimization and around 550 job cuts, is intended to lower the structural cost base and support higher net margins when volumes improve..."
Discover why this Narrative puts LANXESS at 14% undervalued.
Bear case: 19% overvalued
"Although LANXESS has delivered sizeable FORWARD! program savings and announced additional structural measures, the new rounds of job cuts and network optimization scheduled to reach full effect only by the end of 2028 risk coming too late to offset prolonged sub 70% utilization..."
Explore why this Narrative puts LANXESS at 19% overvalued.
LANXESS valuation is only half the story
Price and sales tell you what the market pays for LANXESS today. However, the real curiosity is how professional analysts currently map out its revenue and earnings profile a few years from now. Explore where analysts expect LANXESS to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com