


EN
Acerinox (BME:ACX) Posted Stronger Earnings, Is It Still 23% Undervalued?
Acerinox (BME:ACX) is back in focus after third quarter results, with sales of €1,591 million and net income of €85 million, alongside sharply higher nine month earnings.
Acerinox’s share price has retreated in recent weeks, with the stock down 13.14% on a 1 month share price basis and 17.14% over 3 months, even though the year to date share price return is 14.92% and the 1 year total shareholder return is 37.28%. This hints that momentum has cooled after a strong run into today’s €14.94 level.
Scan the recent earnings momentum at Acerinox compared with other potential opportunities by reviewing the curated 224 high quality undervalued stocks that combine solid cash flows with stronger balance sheets.
Recent earnings and a cooling share price put Acerinox in an unusual spot. Has the pullback reset expectations enough that the risk now looks more balanced for new buyers, or is it still tilted the other way?
Most Popular Narrative: 23% Undervalued
Acerinox is framed as undervalued in the prevailing narrative, with a fair value of about €19.35 against the recent €14.94 share price. This puts the spotlight on what has to go right in the business rather than on the latest pullback.
The main factor that has to go right is that Acerinox successfully executes its high-performance alloys growth and efficiency programs, including the planned capacity investments and targeted recurring EBITDA uplift, without letting higher debt and capex weigh on performance.
The numbers imply the share price treats Acerinox as if the identified medium-term EBITDA upside from growth projects, efficiency gains and HPA synergies will not be fully captured, which supports the view that the stock may still be undervalued and that this perspective remains positive.
See why 28 investors see Acerinox as 23% undervalued.
Result: Fair Value of €19.35 (UNDERVALUED)
Still, two pressure points could flip that Acerinox narrative: prolonged weak stainless demand in key regions and net debt of about €1.27b remaining elevated.
Find out about the key risks to this Acerinox narrative.
Another View: What Acerinox’s P/E Is Telling You
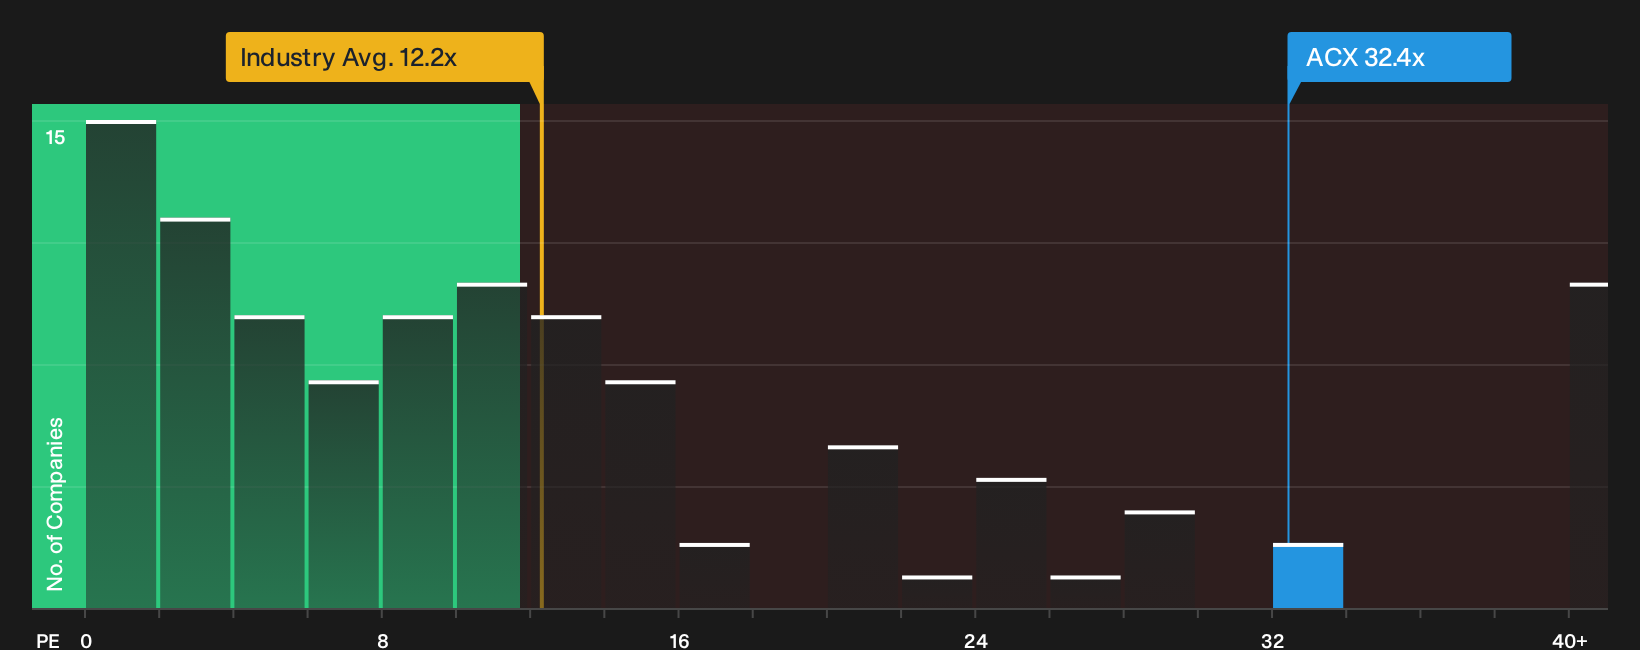
The earlier fair value story presents Acerinox as attractively priced, yet the current P/E of 32.4x sends a different signal. That multiple is far above the European Metals and Mining average of 12.2x, the peer average of 13.6x, and the 29.4x fair ratio that the market could move towards.
If the share price moves closer to that fair ratio or industry levels, today’s premium could compress quickly. The question for you is simple: Is that gap a margin of safety that the DCF has captured, or valuation risk that earnings will need to grow into over time?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sceptical about the mixed signals around Acerinox or leaning optimistic after the recent pullback and valuation debate? Move quickly from reading to evidence and test both sides against the company's 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Acerinox?
Do not stop your research with Acerinox. Broaden your watchlist using targeted screeners that surface opportunities with different strengths before the market focuses on them.
- Target potential income streams by reviewing a curated set of higher yielding payers in the 228 dividend fortresses.
- Focus on financial resilience by scanning the list of solid balance sheet and fundamentals (192 results) so you can concentrate on companies with sturdier fundamentals.
- Look for potential future leaders early by checking the 581 high quality undiscovered gems before attention and pricing adjust.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com