


EN
Heart Device Approval Might Change The Case For Investing In Abbott Stock (ABT)
- Abbott Laboratories recently reported new cardiology and oncology data, including FDA approval of the Amplatzer Paraclose PVL Occluder and positive trial results for Amulet 360, SonicForce IVL and the next-generation Oncodetect MRD cancer test.
- These launches and study readouts point to a heavier emphasis on complex structural heart procedures and ultra-sensitive cancer monitoring. This shift could reshape Abbott Laboratories' product mix, capital needs and regulatory risk profile over time.
- Attention now turns to how Abbott Laboratories' FDA-cleared Paraclose device and broader cardiology pipeline might influence the longer-term investment narrative.
Scan Abbott Laboratories' cardiology push against a curated peer set to see how other device makers with complex heart portfolios stack up in the list of solid balance sheet and fundamentals (25 results).
Abbott Laboratories Investment Narrative Recap
To own Abbott Laboratories you need to believe the device, diagnostics and Nutrition engines can offset legal costs, capital spending and a rich P/E. The key short term swing factor is execution in higher acuity devices like structural heart and electrophysiology, which can influence mix, pricing power and how quickly earnings recover from prior margin pressure.
The near term risk remains legal and regulatory exposure in Nutrition, plus execution risk as Abbott Laboratories layers new cardiac devices on top of an existing portfolio already facing a Class II recall. Recent cardiology and oncology updates look directionally supportive for the product story, but do not alter that central risk reward tension yet.
Among recent headlines, the Amulet 360 VERITAS one year data is most relevant to this cardiology theme. The device posted 96.3% complete left atrial appendage closure on imaging and more than 98% of patients free from ischemic stroke or systemic embolism at one year, reinforcing Abbott Laboratories focus on complex atrial fibrillation related interventions.
That performance, together with CE Mark approval and U.S. investigational status, feeds directly into the catalyst of expanding structural heart and electrophysiology procedures. It also highlights the operational trade off. Deeper involvement in high stakes cardiac care can support higher value device usage, while at the same time increasing regulatory oversight, procedural complexity and potential recall or liability exposure.
Abbott Laboratories' current analyst narrative points to US$60.0b in revenue and US$9.6b in earnings by 2029, based on 8.8% yearly revenue growth and an earnings increase of about US$4.2b from US$5.4b today.
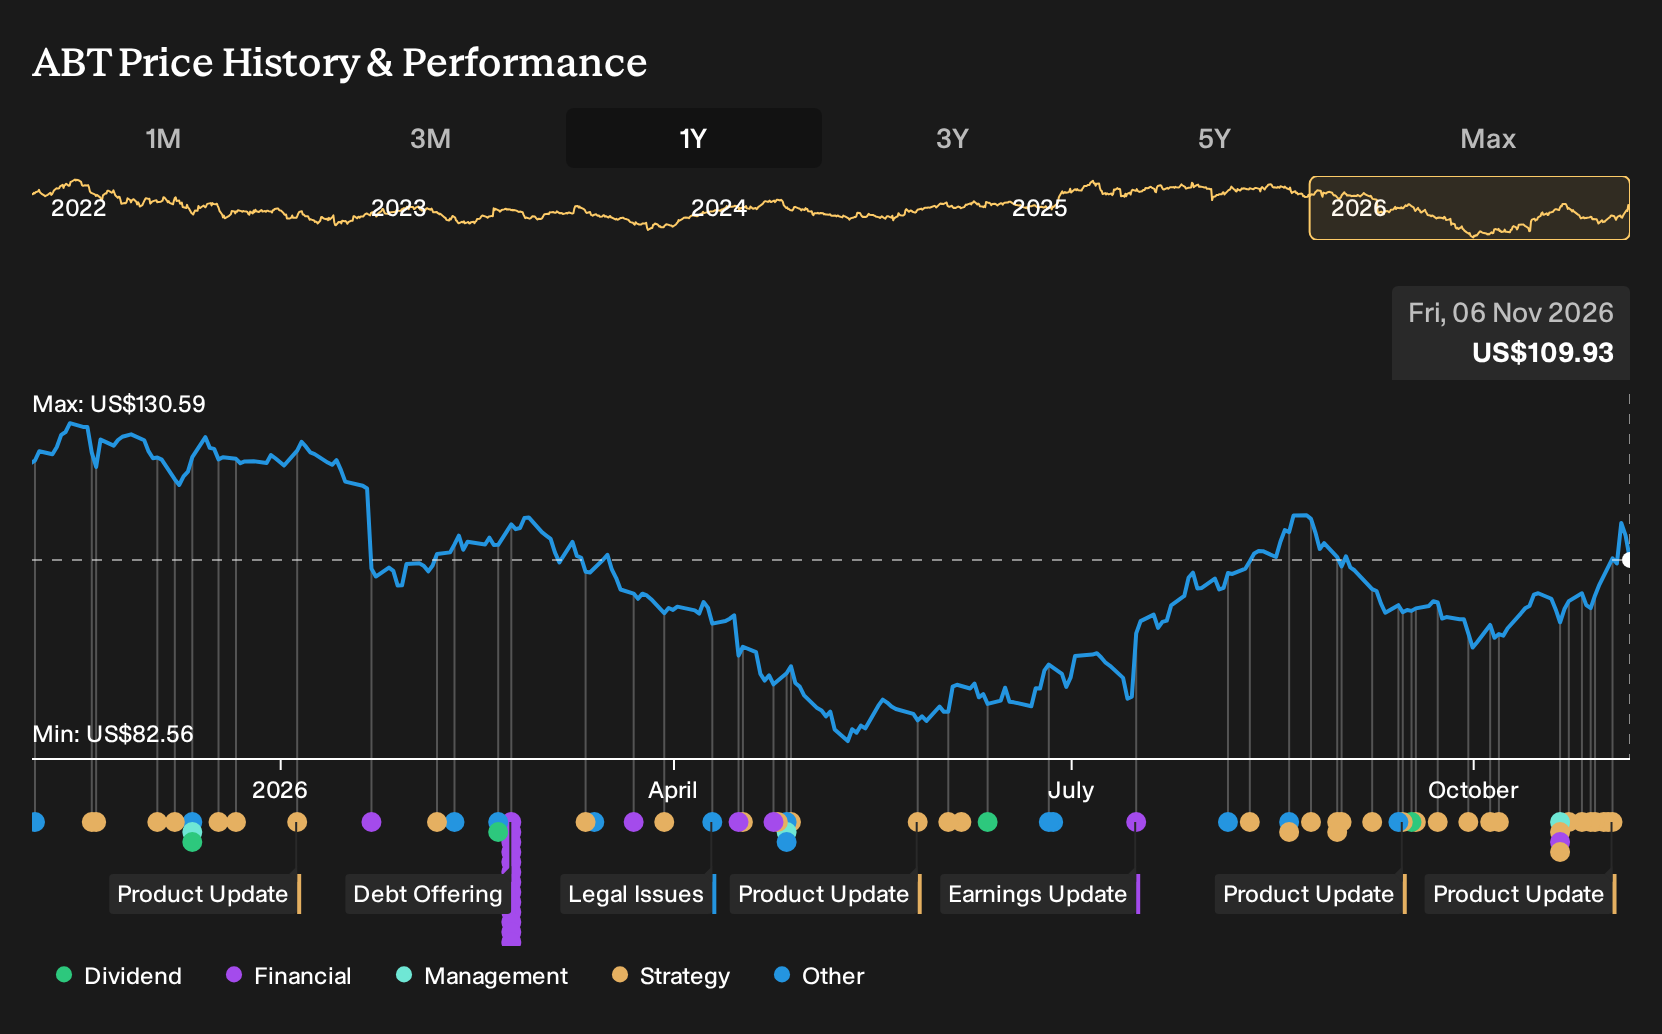
Uncover how Abbott Laboratories' fair value indicates a 9% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Four fair value estimates from the Simply Wall St Community cluster between about US$118.5 and US$151.8, with some members seeing Abbott Laboratories as close to fully priced and others assigning a much richer outlook. Those views sit alongside legal and margin risks in Nutrition and a cardiology pipeline that could alter earnings quality. Investor opinions can differ sharply, so explore several of these community viewpoints before forming your own stance.
Explore 3 other Abbott Laboratories fair value estimates, including one that suggests there could be as much as 38% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Abbott Laboratories research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Abbott Laboratories. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Abbott Laboratories' overall financial health at a glance.
Looking for more investment ideas beyond Abbott Laboratories?
If Abbott Laboratories is on your radar, it can help to compare it with other companies that have different risk, income and balance sheet profiles. Use the Simply Wall St Screener to quickly surface ideas that match the kind of portfolio you want to build.
- If you are hunting for potential mispricing, review companies flagged in the 38 high quality undervalued stocks to see which ones meet your quality and valuation thresholds.
- If income stability matters most to you, focus on businesses in the 7 dividend fortresses and check whether their payouts line up with your return goals.
- If balance sheet strength is your priority, scan the 31 resilient stocks with low risk scores to find candidates with more resilient financial profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com