


EN
Omada Health (OMDA) Lifted Guidance, Is It Still 47% Undervalued?
Omada Health (OMDA) drew fresh attention after raising its 2026 revenue outlook to US$344 million to US$346 million, and reporting record third quarter revenue of US$91.31 million and net income of US$6.55 million.
Despite the stronger outlook, Omada Health’s share price has slid, with a 1-day share price return that declined 20.37% and a 30-day share price return down 27.52%. The year-to-date share price return is slightly positive at 1.28%, while the 1-year total shareholder return is down 25.70%. This points to fading momentum even as recent earnings and guidance shifts reset expectations around growth potential and risk.
Spot 35 healthcare AI stocks that, like Omada Health, are trying to turn virtual care, chronic disease programs, and AI-driven efficiencies into durable scale rather than short-lived share price spikes.Omada Health just lifted its long term revenue outlook, yet the stock dropped sharply on the news. Does that reset give you an early entry opportunity, or is patience the better risk control before the valuation work starts?
Most Popular Narrative: 47% Undervalued
Omada Health closed at $15.09, while the most followed narrative framework pegs fair value at about $28.42, which implies a wide gap that investors now need to explain using the long term story, not the last trading day.
Scaling GLP-1 prescribing alongside the existing GLP-1 Care Track positions Omada as a key coordinator for rapidly expanding obesity therapies, supporting higher average revenue per member and sustained revenue growth.
Deeper integration of AI tools like OmadaSpark, Meal Map and the care team platform should raise coach productivity and member engagement, improving operating leverage and supporting long term expansion in gross margin and EBITDA.
See why 7 investors see Omada Health as 47% undervalued.
The valuation work behind that fair value uses a 7.24% discount rate and blends together revenue, margin and cash flow expectations into a single present value number rather than leaning on a simple P/E shortcut.
Analysts in that framework see Omada Health as undervalued by about 47%, yet the stock has also been weak over 3 and 12 months, so the gap between price and this narrative view reflects both optimism about future earnings power and clear market hesitation around execution, GLP-1 exposure and capital needs.
Result: Fair Value of $28.42 (UNDERVALUED)
Still, the Omada Health story depends heavily on GLP-1 related demand, and a major 2026 investment year could weigh on margins if execution disappoints.
Find out about the key risks to this Omada Health narrative.
Another View On Omada Health’s Valuation
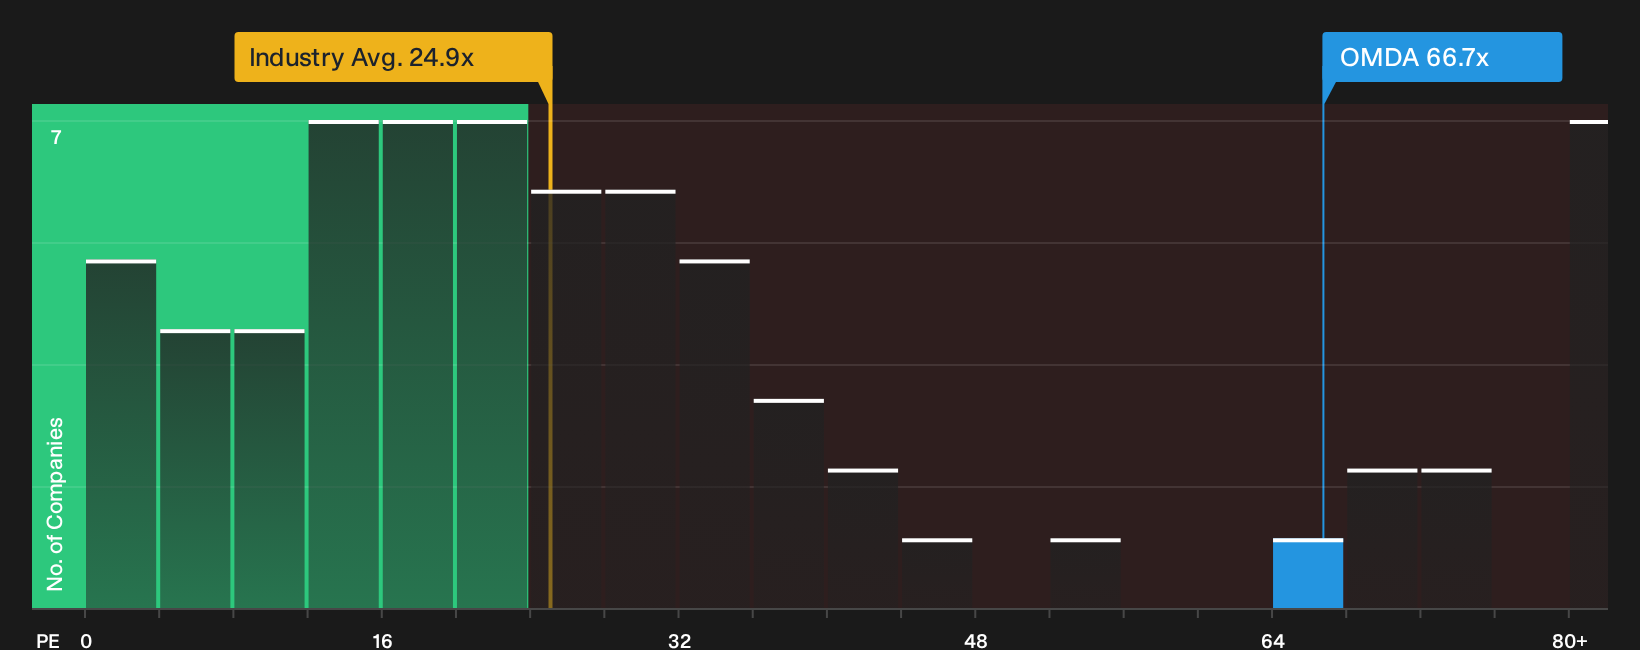
That 47% gap between Omada Health’s share price and the fair value narrative is big, but the market is also looking at the current P/E of 66.7x. Peer companies sit closer to 56x, while the fair ratio sits at 43.8x, which points to richer pricing today. Does that premium feel earned to you, or more like valuation risk building up?
See what the numbers say about this price in our valuation breakdown, then compare how that P/E gap lines up with your own expectations for Omada Health’s future cash generation and competitive position. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty in Omada Health’s story points both ways right now, with fresh guidance on one side and valuation questions on the other. Act quickly, review the full picture yourself, and weigh up both the upside and the downside using 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Omada Health?
If Omada Health has sharpened your focus on quality, do not stop here. Broader watchlists often surface opportunities that single-stock research simply misses.
- Explore a wider opportunity set by scanning the market for focused growth candidates using the 9 elite penny stocks with strong financials.
- Look for potentially attractive pricing by examining mispriced businesses through the 38 high quality undervalued stocks.
- Emphasise financial strength by filtering for sturdier balance sheets and stronger fundamentals with the list of solid balance sheet and fundamentals (25 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com