


EN
Liberty Global (LBTYA) Stock Still Looks Undervalued Following A 33% Five Year Fall
Liberty Global has just come through a sharp share price bounce, which puts fresh attention on whether the current valuation lines up with what its sales can realistically support. After a move like that, the obvious question for you is how much of the business's revenue power is already reflected in the US$9.90 share price.
- Over the past 5 years the stock has fallen 33.1%, which keeps the spotlight on whether investors are now paying a sensible price for a business that has already put long term holders through a tough stretch.
- The group relies heavily on subscription style telecom and media revenue. This can support steadier sales, but it also means any pressure on customer growth or pricing can quickly affect what investors may be willing to pay for each dollar of top line.
- The analysts covering Liberty Global have run their own numbers. See what analysts think Liberty Global's shares could be worth.
The issue now is whether Liberty Global's current share price is adequately backed by its sales based valuation.
If you want to test the same sales based valuation question across more than one ticker, widen the lens using 38 high quality undervalued stocks.
Does Liberty Global Look Undervalued on Sales?
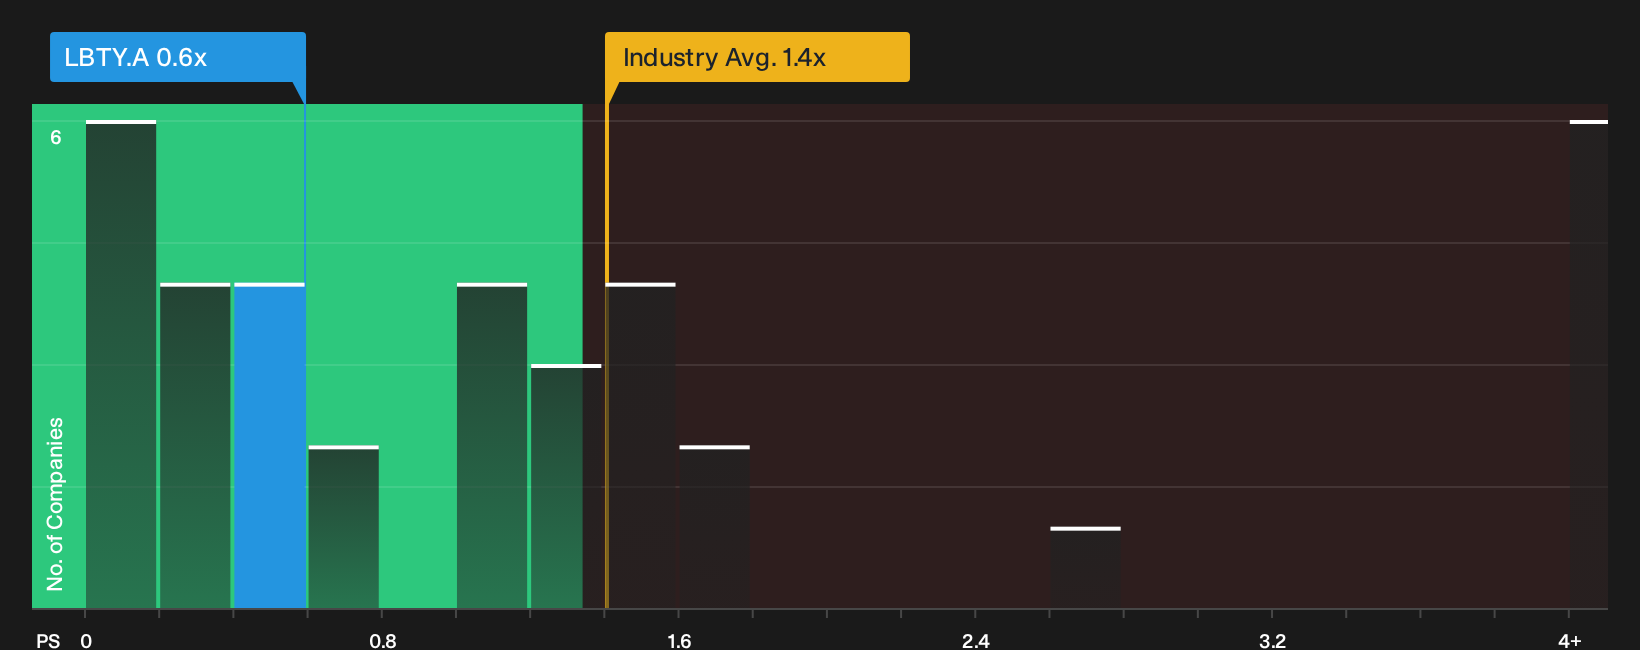
P/S makes sense for Liberty Global because investors are essentially paying for an established pool of subscription revenue rather than near term earnings. On this yardstick, the stock trades at a P/S of 0.6x, well below the broader telecom industry average of 1.4x and also under the peer group on about 1.9x. For a business built on recurring telecom and media contracts, that is a low sales tag compared with what the market currently pays for similar revenue elsewhere.
The tailored fair multiple, which reflects Liberty Global's specific mix of growth prospects, margins, scale and risk, also sits above the current 0.6x level. That gap suggests the market price is not fully crediting each dollar of sales at the level implied by those fundamentals, so the shares screen undervalued on this P/S framework. Explore the numbers behind Liberty Global's P/S valuation.
The Liberty Global Narrative: What Would Justify Today's Price?
Narratives on Simply Wall St act as the bridge between Liberty Global's low P/S multiple and what that might imply for its future growth, margins and earnings. They spell out the set of operating outcomes that would need to play out for the valuation puzzle to lean higher or lower than today's share price. Where a single ratio or model gives one headline figure, these storylines unpack the future that figure rests on so you can track whether it keeps lining up with reality over time.
Liberty Global splits opinion, with some investors focused on discounted assets while others fixate on leverage, cash strain and execution risk.
Bull case: 17% undervalued
"Liberty Global ($LBTYA) closed October 16 at $7.80 per share, putting the combined market value of its three share classes below $3 billion..."
Discover why this Narrative puts Liberty Global at 17% undervalued.
Bear case: 41% overvalued
"While Liberty Global has raised about US$1.2b of additional liquidity year to date through asset disposals and an asset backed loan and now targets US$2b of corporate cash by year end 2026, reliance on such transactions to support the balance sheet and fund commitments can point to a business that still needs portfolio sales rather than internal cash generation to cover investment needs..."
Explore why this Narrative puts Liberty Global at 41% overvalued.
One more Liberty Global factor that deserves your attention
Price tags and storylines only go so far. Research on Liberty Global has also highlighted specific checks that raise concerns, and any investor weighing this stock will likely want to see what those are. Take a closer look at 1 warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com