


EN
How Investors May Respond To TDS Stock Buyback Expansion
- Telephone and Data Systems reported Q3 2026 earnings in early November, with net income returning to profit, record fiber build activity, updated 2026 guidance, and a new US$250 million share repurchase authorization alongside previously completed buybacks.
- The mix of renewed profitability and aggressive fiber investment, paired with fresh capital returns, places Telephone and Data Systems' balance between growth spending and shareholder payouts under close scrutiny.
- We will examine how Telephone and Data Systems' investment narrative is reshaped by renewed profitability together with an additional US$250 million buyback.
Scan how Telephone and Data Systems' renewed profitability and fresh buyback compare with other potential opportunities by reviewing a hand-picked shortlist of 38 high quality undervalued stocks.
Telephone and Data Systems Investment Narrative Recap
To own Telephone and Data Systems, you need to be comfortable with a simple idea. The future hinges on fiber and towers offsetting pressure in older copper and cable services. The Q3 report showed net income back in positive territory, yet telecom revenue guidance for 2026 has been cut, so top line momentum is still under strain.
In the short term, the key swing factor is whether record fiber deployment and cost work can narrow the gap with shrinking legacy lines. The main risk remains that higher capital spending on fiber, combined with weaker legacy revenue, keeps earnings and free cash flow under pressure for longer than hoped.
The fresh US$250 million share repurchase authorization sits beside the almost fully used US$520 million program completed by September 2026. That is a large commitment relative to Telephone and Data Systems' roughly US$3.8b market value, and it comes at a time when the group is leaning harder into fiber construction and higher capex.
For you, the repurchase plan matters because it competes directly with fiber investment for capital. If execution on broadband builds and cost savings stays on track, buybacks can amplify per share metrics. If legacy copper and cable declines or tower tenant loss weigh more heavily, aggressive repurchases could leave less flexibility to absorb a tougher stretch.
According to the current analyst narrative for Telephone and Data Systems, revenues are projected to be US$1.3b and earnings US$225.1 million by 2029, with revenue expected to remain broadly flat and earnings projected to decline by about US$242.3 million from US$467.4 million today.
Uncover how Telephone and Data Systems' fair value indicates a 45% potential upside to its current price that could narrow quickly.
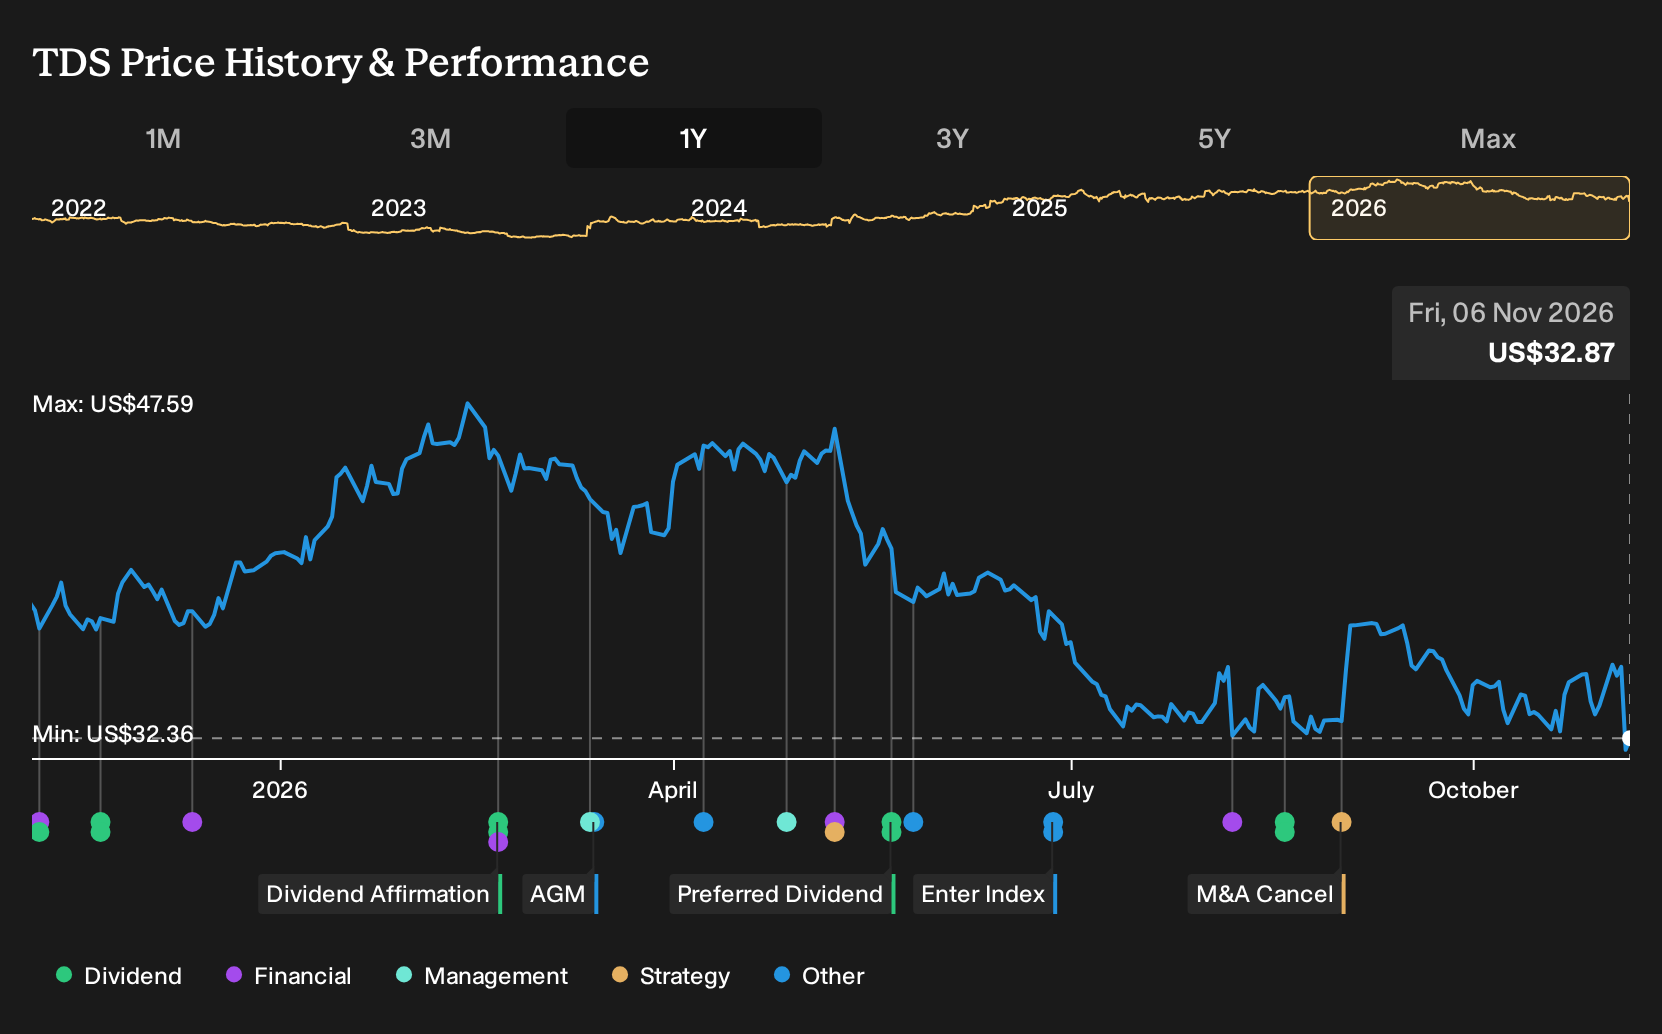
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span a wide band, from about US$1.89 up to US$47.50 per Telephone and Data Systems share, which shows how far opinions can stretch. You are weighing these views against risks such as legacy copper pressure, as well as catalysts including fiber rollouts and tower contracts. Expect disagreement and explore several of these viewpoints before deciding where TDS fits in your portfolio watchlist.
Explore another Telephone and Data Systems fair value estimate, including one that suggests as much as 94% downside from the current price!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Telephone and Data Systems research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Telephone and Data Systems. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Telephone and Data Systems' overall financial health at a glance.
Looking for more investment ideas beyond Telephone and Data Systems?
Once you have a view on Telephone and Data Systems, it can help to compare that thesis against a wider watchlist, so you see where the risk, balance sheets, and income profiles look more or less comfortable for you.
- If downside protection is a priority, start with companies that screen for resilience through 31 resilient stocks with low risk scores that may better match your tolerance for volatility.
- For investors who care most about financial strength, test your standards against a list of solid balance sheet and fundamentals (25 results) and see which businesses clear that bar.
- If you want ideas that are not already crowded, scan a 19 high quality undiscovered gems that pairs quality fundamentals with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com