


EN
Bloom Energy (BE) Stock May Look Fully Priced Following Its 900 MW Power Deal
Bloom Energy has seen its share price swing sharply in both directions, and the question for you now is whether the current valuation can be squared with what the company is actually earning. Recent price moves and headline deals have reset expectations, so the issue is how much of that story is already embedded in the stock.
- Over the past three years the stock has delivered a very large gain of about 15x. That places significant emphasis on whether the earnings profile can support that kind of re-rating.
- The 900 MW agreement with NTT DATA and other data center and decarbonization projects may support higher long term revenue and profit expectations. This feeds directly into how much investors are prepared to pay for each dollar of earnings.
- Your read on Bloom Energy is one view; the desks covering it have another. See what analysts think Bloom Energy's shares could be worth.
The stock's next move may depend on whether Bloom Energy's current share price can be justified by its earnings using this lens.
If you want a broader starting point for research around AI power and data center themes, run a screen on 53 AI infrastructure stocks.
Does Bloom Energy Look Pricey on Earnings?
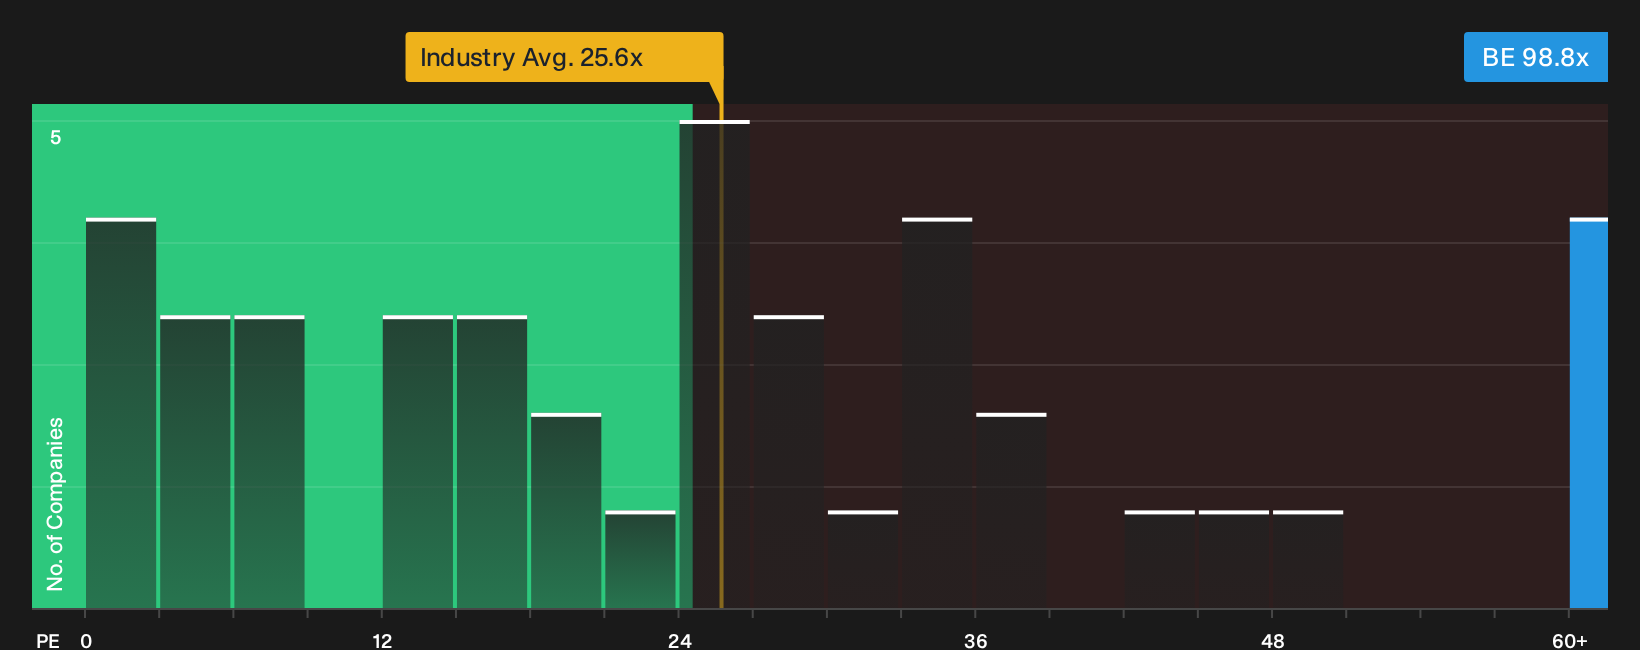
P/E suits Bloom Energy because earnings now exist to anchor the share price rather than just sales or assets. On this metric the stock trades around 98.8x, which is far above the broader electrical equipment industry near 25.6x and also ahead of the peer group near 58.7x. That kind of gap means investors are paying a much higher price for each dollar of profit than is common across the sector.
The valuation model that blends Bloom Energy's growth profile, margins, size and risk points to a lower P/E as a more tailored reference. As a result, the current 98.8x screens as overvalued on this framework. Despite the large 900 MW NTT DATA agreement lifting expectations around data center power demand, the multiple already assumes a rich earnings trajectory compared with what the model implies as a more balanced entry level. Explore the numbers behind Bloom Energy's P/E valuation.
The Bloom Energy Narrative: What Would Justify Today's Price?
Bloom Energy's valuation puzzle sets up the role of Simply Wall St Narratives, which map out what would need to happen to growth, margins and earnings for the stock to be worth meaningfully more or less than it is today, and sit on the Community page. Instead of a single model output, Narratives describe the future path those numbers rely on so you can watch how closely reality tracks the scenario you are using.
Community views on Bloom Energy are split between those who see a long runway and those who think expectations already stretch the story.
Bull case: 55% undervalued
"The Bloom Energy story is still early days, and so many areas for their growth, international and other market segments, are largely untapped…"
Discover why this Narrative puts Bloom Energy at 55% undervalued.
Bear case: 22% overvalued
"Bearish analysts expect Bloom Energy to face funding and execution setbacks on giga-scale AI data center projects, with share price declines around September 2026 seen as a sign that enthusiasm for the build-out story could run ahead of actual deployments…"
Explore why this Narrative puts Bloom Energy at 22% overvalued.
Bloom Energy’s price is only one piece of the decision
Bloom Energy’s share price and P/E are just the surface. Beneath that, our research has flagged specific checks that raise questions investors may want to weigh before going further. Take a closer look at 3 warning signs before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com