


EN
Amylyx Pharmaceuticals (AMLX) Stock Still Trades At A Premium As Phase 3 Progress Advances
Amylyx Pharmaceuticals has surged on strong trial news and investor interest, and the question now is whether a move like this can be squared with what the balance sheet says the business is worth on paper. With Amylyx stock already pricing in a lot of optimism, the focus turns to how that share price lines up against its book value and the broader industry average.
- Amylyx is up 158.3% year to date, which puts real pressure on investors to ask how much of that jump is backed by its underlying net assets.
- Positive Phase 3 LUCIDITY results for avexitide and a cash position reported at US$768.1m after a US$545m equity raise can affect how investors weigh future capital needs against current book equity.
- Your read on Amylyx Pharmaceuticals is one view; the desks covering it have another. See what analysts think Amylyx Pharmaceuticals's shares could be worth.
The issue now is whether Amylyx Pharmaceuticals' recent share price is adequately supported by its book value when compared with the industry average.
If you want to test this same book value question across a wider set of opportunities, you can scan through 38 high quality undervalued stocks.
Has Amylyx Pharmaceuticals Run Too Far on Book Value?
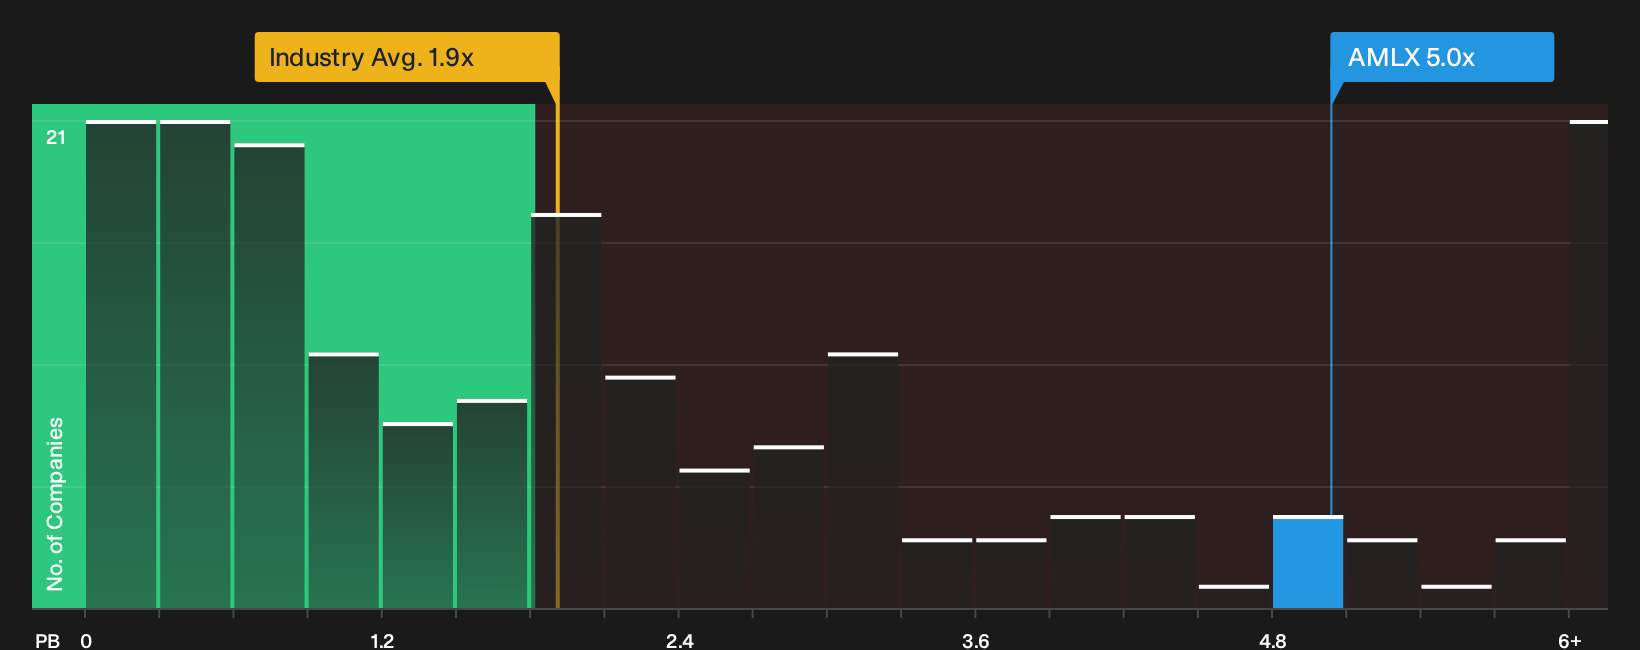
P/B suits Amylyx Pharmaceuticals because the balance sheet and cash position are front and center after the recent equity raise. The stock trades on a P/B of 5.0x, which is well above the Pharmaceuticals industry average of 1.9x and also above the peer group on 3.8x. That gap signals investors are paying a clear premium to the sector for each dollar of net assets on Amylyx's books.
Because the Phase 3 LUCIDITY data and strong cash balance have lifted expectations, that premium looks ambitious rather than conservative when judged against the wider industry. The P/B multiple therefore points to Amylyx stock pricing in a rich valuation relative to typical Pharmaceuticals peers, and any holder needs to weigh how much confidence they have that the current pipeline justifies that higher bar. Explore the numbers behind Amylyx Pharmaceuticals's P/B valuation.
The Amylyx Pharmaceuticals Narrative: What Would Justify Today's Price?
Narratives for Amylyx Pharmaceuticals pick up where the price to book puzzle leaves off and explain which paths for growth, profitability and earnings would need to occur for the shares to be worth materially more or less than they are today on the market. Rather than relying on a single ratio or model output, they describe the future performance underlying that figure so you can watch whether the real Amylyx Pharmaceuticals story continues to align with those expectations.
Bullish holders see Amylyx Pharmaceuticals as building a rare disease franchise, while skeptics think expectations for avexitide and PBH are already stretched.
Bull case: 48% undervalued
"Bullish analysts expect Amylyx Pharmaceuticals to turn avexitide and its broader rare disease pipeline into a durable PBH and endocrine franchise..."
Discover why this Narrative puts Amylyx Pharmaceuticals at 48% undervalued.
Bear case: 24% overvalued
"Bearish analysts caution that current targets already bake in optimistic assumptions on avexitide pricing and uptake, which could leave limited room for upside..."
Explore why this Narrative puts Amylyx Pharmaceuticals at 24% overvalued.
Amylyx Pharmaceuticals: One More Piece Before You Decide
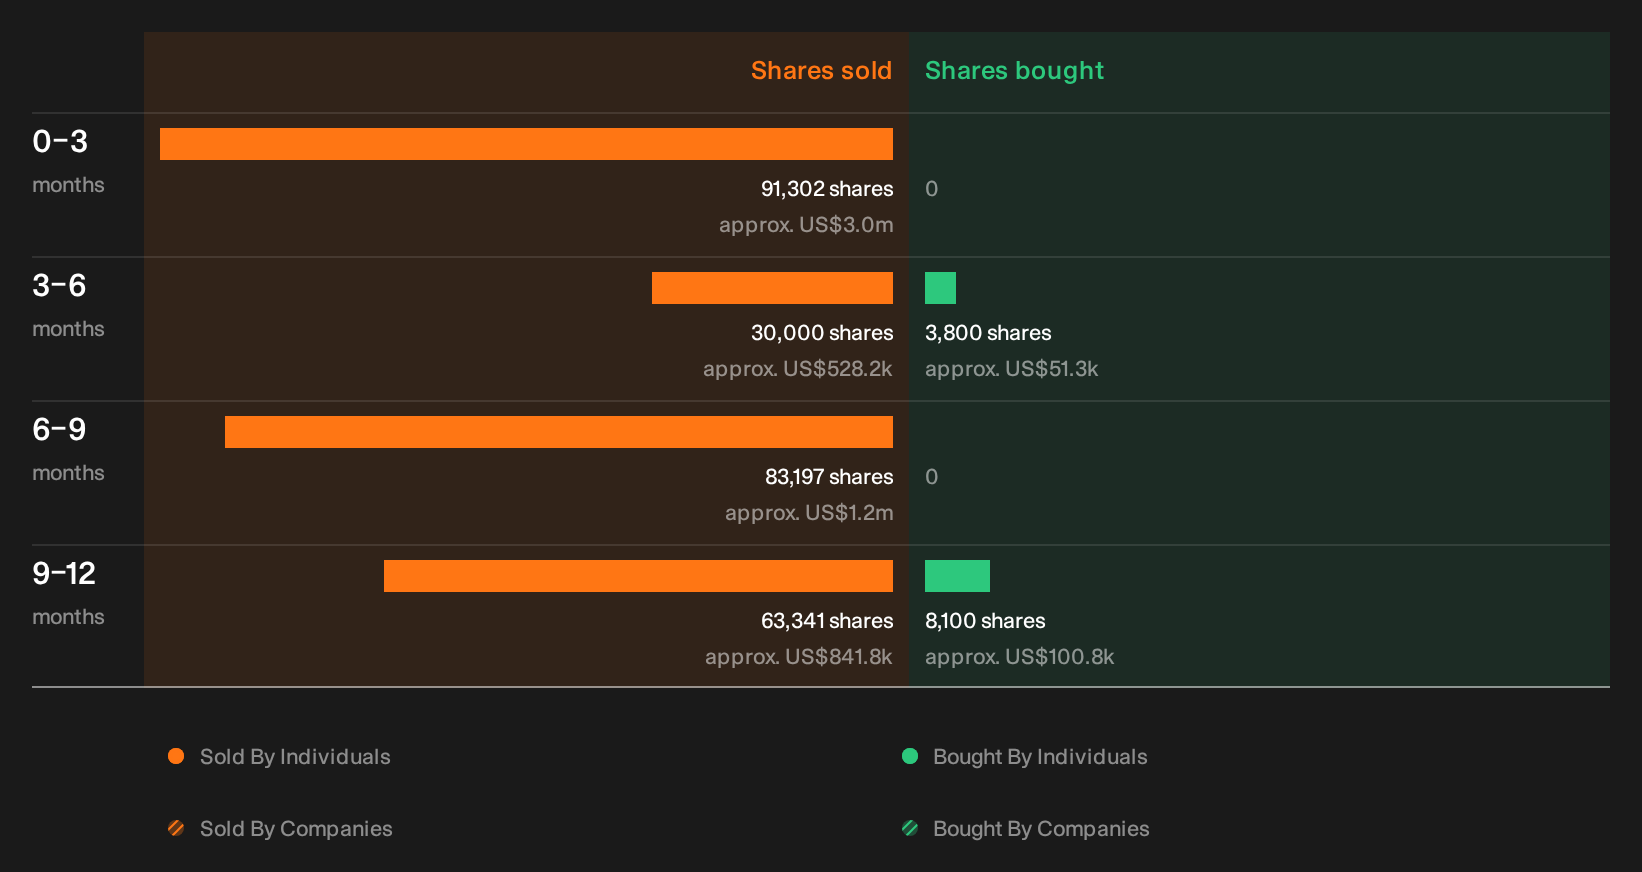
Price, book value and pipeline expectations only tell part of the Amylyx Pharmaceuticals story. Recent trading by people inside the business can offer a very different clue about conviction, and the specific sellers, sizes and context are all laid out for you to review. See the recent insider selling flagged for Amylyx Pharmaceuticals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com