


EN
Red Violet (RDVT) Could Be 17% Undervalued On Record Q3 Revenue And Profit Growth
Why Red Violet’s latest earnings are drawing fresh attention
Red Violet (RDVT) has just posted third quarter 2026 results with higher sales, earnings and customer additions, alongside continued spending on its data platform and AI driven products. That mix is now shaping how traders view the stock.
Despite the upbeat Q3 figures and talk of potential M&A on 4 November 2026, Red Violet’s share price has pulled back, with the stock down 12.1% on a 30 day share price return and 12.4% over 7 days, yet still showing a 36.5% year to date share price gain and a 278.2% three year total shareholder return. This suggests that recent weakness may reflect a pause in a multi year run rather than a collapse in confidence.
Scan beyond Red Violet to see how it compares with other fast-growing software and data plays in our hand picked 19 high quality undiscovered gems universe.
The Q3 beat, clean balance sheet and fresh pullback now converge in a single question. At around $70 a share, does Red Violet still offer an appealing risk reward, or has optimism already been priced in?
Most Popular Narrative: 17% Undervalued
Red Violet’s most followed narrative pins fair value at $84.50, above the latest $70.10 close. This naturally sharpens focus on whether that gap is justified by execution on its volume driven model and AI investment plans.
The main factor that has to go right is that Red Violet successfully uses its AI-enabled identity graph and strong balance sheet to deepen adoption in larger enterprise, public sector, and new vertical workflows while maintaining high gross margins and solid customer retention.
The current valuation implies that Red Violet is fairly valued and already reflects volume-based growth with high-30s adjusted EBITDA margins and continued execution on AI, workflow expansion, and upmarket customer mix.
See why 10 investors see Red Violet as 17% undervalued.
Result: Fair Value of $84.50 (UNDERVALUED)
Still, the Red Violet thesis can be knocked off course if higher AI spending keeps margins stuck, or if softer retention and real estate usage drag on volume.
Find out about the key risks to this Red Violet narrative.
Another view on Red Violet’s valuation
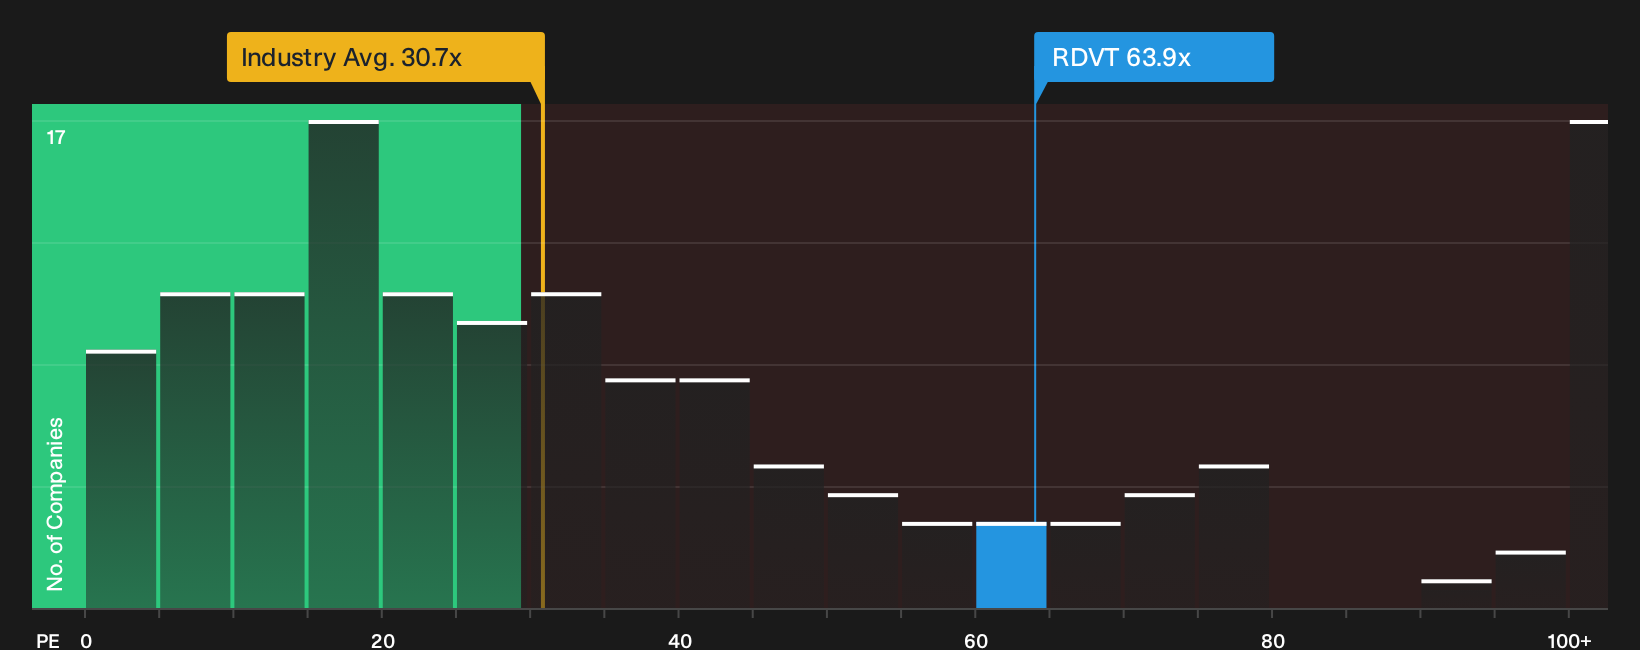
The first narrative leans on cash flow and earnings forecasts to argue Red Violet looks 17% below a fair value of $84.50. A very different picture comes from simple market ratios. At a P/E of 63.9x, RDVT trades at more than double the US Software sector on 30.7x and far above its own fair ratio of 23.9x. That gap points to meaningful valuation risk if sentiment cools or growth expectations ease. Which signal do you give more weight to when both are on the table?
For a closer look at how the current P/E stacks up against that fair ratio and sector peers, review the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If sentiment around Red Violet feels split, treat that as your cue to dig into the numbers yourself and decide where you stand. To see why optimism still clusters around specific strengths, review the 3 key rewards.
Looking for more investment ideas beyond Red Violet?
Do not park all your attention on a single ticker. Use Red Violet as a reference point, then widen your watchlist with targeted stock ideas that fit your style.
- Spot potential bargains early by scanning a focused group of companies that screen as quality yet priced as 38 high quality undervalued stocks.
- Prioritise resilience by zeroing in on businesses with sturdy finances using the list of solid balance sheet and fundamentals (25 results) to filter for balance sheet strength.
- Build your income stream with a curated pool of higher yielding payers by reviewing the 7 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com