


EN
Did Leadership Reshuffle Just Shift ABM Industries (ABM) Investment Narrative?
- ABM Industries reported a leadership shakeup as long time Chief Operating Officer Rene Jacobsen retired, while Richard Sykes and Mark Hawkinson stepped into newly created roles overseeing Facility Solutions and Engineering & Infrastructure Solutions across the United States, United Kingdom, and Ireland.
- The reorganization concentrates cleaning, maintenance, parking, transportation, and technical infrastructure services under two global leaders. This structure directly targets how ABM Industries aligns its resources, service mix, and execution quality with evolving client demand across key end markets.
- Attention now shifts to how ABM Industries' investment narrative intersects with this new Facility Solutions leadership structure and its broader technical focus.
ABM Industries Investment Narrative Recap
To own ABM Industries, you need to be comfortable with a facilities giant that is tilting harder into higher margin technical work while still running a large, lower margin labor heavy services base. The near term story hinges on how well management turns its data center, semiconductor and microgrid backlog into cleanly executed contracts without eroding pricing.
That is where the leadership change matters. Splitting Facility Solutions and Engineering & Infrastructure under Richard Sykes and Mark Hawkinson concentrates accountability around execution and mix. The biggest risk remains a slowdown or weaker conversion in those higher value technical pipelines. This reshuffle looks material mainly for how quickly or smoothly that technical revenue shows up.
The most relevant backdrop to this reorg is the reported build up in data center work. ABM Industries has seen its data center pipeline and backlog with co location customers reach multiples of prior year levels, with 8% organic revenue growth in that area year to date in FY26. For you as a shareholder, the question is simple: Can this be installed on time and on budget?
Putting Hawkinson over Engineering & Infrastructure ties that expanding pipeline directly to an executive already running facility infrastructure, mechanical, microgrids and energy solutions. Execution quality here feeds straight into the core catalysts analysts highlight, including a greater share of earnings from technical end markets and the potential for stronger consolidated margins over time. Missed timelines or cost creep would cut the other way and weigh on the thesis.
ABM Industries' current analyst narrative points to revenues of US$10.1b and earnings of US$272.9m by 2029, based on revenue growth of 3.3% a year and an earnings increase of about US$106.5m from earnings today of US$166.4m.
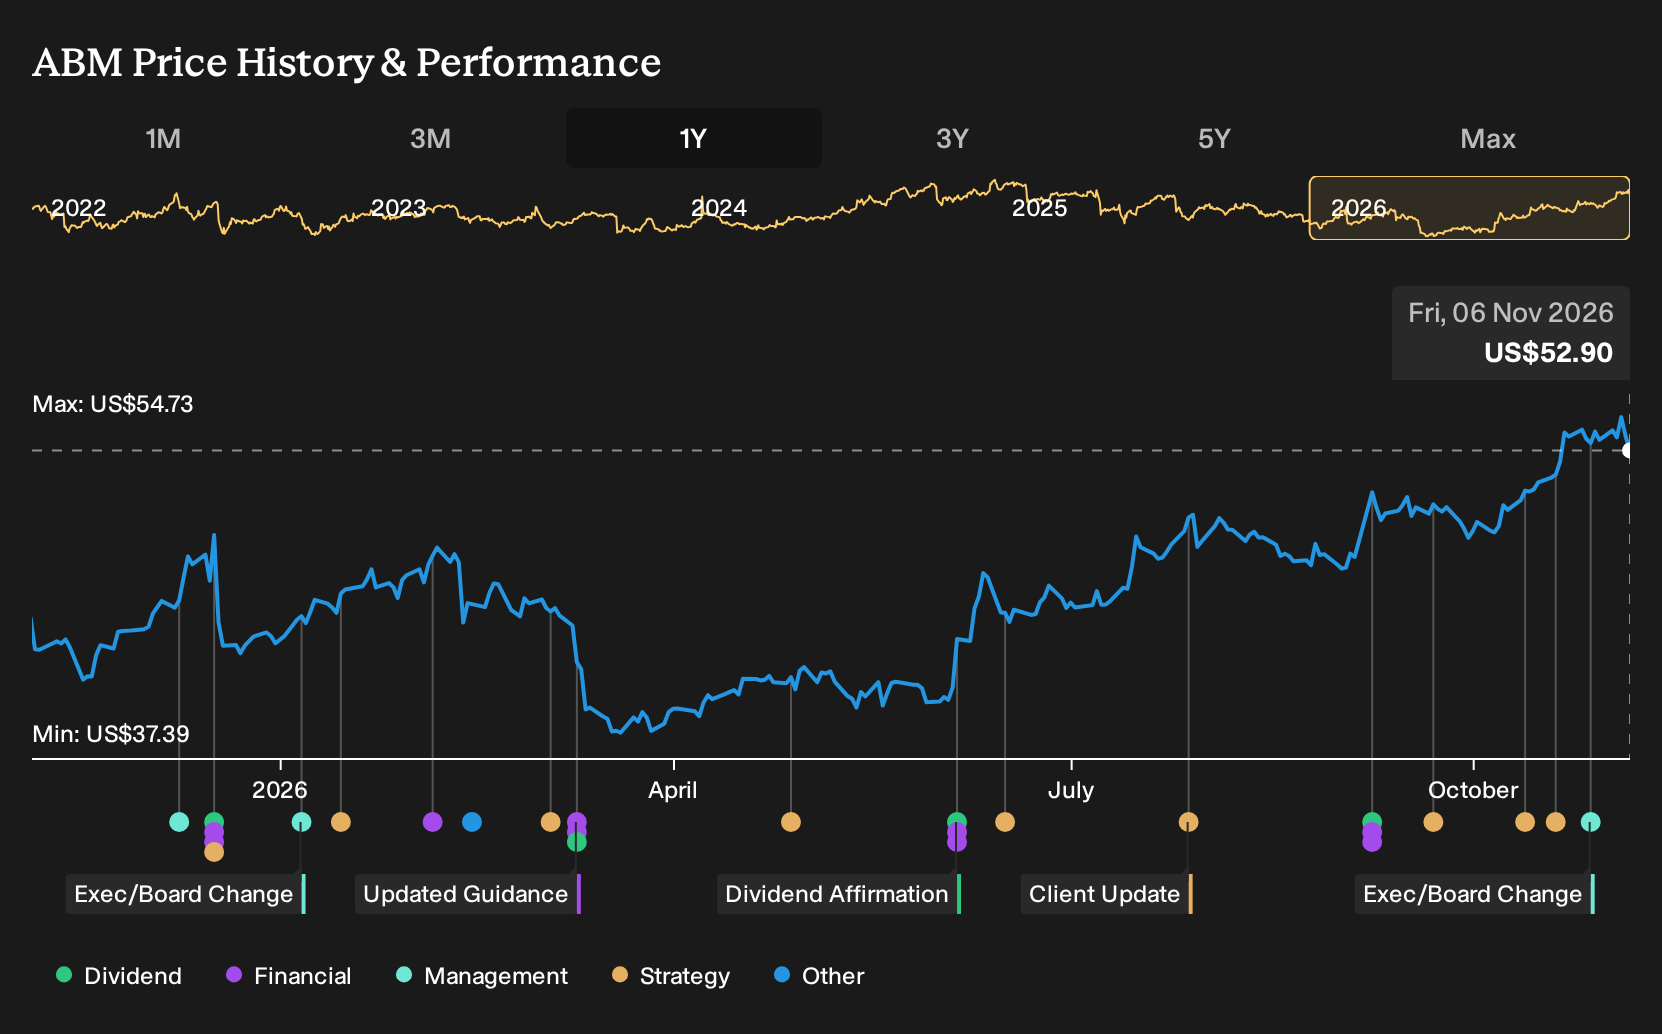
Uncover how ABM Industries' fair value indicates a 6% potential upside to its current price, which could narrow quickly as investors reassess ABM Industries' setup.
Exploring Other Perspectives
One bullish twist on ABM Industries focuses on upside from Technical Solutions rather than execution risk. The most optimistic analysts were already penciling in revenue of about US$10.2b and earnings of roughly US$277.0m by 2029 before this leadership shakeup. You can treat those richer forecasts as one end of a wide opinion range that may shift as the new structure settles in.
Explore another ABM Industries fair value estimate, including one that suggests as much as 87% upside from the current price!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your ABM Industries research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for ABM Industries. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ABM Industries' overall financial health at a glance.
Looking for more investment ideas beyond ABM Industries?
If the ABM Industries story has sharpened your thinking, broaden your watchlist by scanning for other companies that match the type of risk and return profile you want, using the Simply Wall St Screener as a jumping off point.
- For potential value opportunities with quality fundamentals already in place, review a curated set of 38 high quality undervalued stocks that pair healthy balance sheets with supportive cash flows.
- If capital protection and steadier profiles matter more to you than rapid upside, focus on companies in the 31 resilient stocks with low risk scores that screen well on financial stability and risk metrics.
- To widen your opportunity set with lesser known prospects, scan the 19 high quality undiscovered gems that couple strong underlying numbers with relatively low market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com