


EN
Is Stronger Earnings Altering The Investment Case For RBI Stock?
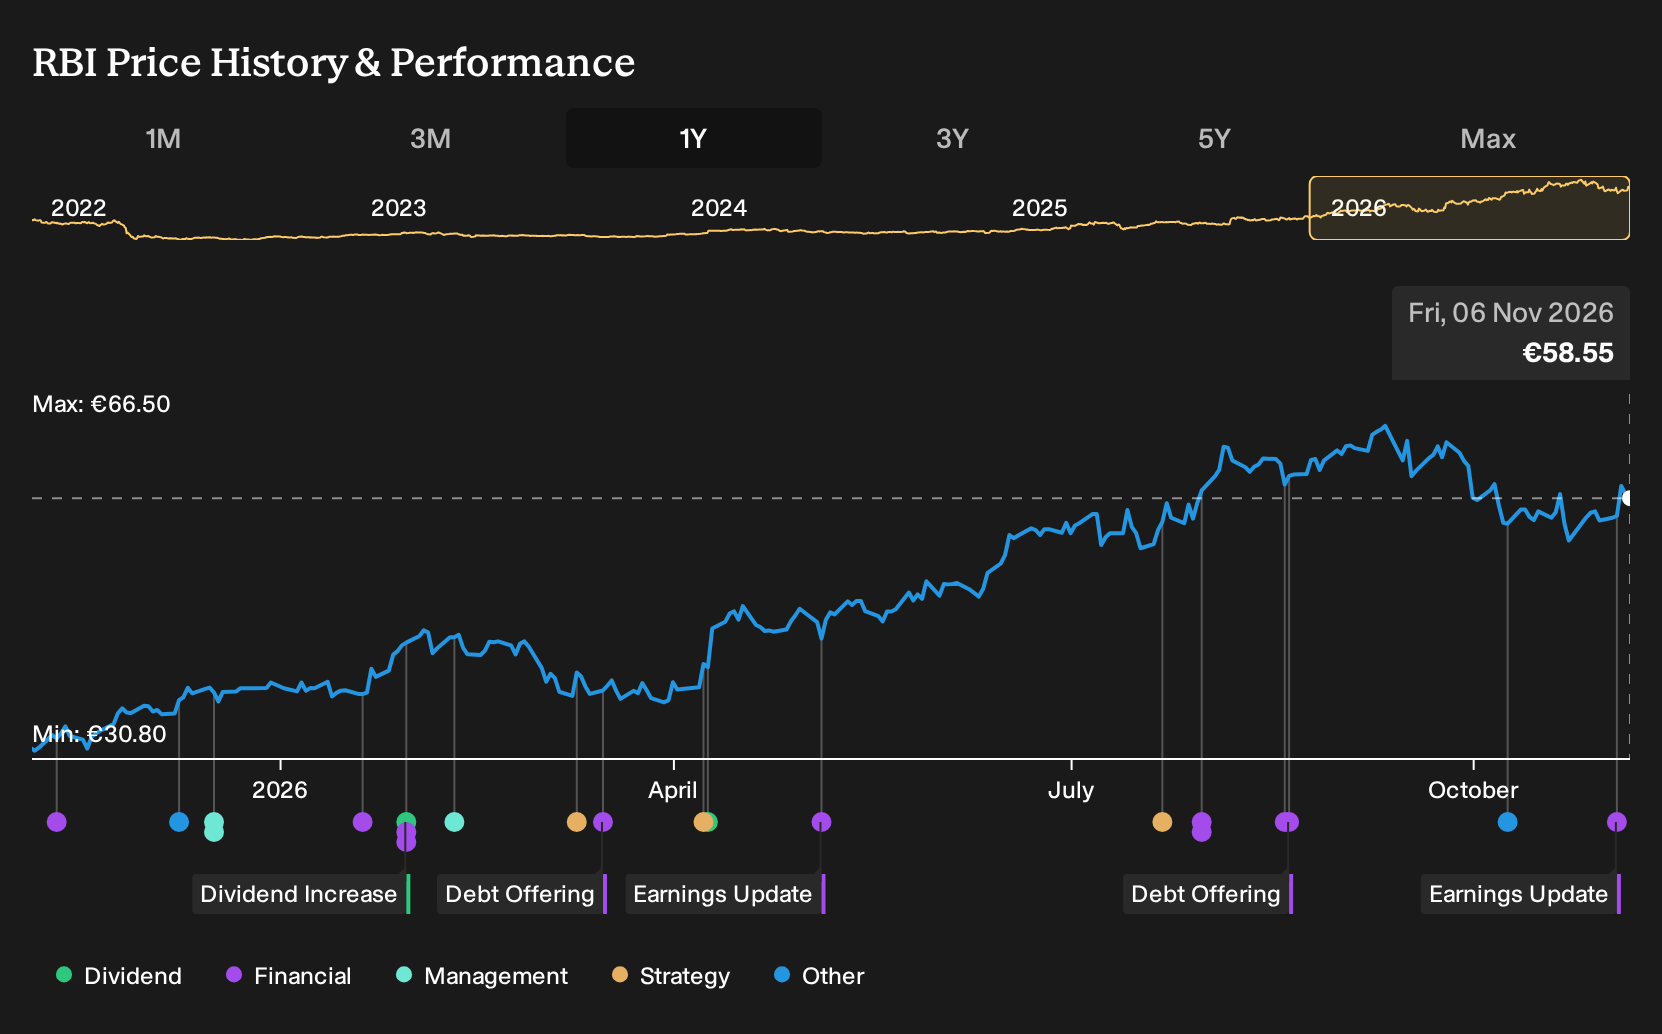
- Raiffeisen Bank International reported earnings for the nine months to 30 September 2026, with net interest income of €4,544 million, net income of €1,638 million, and basic earnings per share from continuing operations of €4.71.
- For the core group excluding Russia, consolidated profit rose 10% year on year to about €1.1 billion, supported by record quarterly net interest income, strong asset quality, and a record low 1.5% non performing loan ratio. Management expects recent acquisitions to support future financial metrics.
- We will now explore how Raiffeisen Bank International's record net interest income shapes the existing investment narrative and risk reward balance.
Scan how Raiffeisen Bank International's earnings story compares with other resilient lenders by reviewing our curated list of solid balance sheet and fundamentals (192 results) in one place.
Raiffeisen Bank International Investment Narrative Recap
For Raiffeisen Bank International, the core belief for shareholders is that the Central and Eastern Europe franchise can keep generating solid net interest income and resilient credit quality while legacy issues are worked through. The latest nine-month figures, with net income of €1,638 million and basic EPS of €4.71 from continuing operations, indicate that the operating engine is intact.
The near-term swing factor is still how cleanly Russia exposure, Polish litigation and higher costs are contained against this earning power. Record net interest income in Q3 and a low 1.5% non-performing loan ratio in the core group help, but trapped Russian capital and potential extra provisions remain the biggest operational overhang.
The most relevant development for that thesis is the earnings update for the nine months to 30 September 2026. Net interest income of €4,544 million, compared with €4,454 million a year earlier, and net income of €1,638 million, compared with €926 million, provide investors with additional information about how Raiffeisen Bank International is trading through these issues.
Regarding catalysts, that profit base and record quarterly net interest income of €1.16 billion intersect directly with the planned integration of Garanti BBVA Romania and Addiko. If execution stays tight, scale in Romania, Croatia and Slovenia can support fee income and loan growth, while any deterioration in asset quality or litigation costs would quickly test how durable that earnings bridge really is.
Raiffeisen Bank International's analyst narrative points to revenues of €9.6 billion and earnings of €2.3 billion by 2029. This is based on an assumed 2.6% yearly revenue growth rate and a decline in earnings of €0.1 billion from current earnings of €2.4 billion.
Discover why Raiffeisen Bank International's fair value suggests a valuation gap consistent with its current price.
Exploring Other Perspectives
For Raiffeisen Bank International, the more cautious analysts focus on litigation risk rather than earnings momentum. Before this earnings release, the lowest forecasts were for revenue of about €9.1b and earnings of €2.1b by 2029, well below the consensus of €9.6b and €2.3b. That more pessimistic view could shift as you compare these scenarios yourself.
Explore 4 other Raiffeisen Bank International fair value estimates, including one that suggests as much as 39% downside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Raiffeisen Bank International research is our analysis highlighting 4 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Raiffeisen Bank International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Raiffeisen Bank International's overall financial health at a glance.
Looking for more Raiffeisen Bank International style investment ideas?
If Raiffeisen Bank International's latest earnings have sharpened your focus on quality and risk, use the Simply Wall St Screener to line up a wider watchlist that fits your approach before you commit fresh capital.
- For investors who want potential upside without ignoring balance sheet strength, scan a 127 elite penny stocks with strong financials that already show solid financial underpinnings.
- If resilience matters more than excitement for your next pick, filter the market using a 209 resilient stocks with low risk scores designed to highlight businesses with lower risk scores.
- When you prefer quality businesses that are still flying under the radar, build out your watchlist from a 581 high quality undiscovered gems with strong fundamentals and room for wider investor attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com