


EN
Is Pilgrim's Pride (PPC) Undervalued After Weaker Earnings And Its UK Lamb Exit?
Pilgrim's Pride (PPC) has moved into the spotlight after agreeing to sell a UK lamb slaughterhouse, planning to close another lamb facility, and reporting softer third quarter earnings that showed lower net income and earnings per share.
Recent moves have come after a tough stretch for Pilgrim's Pride shareholders, with the year to date share price return down 28.44% and the 1 year total shareholder return lower by 23.00%, even though the 3 year total shareholder return is up 29.91%. The 7.62% 90 day share price return suggests some momentum has begun to rebuild as investors weigh weaker recent earnings against the decision to exit UK lamb processing and concentrate on the core poultry, pork, and prepared foods operations, at a share price of US$28.53.
Compare Pilgrim's Pride with other protein producers that score well on balance sheet strength in our curated list of solid balance sheet and fundamentals (25 results) to see how it stacks up on fundamentals.
Pilgrim's Pride trades below the average analyst price target while recent earnings and the UK lamb exit have raised fresh questions about risk. Is that gap a bargain or a warning signal?
Most Popular Narrative: 14% Undervalued
Against the last close at $28.53, the most followed valuation story for Pilgrim's Pride points to a fair value of $33.29, using a 7.24% discount rate and long term earnings assumptions to frame that gap.
The main factor that has to go right is that heavy capital expenditures and efficiency projects in the U.S., Mexico and Europe lead to sustainably better margins despite protein supply volatility, legal costs and regional profit pressure.
The current valuation implies that the market is discounting recent margin compression and regional setbacks more heavily than the progress in mix upgrade, geographic expansion and balance sheet capacity, which supports the view that Pilgrim's Pride may be undervalued.
See why 19 investors see Pilgrim's Pride as 14% undervalued.
Result: Fair Value of $33.29 (UNDERVALUED)
Still, Pilgrim's Pride investors need to watch chicken supply staying high in the U.S. and ongoing legal costs, as either could pressure margins and challenge that undervalued thesis.
Find out about the key risks to this Pilgrim's Pride narrative.
Another View On Pilgrim's Pride Valuation
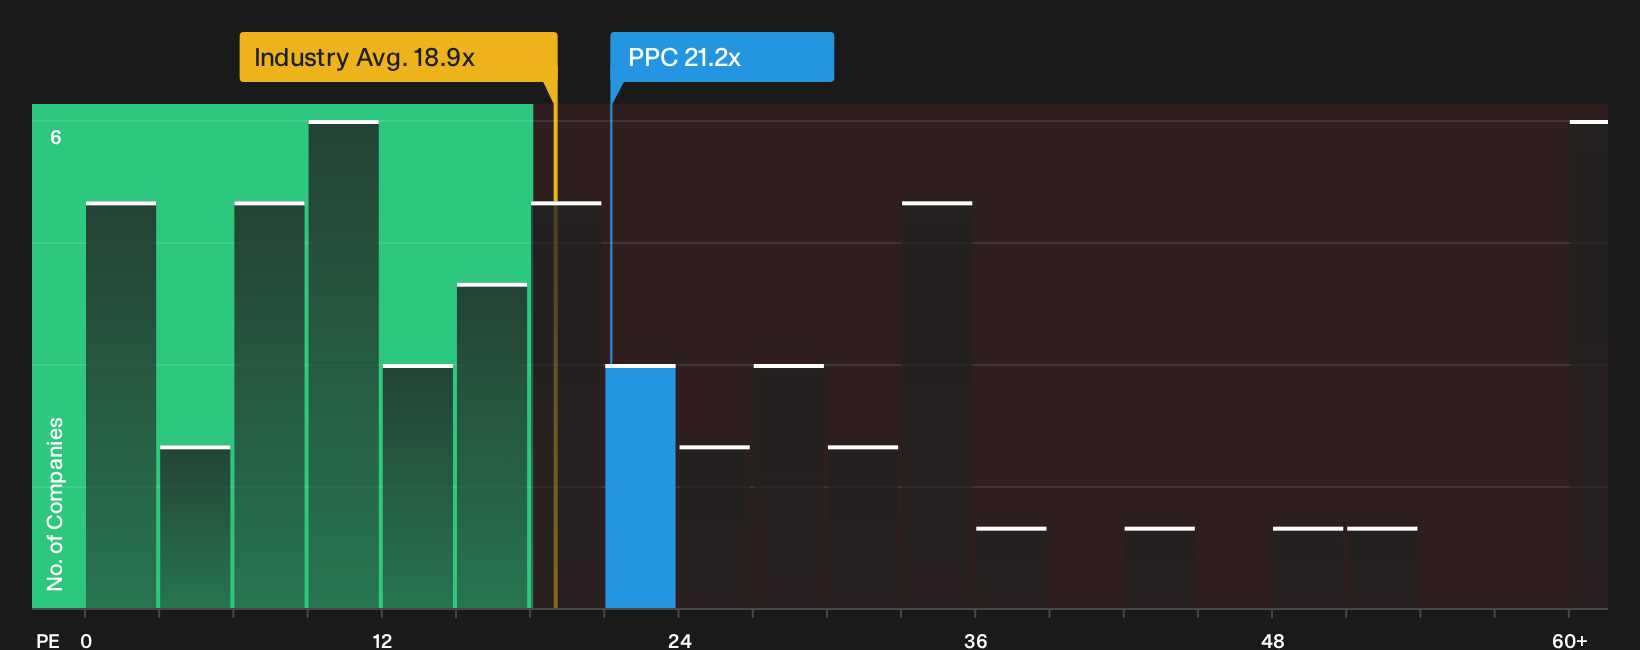
The popular fair value story pegs Pilgrim's Pride at $33.29, yet the current P/E ratio complicates that picture. PPC trades at 21.2x earnings. That is higher than the US Food industry on 18.9x, slightly cheaper than peers at 22.7x, and well below a fair ratio estimate of 37.5x.
This spread suggests the stock carries less of a discount than simple fair value narratives imply, while still leaving some room if the market were to move closer to that higher fair ratio. Which side of that gap do you think investors are really paying for today: the industry premium or the potential fair ratio upside?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Pilgrim's Pride valuation are clear, so treat this as your prompt to review the data, act with appropriate speed, and reach your own judgment using the 1 key reward and 3 important warning signs.
Looking for more Pilgrim's Pride investment ideas?
If Pilgrim's Pride has sharpened your focus, do not stop here. Broaden your watchlist with data driven ideas that could reshape how you think about opportunities.
- Target resilient balance sheets and steady fundamentals by scanning the list of solid balance sheet and fundamentals (25 results) and compare how financial strength varies across sectors.
- Pursue potential value opportunities early by reviewing the 38 high quality undervalued stocks before the crowd starts paying closer attention.
- Strengthen your income stream by checking the 7 dividend fortresses and see which payouts might complement a holding like Pilgrim's Pride.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com