


EN
3 Overlooked US Bank Stocks With Net Interest Margin Leverage
After a strong October jobs report pushed market odds of another Fed rate hike higher, investors are once again being reminded that higher for longer rates can quickly reshape winners and laggards. That kind of backdrop can punish some assets while quietly helping others, especially businesses whose income relies on the gap between what they pay on deposits and earn on loans. This article explores 3 U.S. regional and mid sized bank stocks exposed to this latest data shock, and why their net interest margin leverage now deserves a closer look.
The three banks that follow are just a sample from this theme, and the full screen surfaced 31 more regional and mid sized lenders with equally compelling income and balance sheet stories tied to net interest margin leverage. To go beyond the short list and identify your own high conviction ideas, head straight to the US Regional and Mid-Sized Banks with Net-Interest Margin Leverage screener.
MVB Financial (MVBF)
Overview: MVB Financial is a regional bank that blends traditional lending and deposit taking with fintech driven payments, gaming and banking as a service.
Operations: MVB Financial generates around US$143 million from core banking, US$11 million from its financial holding company and US$9 million from mortgage banking, almost entirely in the United States.
Market Cap: US$337 million
MVB Financial fits this higher for longer theme because its lending and deposit franchise is tightly linked to net interest income. Its fintech engines add fee potential that does not depend solely on rate moves.
"Expansion of payments, banking as a service and digital gaming relationships with large partners such as Fiserv, Worldpay, Intuit Credit Karma, FanDuel, DraftKings and BetMGM positions MVB to capture more transaction volume and fee based revenue as these ecosystems keep growing."
The real swing factor for MVB Financial is how one evolving source of funding reshapes both its margin profile and growth runway.
That funding shift is the real hinge for MVB Financial, and the full narrative for MVB Financial lays out how it could accelerate margins while reshaping risk.

Southern First Bancshares (SFST)
Overview: Southern First Bancshares is a Southeast focused bank holding company providing commercial, consumer, and mortgage lending funded by a broad deposit base.
Operations: Southern First Bancshares generates about US$135 million from core banking activities in the United States, primarily tied to traditional lending and deposits.
Market Cap: US$563 million
Southern First Bancshares is directly exposed to the higher for longer rate environment, with earnings anchored in commercial, consumer, and mortgage loans funded by checking, savings, and time deposits across three Southeastern states. Net interest income was US$34.67 million in Q3 2026 and net income was US$12.23 million. A key consideration is how the remaining pressure on credit quality may affect the net interest margin engine from here.
That margin question comes into focus fast with the 3 key rewards and 2 important warning signs, which examines how Southern First Bancshares could balance income opportunity against emerging credit pressure.
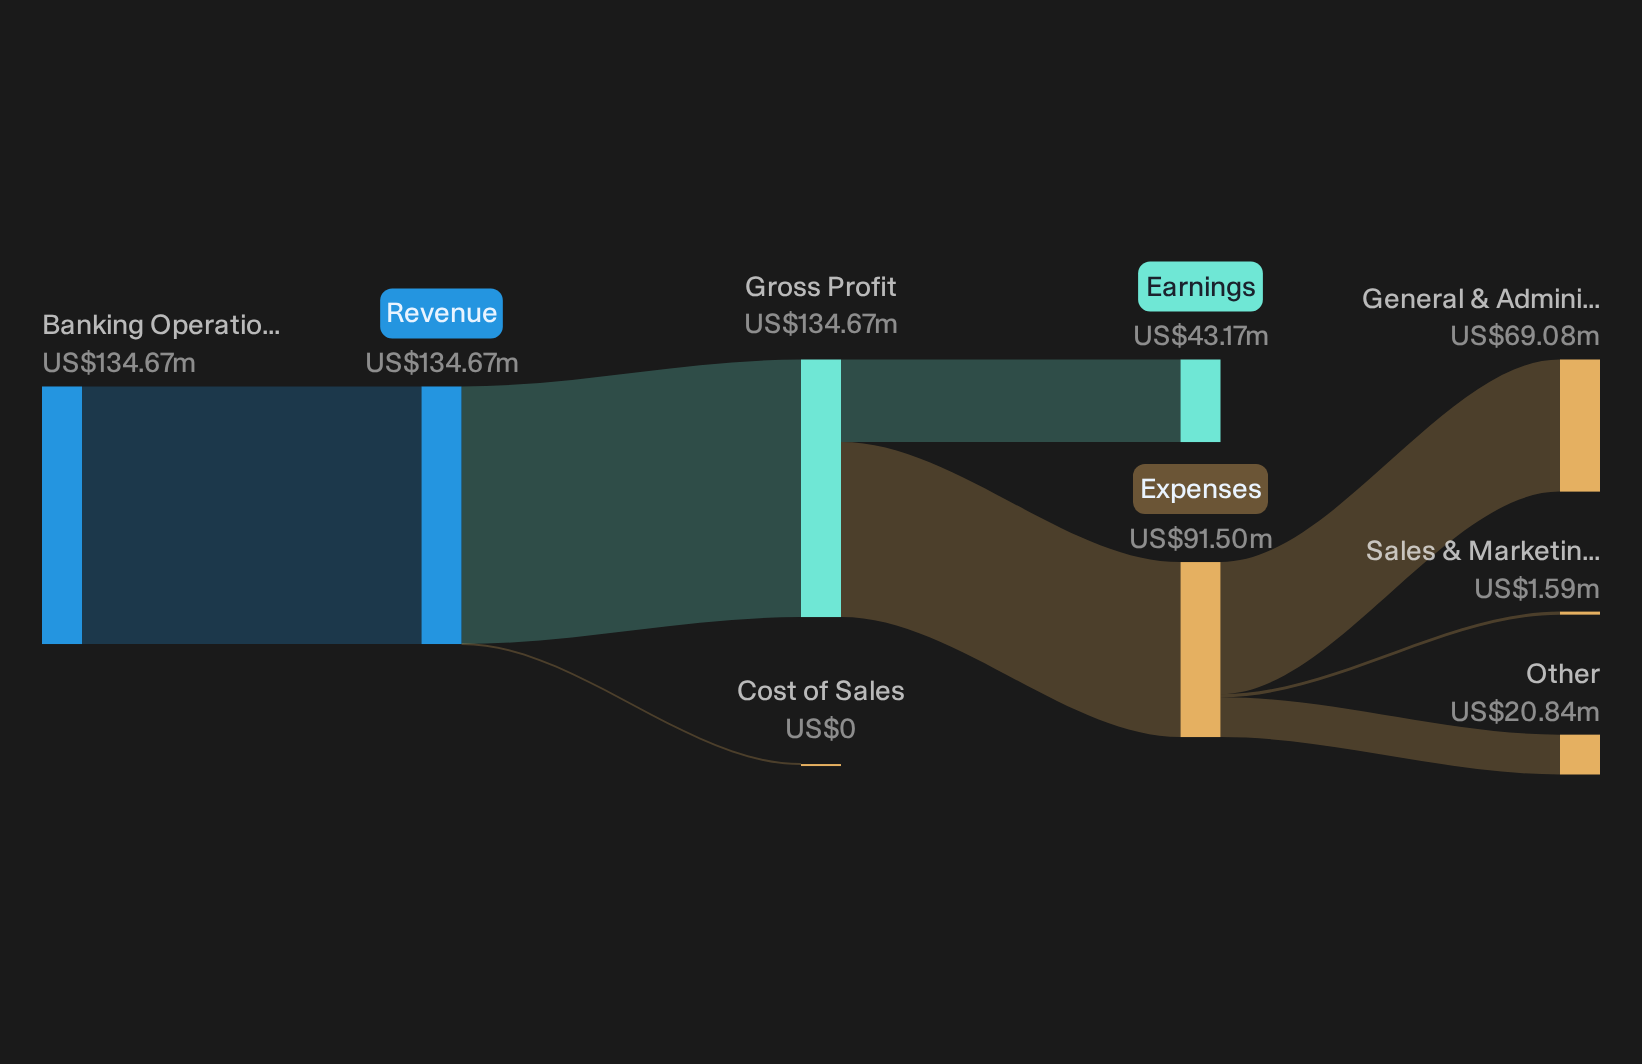
Northrim BanCorp (NRIM)
Overview: Northrim BanCorp is an Anchorage based commercial bank focused on traditional lending and deposit services for businesses and professionals.
Operations: Northrim BanCorp generates about US$146 million from community banking, US$44 million from home mortgage lending and US$17 million from specialty finance, all in the United States.
Market Cap: US$523 million
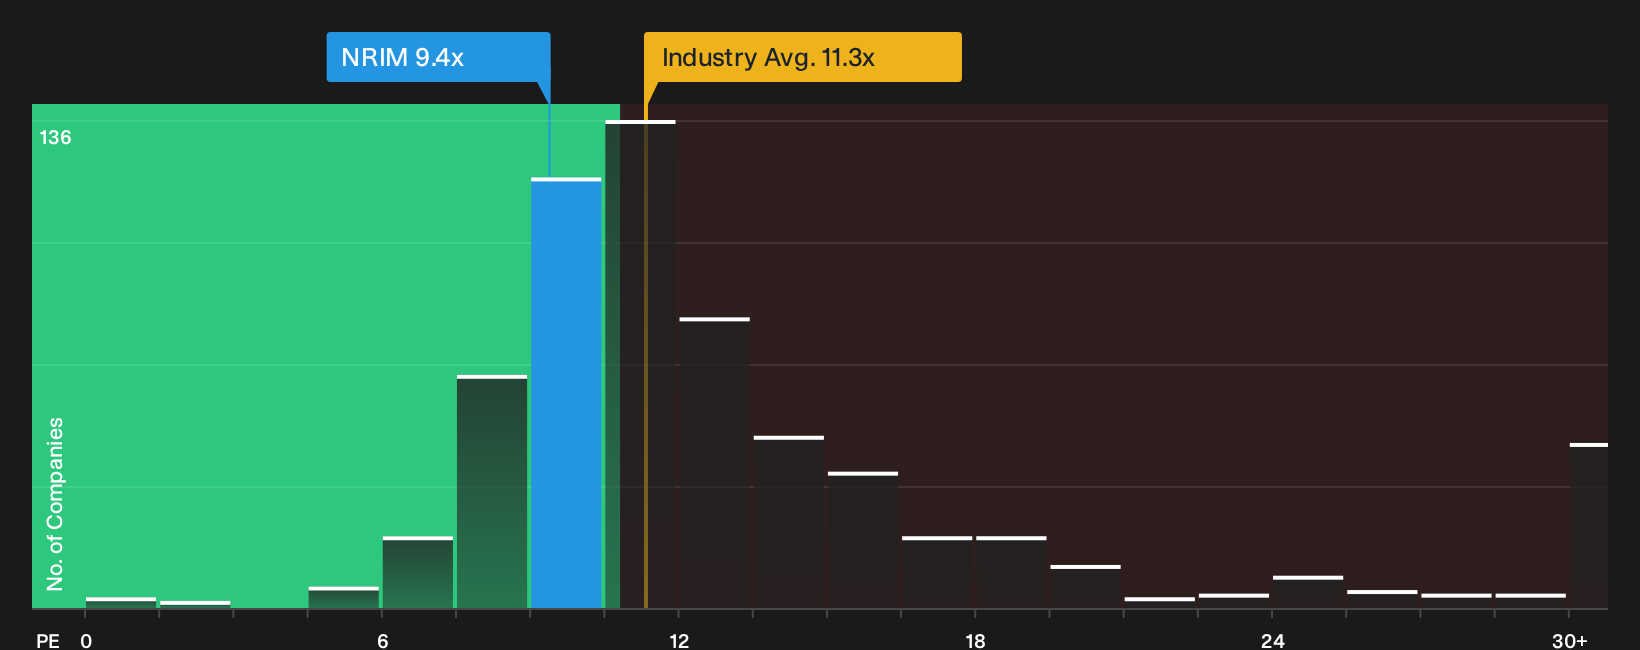
Northrim BanCorp sits squarely in this net interest margin focused screen, with US$110.68 million in net interest income for the first nine months of 2026 and a P/E around 9.4x paired with a dividend yield near 2.89%. For a lender built on deposits and business loans, what happens when one subtle pressure on profitability either eases or lingers will matter a lot for investors.
If that profitability pressure matters to you, the 5 key rewards and 2 important warning signs reveals where Northrim BanCorp’s income engine could either accelerate or stall next.
Seeking Alternatives Before The Crowd?
Fresh ideas move first. By the time momentum is flying and breakouts are on every chart, the ideal entry can be gone. Scan these under the radar lists while it matters and look for opportunities earlier in the process.
- Target dependable cash generators that keep distribution front and center by reviewing the 7 dividend fortresses curated for income focused portfolios that cannot wait for yields to catch up.
- Spot early leaders in automation and factory intelligence by scanning the 90 robotics and automation stocks before industrial robotics demand is fully reflected in pricing and potential mispricing drops out of view.
- Track the backbone of AI capacity growth by checking the 53 AI infrastructure stocks while key enablers of data center expansion are still flying under broader market radars.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com