


EN
How $5 Billion Buyback At Thermo Fisher Scientific (TMO) Has Changed Its Investment Story
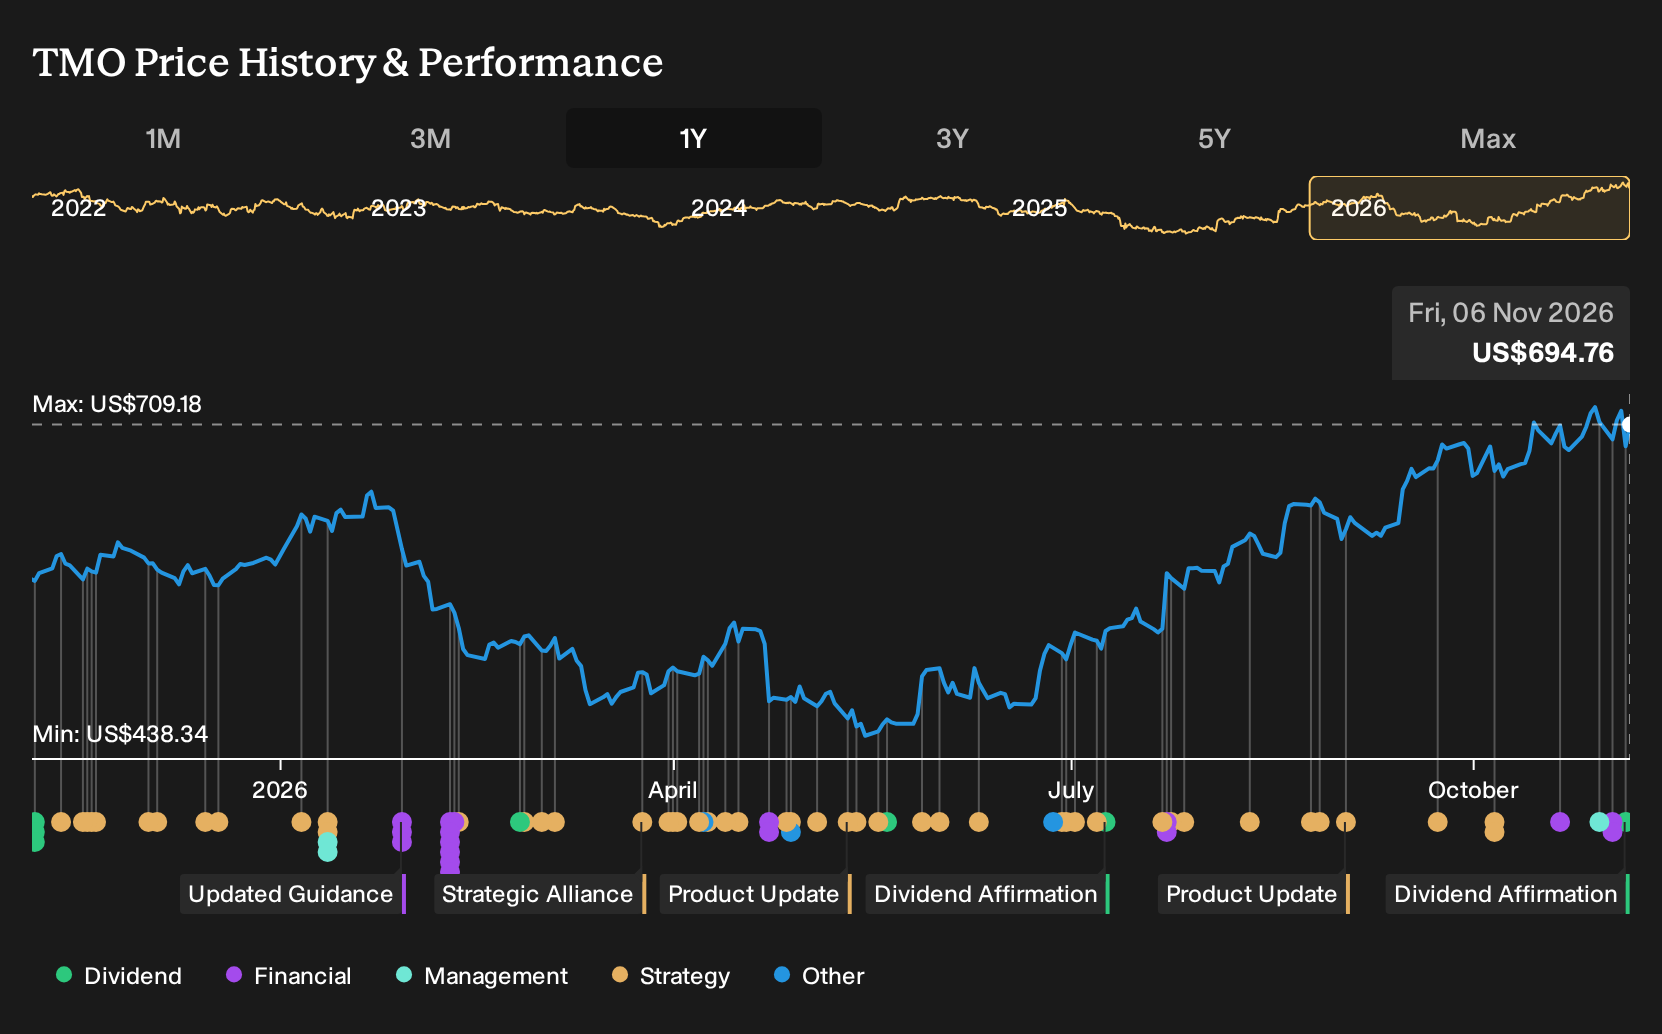
- Thermo Fisher Scientific approved a new US$5 billion share repurchase program, refreshed its dividend at US$0.47 per share, and issued CHF 280 million of long dated Swiss franc bonds, while also confirming the planned retirement of Executive Vice President Michael D. Shafer at the end of 2026.
- The enlarged buyback authorization, alongside continued dividends and fresh eurobond financing, indicates that Thermo Fisher Scientific is actively managing its capital structure and ownership mix while funding its broad life sciences tools and services operations.
- The focus now turns to how Thermo Fisher Scientific's new US$5 billion repurchase authorization could influence its existing capital return led investment profile.
Compare Thermo Fisher Scientific's capital return playbook with other companies actively rewarding shareholders by scanning our curated list of 7 dividend fortresses positioned for income-focused portfolios.
Thermo Fisher Scientific Investment Narrative Recap
For Thermo Fisher Scientific, the big picture you need to buy into is that pharma and biotech demand, bioproduction and higher value instruments keep pulling more weight than slower academic and government spending. The key near term swing factor is how quickly muted funding pockets improve versus expectations, because that shapes organic revenue momentum and operating leverage.
The largest operational risk still sits with that softer academic and government channel and the earnings dilution from the microbiology divestiture if follow on deployment underwhelms. The latest dividend and buyback news does not materially change those business level drivers. It mainly speaks to capital allocation, not day to day execution.
The fresh quarterly dividend affirmation at US$0.47 per share is the cleanest signal in this batch of updates. It indicates that management is currently balancing ongoing cash returns with the demands of a capital intensive tools and services platform that is leaning into bioproduction, data rich instruments and outsourced pharma services.
For catalysts, the dividend is a small piece next to factors such as M&A integration, microbiology divestiture execution and capacity additions tied to pharma reshoring and electron microscopy orders for semiconductor fabs. The payout simply sits alongside the enlarged buyback as another recurring feature investors can factor into Thermo Fisher Scientific’s capital return profile while they watch those operating milestones.
Thermo Fisher Scientific's narrative projects US$56.1b revenue and US$10.7b earnings by 2029. This assumes 5.8% yearly revenue growth and an earnings increase of about US$3.6b from US$7.1b today.
Uncover why Thermo Fisher Scientific's fair value indicates an 8% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the lowest Thermo Fisher Scientific forecasts lean hard on microbiology divestiture risk. Those analysts saw 2029 earnings closer to US$9.5b on about 5.3% annual revenue growth, versus the consensus US$10.7b path. The refreshed dividend and new Swiss bonds could shift that debate, so treat these pre news assumptions as starting points and compare several viewpoints.
Explore 4 other Thermo Fisher Scientific fair value estimates, including one that suggests there may be as much as 15% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider conducting your own research and forming your own view.
- A great starting point for your Thermo Fisher Scientific research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Thermo Fisher Scientific. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Thermo Fisher Scientific's overall financial health at a glance.
Looking For More Investment Ideas Beyond Thermo Fisher Scientific?
Once you have a handle on Thermo Fisher Scientific, it can help to widen the lens and compare its profile with other businesses that fit different portfolio roles. The Simply Wall St Screener offers several focused starting points so you can align ideas with your own risk tolerance, income needs, and return goals.
- If capital preservation and smoother rides matter most to you, start with resilient businesses by checking out 31 resilient stocks with low risk scores that may better match a lower volatility approach.
- If you want balance sheet strength front and centre, focus on financially robust companies through a list of solid balance sheet and fundamentals (25 results) that can handle tougher conditions.
- If you prefer chasing under followed opportunities, look at quality businesses that fly under the radar by scanning 19 high quality undiscovered gems that might not be widely owned yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com