


EN
Diamondback Energy (FANG) Just Gave Investors Something To Think About
Diamondback Energy (FANG) is back in focus after releasing third quarter 2026 results, updating its production outlook and approving a higher base dividend, a trio of updates that matters for income oriented investors.
Recent price action has been choppy for Diamondback Energy, with the share price falling 15.6% over the last week and 10.1% over the past three months. Even so, the year-to-date share price return is up 17.5% and the 1-year total shareholder return sits at 27.6%, suggesting longer term holders have still seen momentum hold up despite the latest pullback.
Scan income ideas around Diamondback Energy's latest dividend move and production update by checking a curated list of resilient cash generators in the 7 dividend fortresses.After a sharp pullback and a higher base dividend, Diamondback Energy now sits in a very different spot for income hunters. Does it make more sense to lean in at this point, or to wait for a cheaper entry and stronger yield?
Most Popular Narrative: 25% Undervalued
On the most followed narrative, Diamondback Energy screens as undervalued, with a fair value estimate of $239.45 against the recent $178.96 close. This sets up a story centered on cash generation rather than volume growth.
Ongoing consolidation in the Permian Basin, with Diamondback Energy positioned as a consolidator that has already integrated large acquisitions and realized lower lease operating expense through automation and pump by exception, supports further scale driven synergies that can help sustain EBITDA margins and free cash flow.
See why 80 investors see Diamondback Energy as 25% undervalued.
Result: Fair Value of $239.45 (UNDERVALUED)
Still, this underpriced story can change quickly if large insider share sales continue or if higher Permian power and water costs erode the margins of Diamondback Energy.
Find out about the key risks to this Diamondback Energy narrative.
Another View: Diamondback Energy on Earnings Multiples
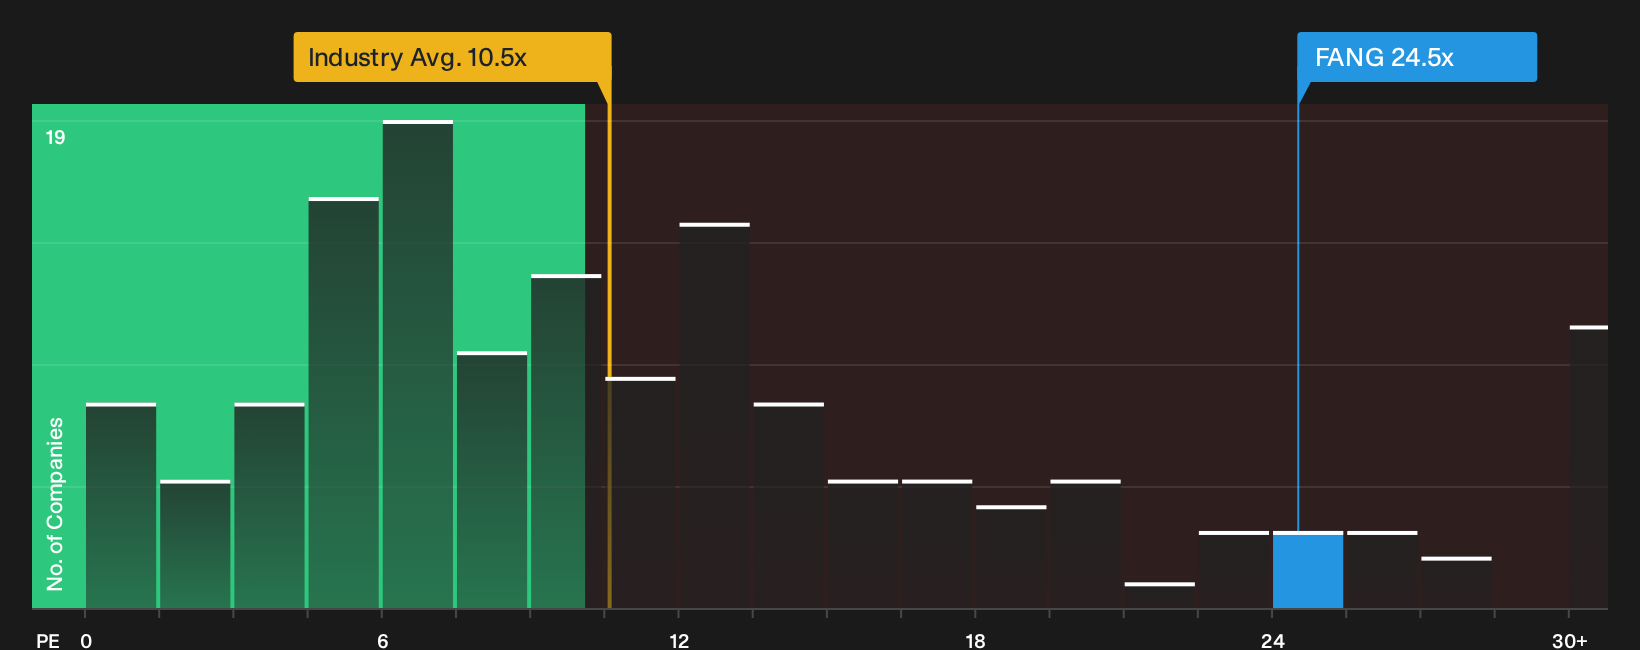
The discounted cash flow work presents Diamondback Energy as undervalued. However, the simple earnings multiple tells a different story. FANG trades on a P/E of 24.5x, compared with 11.4x for peers, 10.5x for the wider US Oil and Gas group, and a fair ratio of 21.5x. That richer tag can mean investors are paying up for quality or accepting higher valuation risk. Which story do you think fits better?
To see how this earnings based view fits into the rest of the numbers, including where pricing might normalise toward the fair ratio, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment on Diamondback Energy is split, with investors flagging both real concerns and genuine bright spots, so move quickly and weigh the trade off for yourself. To see both sides in one place, review the 3 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Diamondback Energy?
If you stop with Diamondback Energy, you risk missing other clear opportunities. Use the Simply Wall Street Screener to broaden your watchlist with focus and intent.
- Spot potential mispricings early and review the 38 high quality undervalued stocks that combine stronger fundamentals with what may be appealing entry prices.
- Prioritise resilience and scan a list of solid balance sheet and fundamentals (25 results) so you can focus on businesses that look better equipped to handle tougher conditions.
- Get ahead of the crowd and track a 19 high quality undiscovered gems before they attract wider attention and heavier trading interest.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com