


EN
What Coca-Cola HBC Holders Bought Into
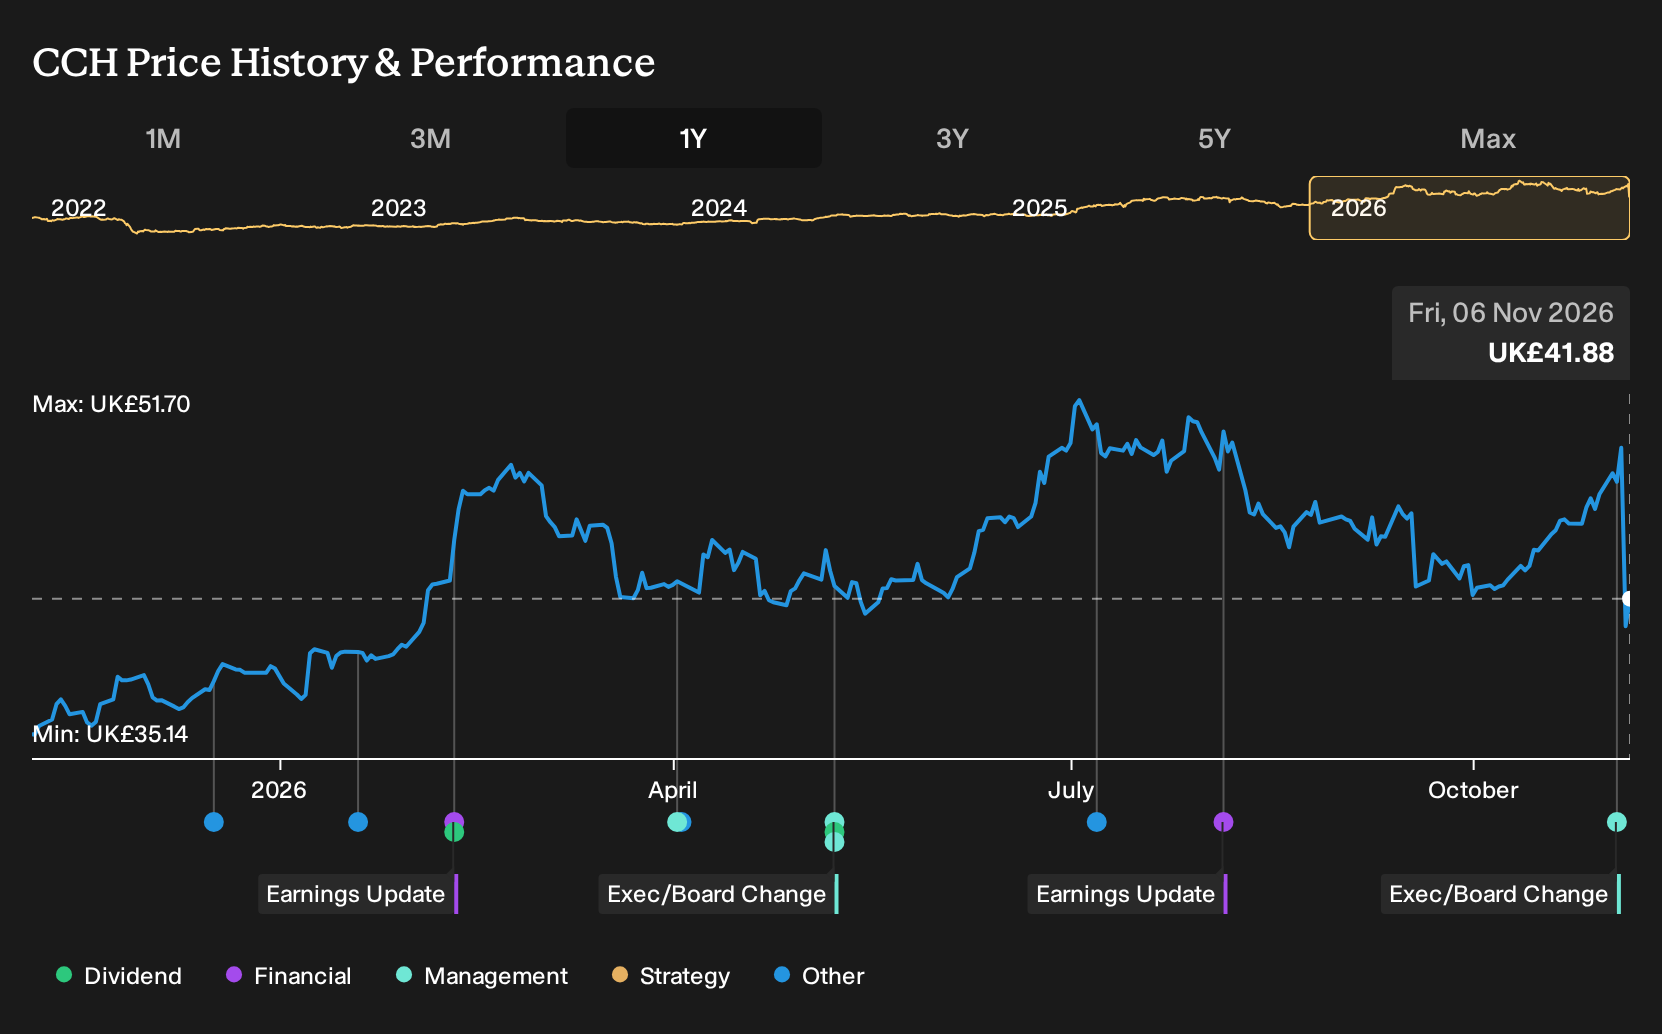
If Coca-Cola HBC was sitting on your watchlist instead of in your portfolio, the outcome over the past year may feel painful to review. Investors who held Coca-Cola HBC over the past year are up 20.6%, including dividends. That result lands after analysts had split views in late 2025 on whether emerging market demand, especially in Nigeria and Egypt, could really offset rising regulation and aging European consumers. Which side of that consumption story looked more credible at the starting line?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
Coca-Cola HBC has already moved. See which of 14 high quality undervalued stocks still trade below our estimates.
The Two Coca-Cola HBC Stories Investors Had To Weigh
The shares cost £35.14 at the start of the period, and Coca-Cola HBC sat between two sharply different stories about its future.
The bullish Narrative put Fair Value at £41.26, or 17% above the start price. It leaned on assumptions of 6.6% annual revenue growth and a profit margin of 8.6%, supported by Nigeria and Egypt demand, as well as digital and AI projects.
The bearish view pointed to a Fair Value of £26.42, or 25% below the start price. It focused on tighter sugar regulation and aging European populations as long-term threats to soft drink volumes and profitability.
What The 2026 Evidence Did To The Coca-Cola HBC Debate
The clearest fresh data point was Coca-Cola HBC’s H1 2026 report, with revenue of €6.23b and net income of €524.4m compared with €5.62b and €470.6m a year earlier. That supported the optimistic case that assumed higher sales and profit. Russian asset uncertainty, with a local brewer seeking control of its subsidiaries, pulled the other way. Overall, the evidence cut both ways.
The decision in 2025 hinged on whether emerging market demand and new categories could carry revenue and earnings. When you look at another consumer stock, check whether reported sales, profit and guidance line up with whatever growth story you are being asked to believe.
What Coca-Cola HBC’s Price Seems To Assume Now
Coca-Cola HBC now trades at £41.88, after a 20.6% gain over the past year. The selected bullish Narrative places Fair Value above that level, based on how much earnings power it sees in Africa, energy drinks and the broader 24/7 beverage line up.
The argument leans on execution. A buyer today would need to judge whether current pricing still understates the durability of African volume growth, single serve mix gains and digital tools that aim to turn those into lasting profit.
"The numbers and recent analyst targets indicate that Coca-Cola HBC’s share price still reflects caution on input cost pressure, finance costs and regulatory risks, even as some investors and banks see room for upside. As a result, the stock appears to be pricing in less than a full credit for its Africa growth and digital initiatives."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
How Could You Get There Earlier?
What if your next investment idea came before the headlines? Go straight to the companies whose prices and our estimates still disagree. Three places to start, with the names waiting behind the link.
- Company 1 - 33% below our estimate - targets fundraising into tax-efficient retail products and regional private equity mandates.
- Company 2 - 29% below our estimate - builds a single-tech investment platform that serves both advisers and direct customers at scale.
- Company 3 - 15% below our estimate - recruits senior lawyers onto a dispersed platform that shares fees instead of traditional firm overhead.
Those are three of them. See every one of the 9 solid balance sheet companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com