


EN
3 Power Stocks Retail Investors Are Watching For AI Data Center Demand
AI data centers are hungry for power, and the rush to secure clean, always on electricity is turning once niche ideas like Fervo Energy’s enhanced geothermal projects into front page stories for investors. That shift creates a window where business models tied to firm low carbon power could move from concept to real contracts. This article walks through three stocks exposed to that story and explains why the recent news around Fervo might matter to your portfolio.
The three stocks that follow are a sample, not the full picture, and the broader screen surfaced 12 more companies tied to clean baseload power and long term contracts that could be just as interesting for AI and data center demand. To see the wider field and identify which ideas best fit your own risk and return goals, head into the Clean baseload power for AI and data centers screener.
Aboitiz Equity Ventures (PSE:AEV)
Aboitiz Equity Ventures ties clean baseload generation and data services under one roof, which makes it a useful bellwether for how Philippine and Asian grids might supply always on power to AI heavy data centers over the next few years.
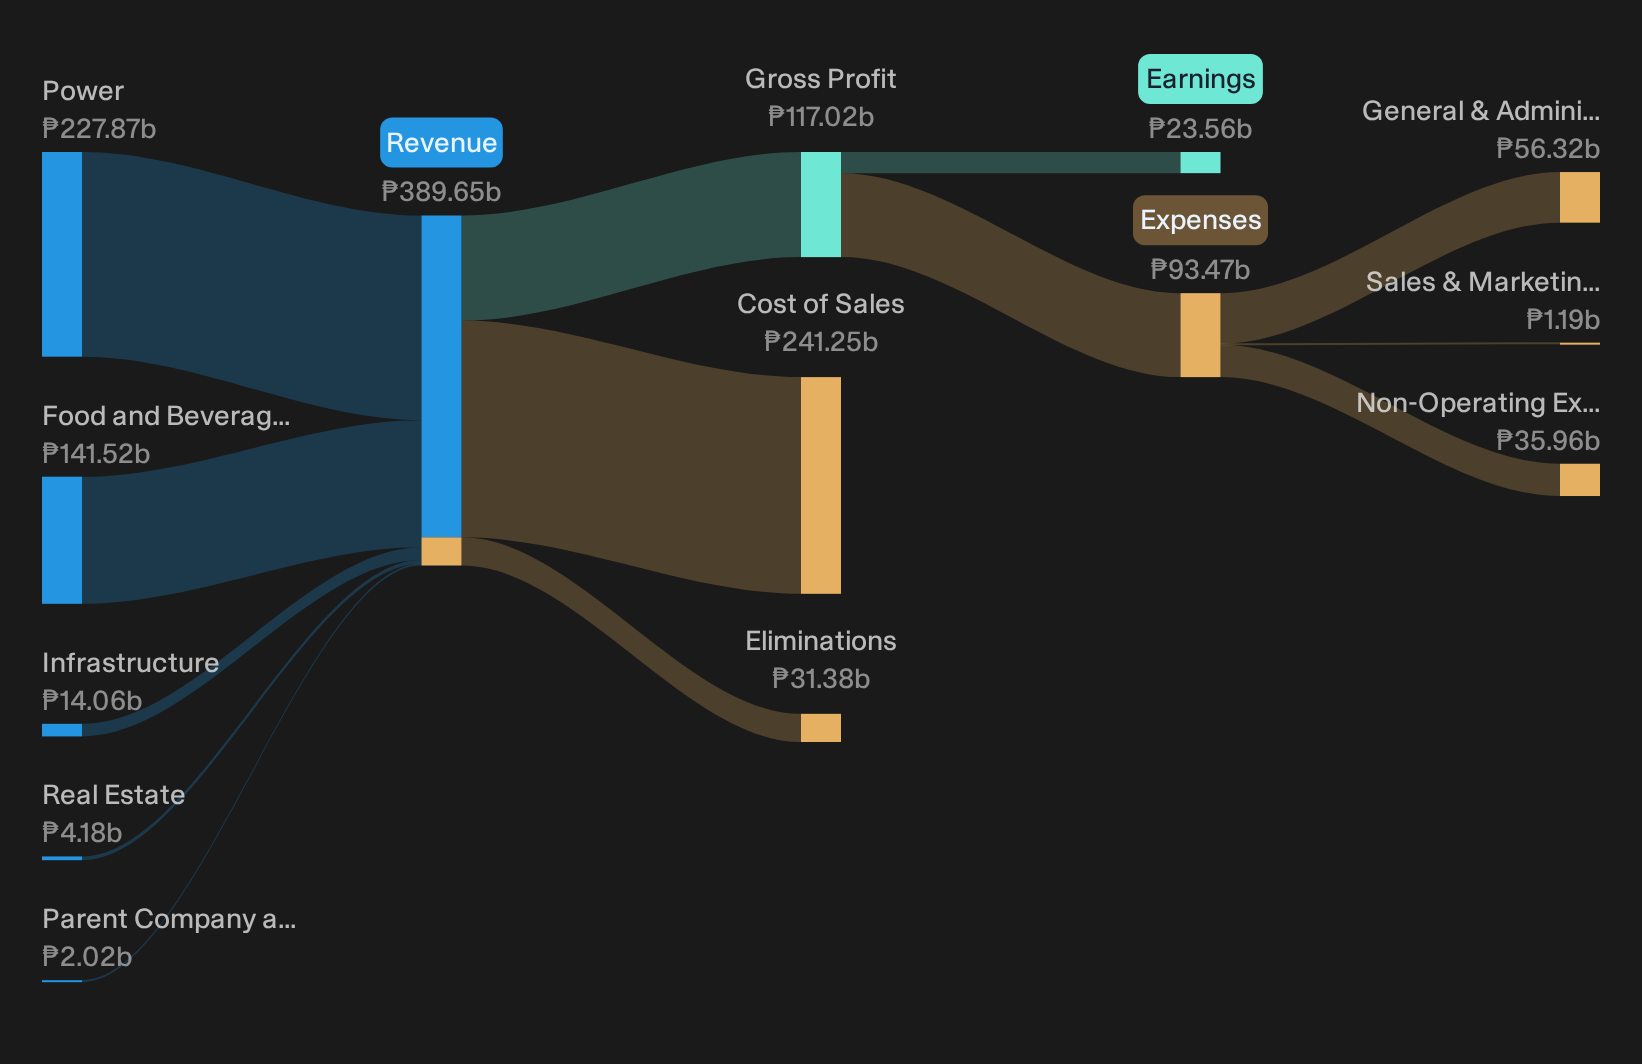
Aboitiz Equity Ventures runs power, banking, food, infrastructure, land and data science or AI operations, with around ₱227.9b from Power and ₱141.5b from Food and Beverage out of roughly ₱399.7b segment revenue, plus smaller Infrastructure and Real Estate units, and a market cap near ₱211b.
"The earlier idea that AboitizLand was focusing on high value residential projects now connects with Residential returning to profitability in 1H26 with net income of PHP 102m and EBITDA of PHP 203m, while stricter buyer qualification and ready for occupancy inventory position the residential and estate platform for more stable revenue and margin contribution. The earlier concern that revenue decline in Aboitiz Foods could weigh on total revenue growth now has a different shape, since the group is reporting 1H26 revenue of ₱51.6b and EBITDA of ₱4.7b for Aboitiz Foods; prolonged weakness in these downstream units could offset the contribution from regional agribusiness and limit future group revenue and earnings growth."
What happens to future margins and reinvestment capacity if one quiet pressure inside this diversified mix tightens faster than management expects?
That pressure point is exactly where the story gets interesting, and the full narrative for Aboitiz Equity Ventures shows how Aboitiz Equity Ventures could turn tightening cash into accelerating opportunity.
Acen (PSE:ACEN)
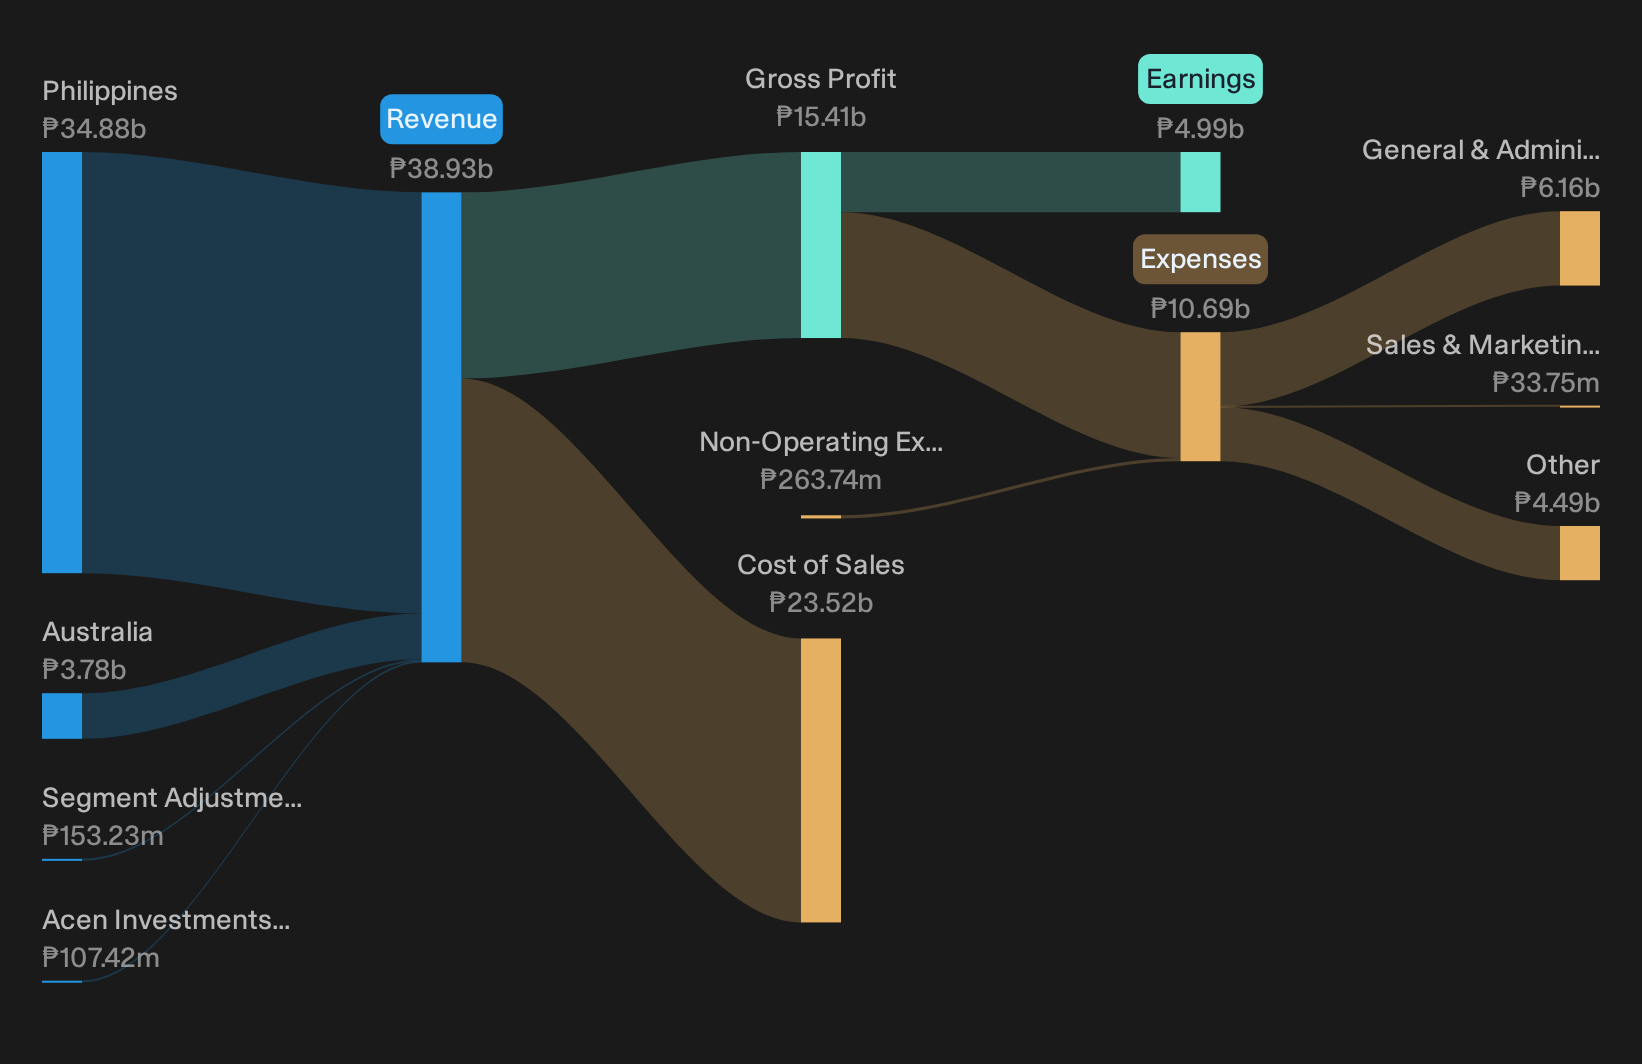
Acen is a pure-play power producer focused on renewables that fits the clean baseload and long term PPA theme. Most of its ₱39.9b revenue comes from the Philippines at about ₱34.9b, with Australia contributing roughly ₱3.8b, and a market value near ₱105.5b.
Acen lines up closely with the screener idea because it already runs utility scale solar, wind, geothermal and battery projects that can underpin firm clean power for energy hungry data centers. Earnings momentum, recent term loans for renewables and growing retail supply deals are part of that story, but the outcome still hinges on how one funding pressure shapes future project economics.
That funding hinge is exactly where your view on Acen can sharpen. The analysis report for Acen shows how project economics could accelerate or stall under different capital cost paths.
ACME Solar Holdings (NSEI:ACMESOLAR)
ACME Solar Holdings provides exposure to India’s push for low carbon power that can be structured into long term PPAs for energy hungry data centers, with a business built around large scale solar, wind and battery projects plus grid facing services.
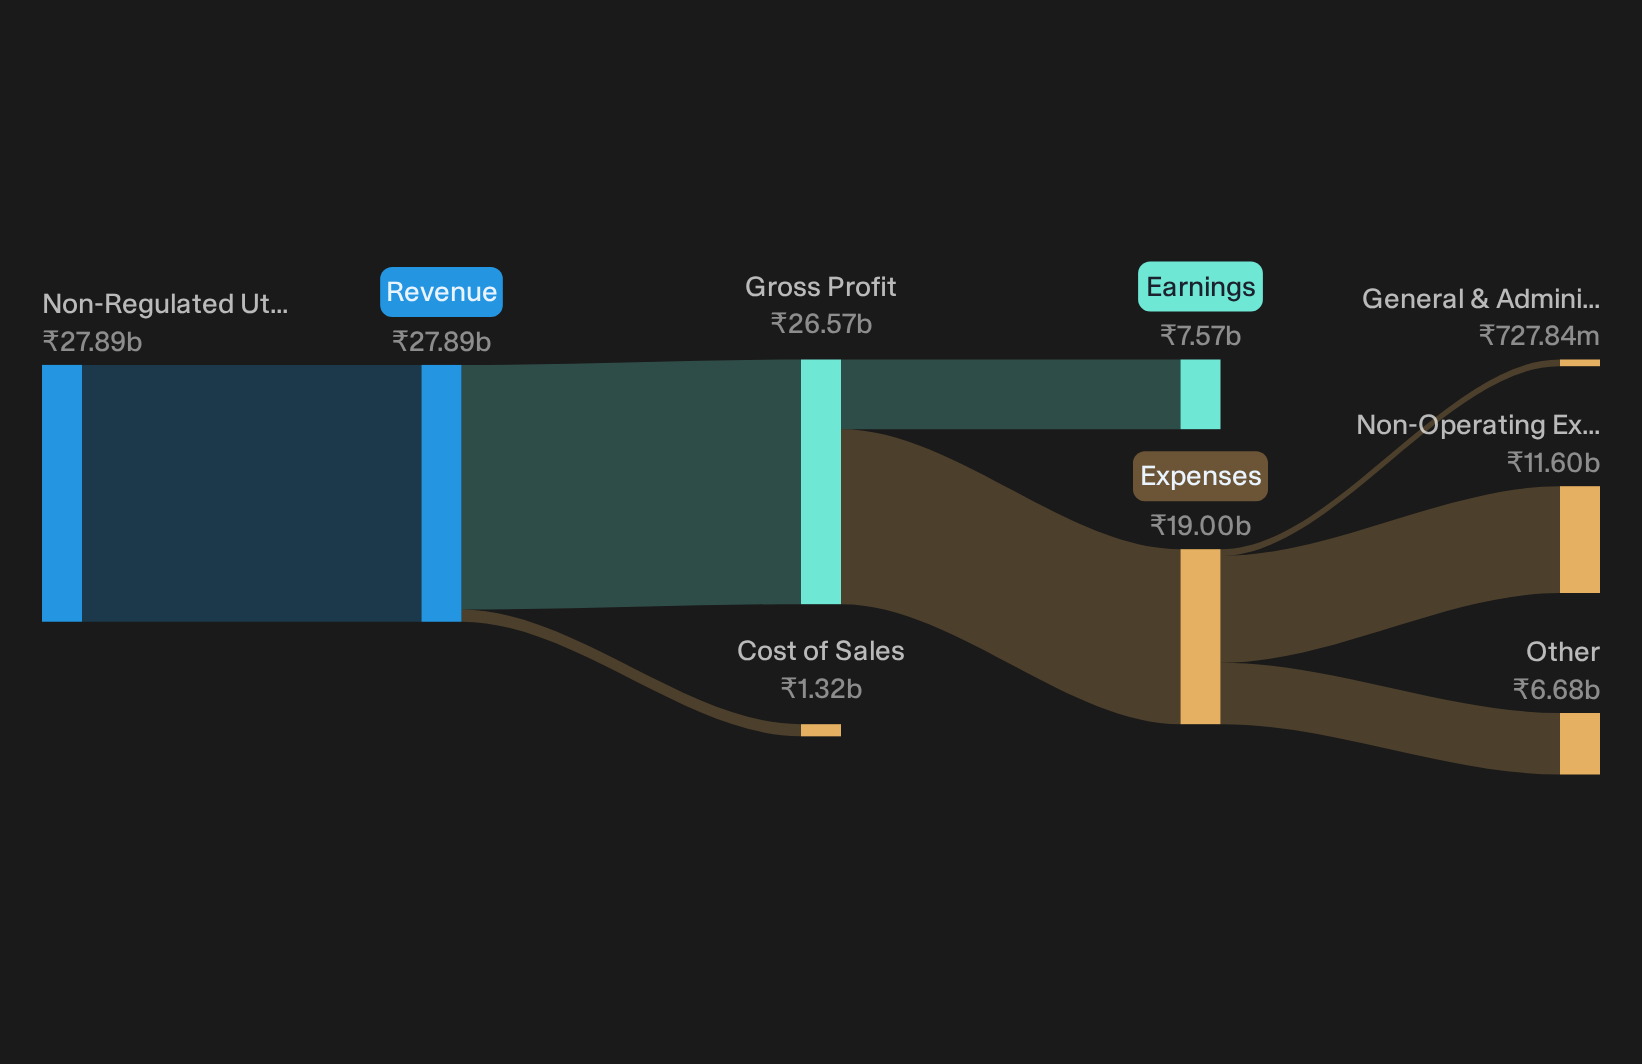
ACME Solar Holdings develops and operates grid connected solar and wind projects in India, earning about ₹27.9b from its non regulated utility arm in India, and carries a market value close to ₹279.2b.
Interest in ACME Solar has picked up as investors look beyond geothermal headlines and start asking which renewables platforms already pair large battery projects with PPA backed output that could be shaped to match data center style demand curves.
"Rapid build out of grid scale battery energy storage, with 13.5 gigawatt hour in the portfolio and 5.1 gigawatt hour already ordered, positions ACME to monetize peak power price spreads from Q4 FY 26 onward, which could lift EBITDA and earnings quality."
What ultimately matters is how one quiet shift in funding and contract mix changes the balance between rich growth expectations and future cash generation.
That shift in balance is where your edge can start, and the full narrative for ACME Solar Holdings shows how funding, contracts and storage could reshape ACME Solar Holdings from here.
Seeking Alternatives Beyond Your Current Watchlist?
Fresh ideas move first. Breakout trends, early momentum and under the radar stories rarely stay quiet for long, and the best entries go to those who act now.
- Spot potential turnarounds before momentum is obvious by scanning 581 high quality undiscovered gems that focus on strong fundamentals while they are still largely under the radar for now.
- Lock in potential cash flow strength with 228 dividend fortresses that focus on higher yielding, resilient payers before yield compression and price moves narrow your options.
- Ride structural tech demand by checking 53 AI infrastructure stocks packed with businesses tied to the build out supporting AI capacity while market attention is still catching up.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com