


EN
Does Revenue Guidance Beat Change The Bull Case For Skyworks Solutions (SWKS)?
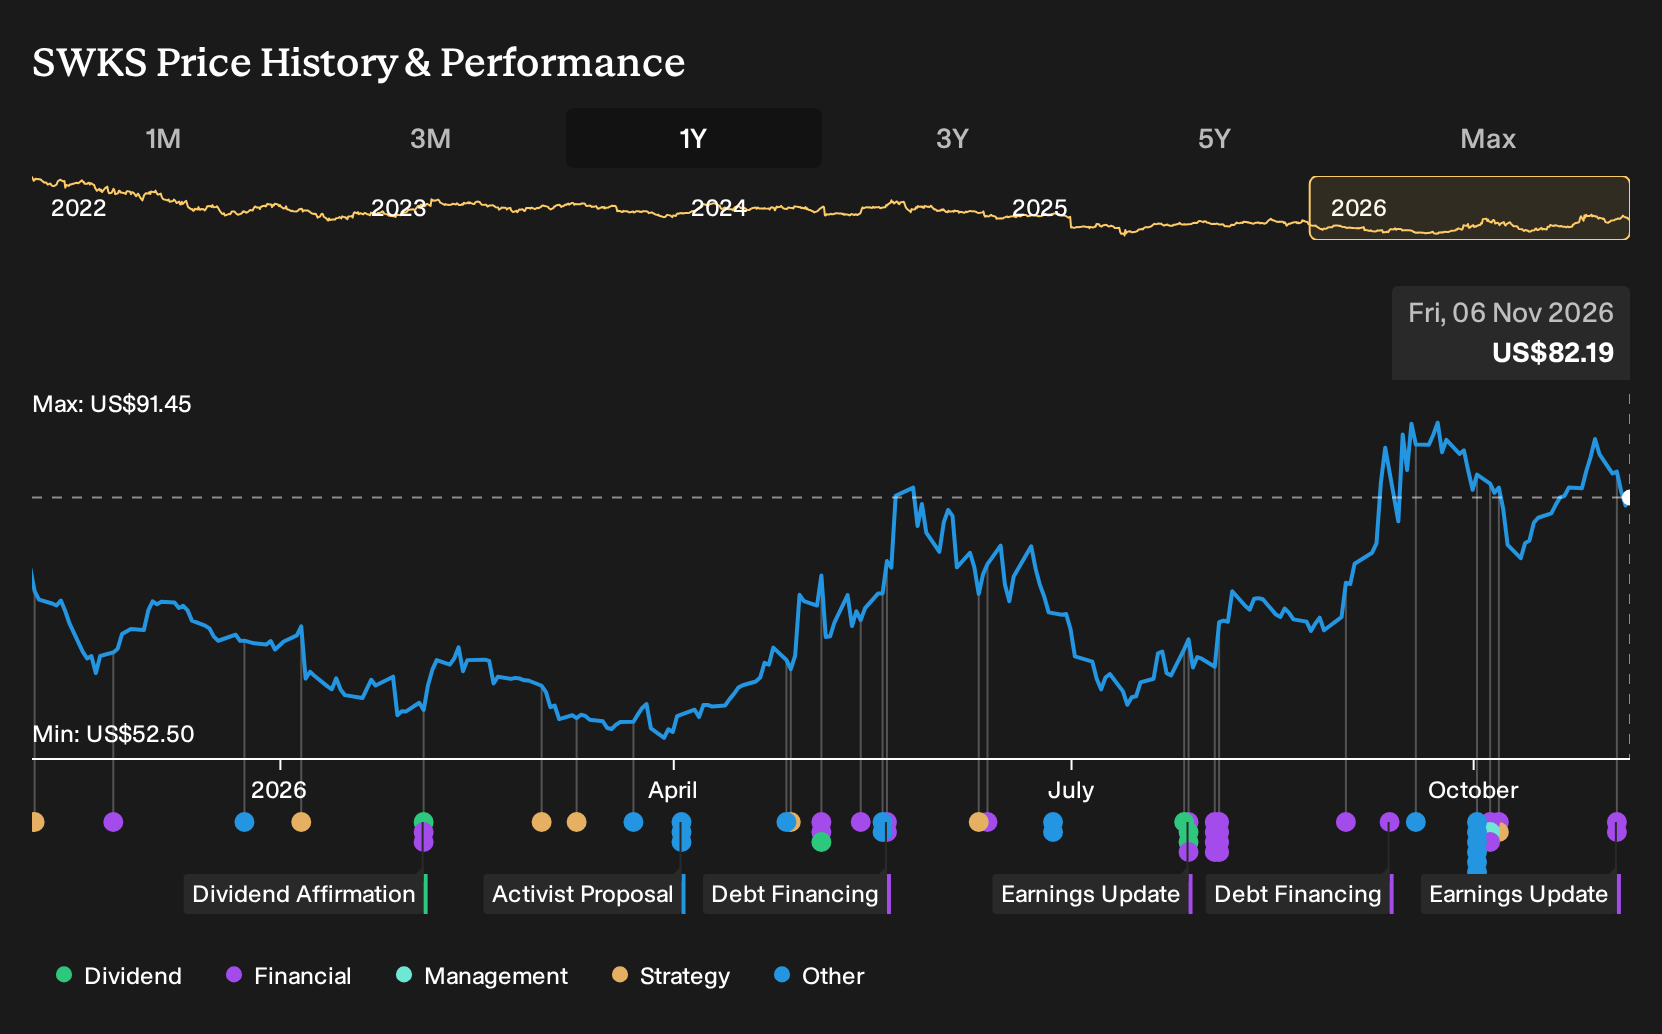
- Skyworks Solutions reported fourth quarter 2026 sales of US$1,045.7 million and net income of US$23.4 million, with full year revenue of US$3,959.6 million and earnings per share from continuing operations of US$1.14 on a diluted basis, all for periods that ended before today.
- The company paired these weaker earnings with revenue guidance of US$1.80 billion to US$1.90 billion for the first fiscal quarter of 2027. Together with higher analyst estimates, this draws attention to whether underlying demand and cost control can support a near term recovery in profitability.
- We will examine how Skyworks Solutions' investment narrative around RF content expansion and diversification is tested by soft earnings but stronger revenue guidance.
Skyworks Solutions Investment Narrative Recap
For a shareholder in Skyworks Solutions, the core belief is that RF content in premium phones and high performance connectivity keeps getting more complex and valuable. The recent quarter, with US$23.4 million in net income on US$1,045.7 million of sales, challenges confidence in near term execution. The immediate catalyst is whether RF programs tied to leading mobile and Android design wins can translate into cleaner, higher margin earnings.
The biggest operational risk right now sits in concentrated mobile exposure and compressed profitability. Full year net income of US$172.1 million on US$3,959.6 million of sales leaves limited room for error if a key customer trims units or mix. The guidance lift around upcoming revenue puts more focus on cost discipline and how quickly the profit margin can stabilise from here.
The most relevant disclosure is Skyworks Solutions guiding first fiscal quarter 2027 revenue to a range of US$1.80b to US$1.90b. That range, coming right after weaker quarterly and annual earnings, frames the next few months as a test of demand for RF content across mobile and broad markets. It also becomes the reference point investors watch against orders and utilisation.
If that revenue range is achieved, the spotlight shifts to quality of profit rather than just top line scale. Investors will likely track whether gross and net margins start to rebuild from the compressed 2026 levels, and how much of the mix comes from areas like Wi Fi, automotive and AI data center. Execution against that backdrop is what will drive the next phase of the Skyworks Solutions story.
Analysts outline a scenario in which Skyworks Solutions reaches US$8.0b in revenue and US$1.3b in earnings by 2029. This implies forecast revenue growth of 25.6% per year and an earnings increase of about US$1.0b from US$290.1m today.
Uncover why Skyworks Solutions' fair value indicates a 4% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
One alternate view around Skyworks Solutions focuses less on RF content upside and more on margin strain. The most bearish analysts were already working with profit margins at 4.3% and a higher implied P/E of 72.5% of the industry level, even while pencilling in US$8.0b of revenue and US$1.3b of earnings by 2029. That creates a much harsher story on cost pressure and execution risk than the consensus, and the new earnings news could push those expectations in either direction once models are updated.
Explore 3 other Skyworks Solutions fair value estimates, including one that suggests it could be worth just $78.44.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Skyworks Solutions research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Skyworks Solutions. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Skyworks Solutions' overall financial health at a glance.
Looking For More Investment Ideas Beyond Skyworks Solutions?
If Skyworks Solutions has sharpened your appetite for targeted opportunities, it can help to widen the lens and scan other companies with fundamentals that fit your risk and income preferences. The Simply Wall St Screener gives you a way to filter for balance sheet strength, value, or income characteristics in a structured way, rather than jumping from ticker to ticker.
- If you want potential upside without stretching on quality, you can filter for resilient businesses trading below their estimated worth using the 38 high quality undervalued stocks.
- For investors who care most about capital preservation and steadier profiles, you can focus on companies that clear strict risk checks through the 31 resilient stocks with low risk scores.
- If income matters to your plan, you can zero in on higher yielding payers that still pass core financial health tests with the 7 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com