


EN
Are Stronger Earnings Altering The Investment Case For Yum! Brands (YUM)?
- Yum! Brands reported third quarter 2026 revenue of US$2,054 million and net income of US$1,623 million, with basic EPS from continuing operations of US$5.96, alongside higher nine month sales and earnings compared with the prior year period.
- The scale of Yum! Brands' year to date net income of US$2,908 million and diluted EPS of US$10.51 highlights how recent operating performance is reshaping the earnings base that underpins its long term investment case.
- We will now examine how the sharp jump in net income at Yum! Brands reshapes the investment narrative that investors had been using until now.
Yum! Brands Investment Narrative Recap
To own Yum! Brands, you need to believe its franchise heavy model, expanding digital channels and KFC led development can support resilient earnings even when individual concepts face pressure. The Q3 2026 numbers, with US$2,054 million of revenue and US$1,623 million of net income, reinforce that the earnings base is currently robust. In the short term, the key swing factor remains how quickly Taco Bell traffic and margins stabilise after recent softness.
The biggest risk is that weaker demand or heavier discounting at Taco Bell, together with reliance on the Byte digital and AI platform, erodes restaurant level profitability rather than supporting it. The latest earnings do not remove that risk. They simply give Yum! Brands more room to absorb setbacks if execution or customer demand disappoints.
The KFC Muse launch in Dubai is the clearest operational bridge between the earnings story and future catalysts. Yum! Brands is using KFC as the development engine, and this new flagship format folds in updated branding, a specialty beverage platform and a more experiential layout that encourages longer visits. It ties directly into the thesis that KFC unit growth and higher digital engagement can reshape the group earnings mix.
If KFC Muse in Dubai and the planned Seoul site validate higher throughput, stronger beverage attach rates and customer appetite for more immersive restaurants, that supports the idea that KFC can keep carrying more of the growth load while Taco Bell works through its issues. The risk is that these concepts prove costly to roll out at scale or that returns per store do not justify broader adoption, which would blunt an important potential catalyst in the Yum! Brands story.
Yum! Brands' current analyst script points to revenues of US$9.7b and earnings of US$2.1b by 2029, based on a projected 3.6% yearly rise in revenue and a shift in profitability that reduces earnings by US$0.1b from the current US$2.2b base.
Uncover why Yum! Brands' fair value indicates a 7% potential upside to its current price that may not last much longer.
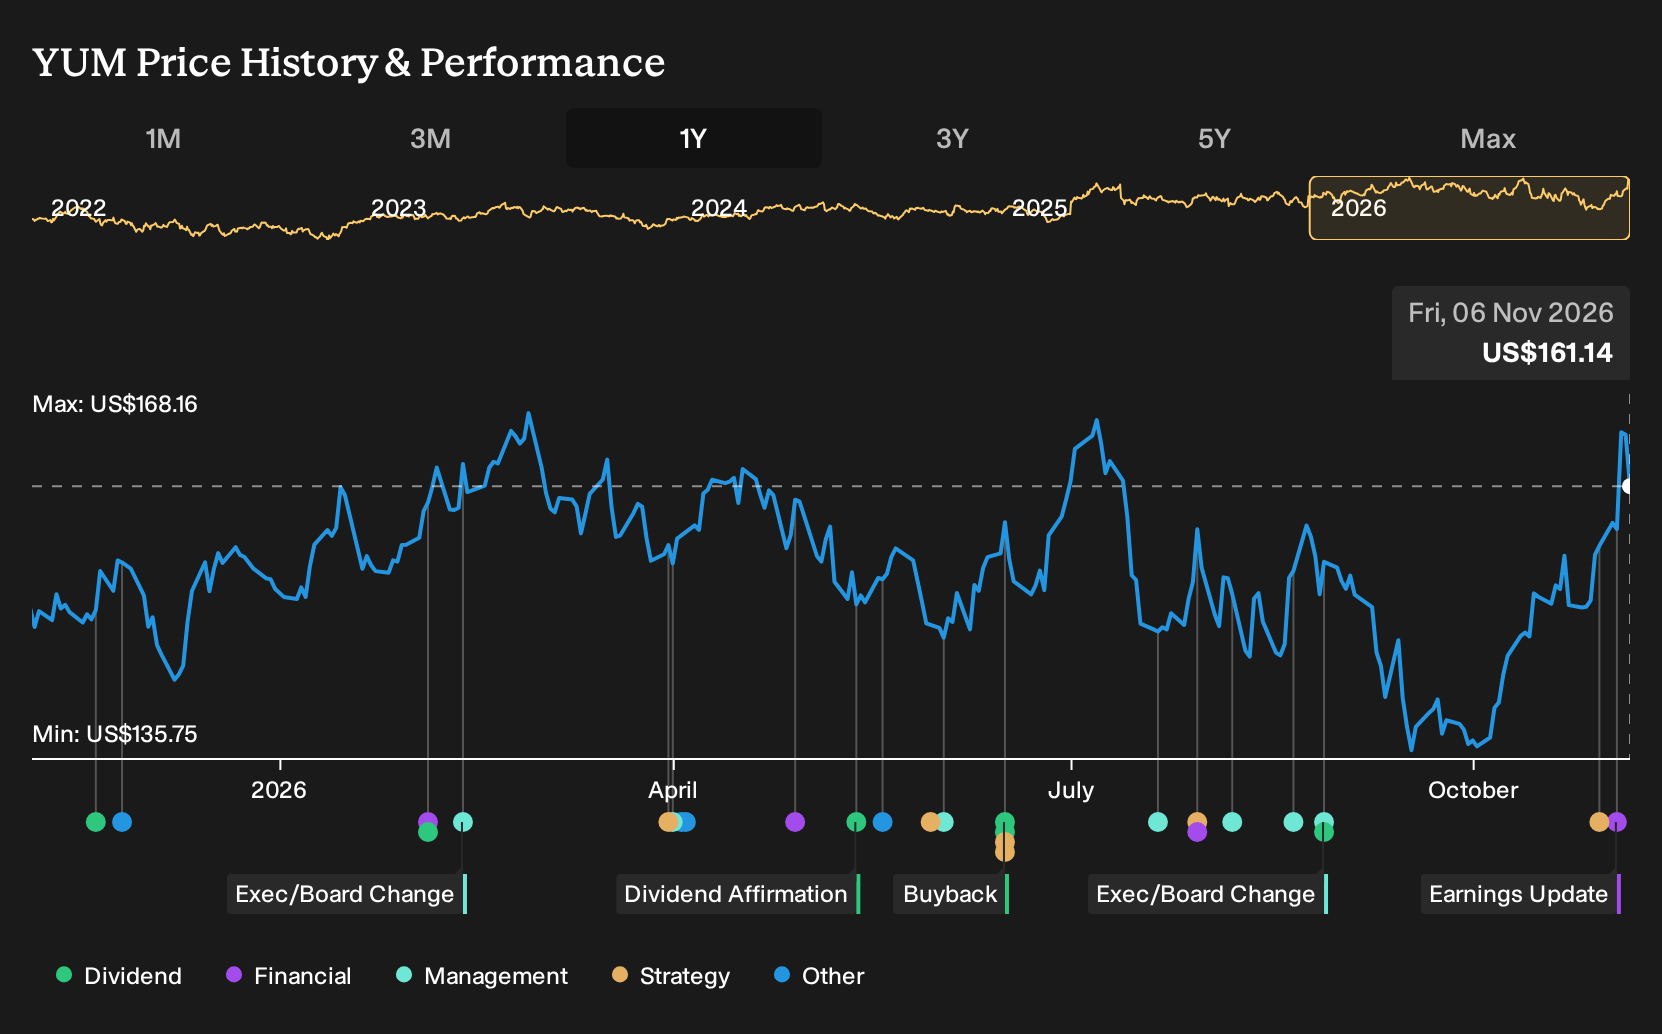
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster in a tight band between about US$163.80 and US$174.87, so private investors there are currently framing Yum! Brands within a relatively narrow valuation range. You still face meaningful disagreement on Byte execution risk, Taco Bell traffic pressure and the potential lift from KFC Muse, which makes it worth comparing several opposing views before forming your own stance.
Explore 2 other Yum! Brands fair value estimates, including one that suggests it could be worth just $163.80.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Yum! Brands research is our analysis highlighting 3 key rewards and 5 important warning signs that could impact your investment decision.
- See our latest analysis for Yum! Brands. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Yum! Brands' overall financial health at a glance.
Looking For More Investment Ideas Beyond Yum! Brands?
Once you have a view on Yum! Brands, it can help to compare that thesis with other companies that share similar quality traits or very different risk profiles. That context keeps you honest and often surfaces ideas you would not have considered on your own.
- If you want to focus on resilience and balance sheet strength, start with companies that show consistent fundamentals in our list of solid balance sheet and fundamentals (25 results).
- For investors who care most about valuation support and quality fundamentals, scan the 38 high quality undervalued stocks to see which opportunities currently line up with those preferences.
- If you are hunting for under the radar stories that could be earlier in their journey, broaden your watchlist with the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com