


EN
Cameco (TSX:CCO) Renews Equity Capacity On A Valuation Story Still Under Debate
Cameco (TSX:CCO) has moved back into the spotlight after renewing an at the market equity program of up to US$1b and filing a fresh US$3b universal shelf registration.
The renewed capital programs land at a choppy moment for Cameco. The share price jumped 5.01% on the day to CA$100.65, yet it is still down 19.87% over the past 30 days and 25.81% over 90 days, while the 1 year total shareholder return has declined 22.09% but remains strongly positive over three and five years. Recent earnings in late October, a narrowed 2026 production and sales range, continued dividend payments for 2026, and an upcoming CFO transition all sit in the background as investors reassess growth plans and risk around new equity issuance and the US$3b shelf capacity.
Scan how Cameco’s funding move compares to other nuclear fuel and infrastructure plays by running through the hand picked 17 nuclear energy infrastructure stocks list immediately after this headline shift.
Cameco has already given back a big chunk of its multi year gains, just as it lines up fresh equity capacity. Is most of the easy upside gone, or does the current valuation still leave real room?
Most Popular Narrative: 42% Undervalued
Cameco’s most followed valuation view pegs fair value around CA$174.57 per share, well above the recent CA$100.65 close. This puts the fresh equity capacity and recent pullback into sharper focus for anyone weighing dilution risk against long term upside.
Cameco continues to be tied to a global wave of new nuclear construction, with government-backed programs in countries such as Canada, the U.S. and those pledging to expand nuclear capacity expected to support uranium and fuel demand over many years, which can feed into higher long-term revenues.
Momentum in utility contracting remains a live driver. Long-term uranium contracting is still below replacement rates, and Cameco is deliberately limiting new contract volumes while pushing for higher floors in the high US$70s per pound and ceilings around US$160 per pound on longer-tenor deals. This supports pricing power and potential net margin expansion.
See why 164 investors see Cameco as 42% undervalued.
Result: Fair Value of CA$174.57 (UNDERVALUED)
Still, Cameco’s story can change quickly if Saskatchewan disruptions persist, or if Westinghouse project milestones and related earnings arrive more slowly than analysts model.
Find out about the key risks to this Cameco narrative.
Another View: Cameco Looks Expensive On Earnings
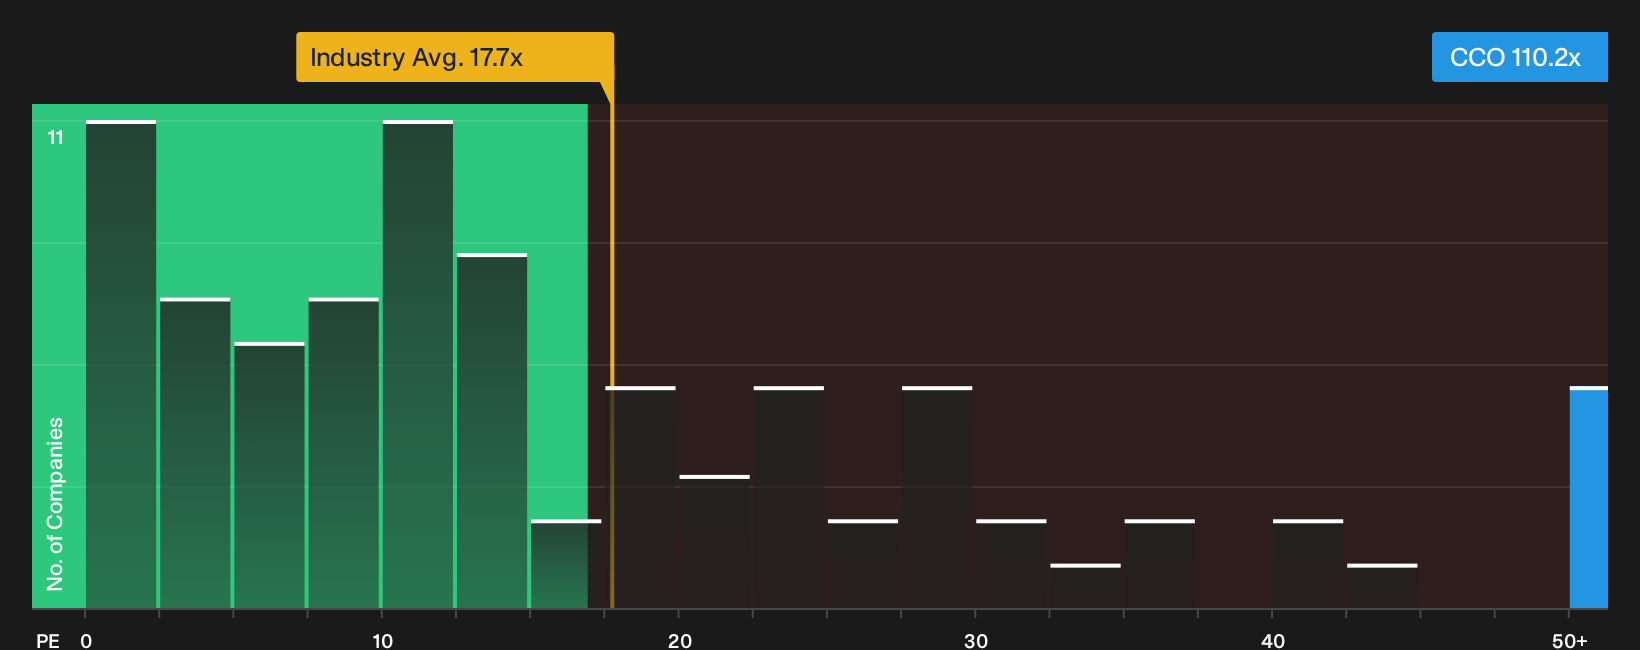
There is a catch. While the popular fair value for Cameco leans on analyst cash flow and earnings projections, the plain P/E picture looks stretched. The stock trades on roughly 110.2x earnings compared with about 20.4x for peers and a fair ratio estimate of 31.5x.
That leaves a wide gap between what the narrative says Cameco could earn in future and what investors are already paying today. If the share price drifts closer to that fair ratio, how much of the perceived upside survives?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Does the mixed tone on Cameco leave you excited or uneasy about where value sits today, and how fast sentiment can flip? Act quickly and weigh that against the company’s optimistic signals by reviewing the 3 key rewards.
Looking for more investment ideas beyond Cameco?
If Cameco has sharpened your focus on where risk and reward meet, do not stop here. A broader watchlist can reveal opportunities you would otherwise miss.
- Target potential upside by zeroing in on quality companies trading below estimated worth through the 7 high quality undervalued stocks.
- Strengthen income potential by reviewing companies offering higher yields with resilient payouts using the 3 dividend fortresses.
- Dial down portfolio stress by scanning for companies that score well on stability through the 9 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com