


EN
3 US Regional Bank Stocks Built For Higher Interest Rates
Interest rates that stay high for longer can quietly reshape winners and losers across markets, and not only in the obvious places. When borrowing costs remain elevated, some businesses pick up extra income on cash and investments, while others face heavier funding pressure and slower deal activity. This article walks through three U.S. bank and insurer stocks exposed to that higher-for-longer story and explains how the same macro shock can hit each of them in very different ways.
The banks and insurers that follow are just a small sample of this theme, and the full screen surfaced 20 more U.S. companies with similarly compelling rate stories that are not covered below. To see the wider field and identify which higher-for-longer plays best fit your own risk and return preferences, head straight into the US Banks and Insurers Benefiting from Higher-for-Longer Interest Rates screener.
HomeTrust Bancshares (HTB)
HomeTrust Bancshares is a regional bank holding company built around old fashioned lending and deposit gathering, with a single Banking segment generating about US$213 million in revenue, all in the United States. The stock’s market value sits around US$736 million, giving investors focused exposure to higher-for-longer policy rates.
HomeTrust Bancshares offers clean exposure to higher-for-longer rates because its earnings lean heavily on loans, deposits, and net interest income that all react directly to policy moves. Recent results show meaningful net interest income and solid profitability, yet one unresolved pressure on credit reserves could still reshape how much of that rate benefit reaches the bottom line.
That reserve question is significant, so review the 3 key rewards and 1 important warning sign to see how rate sensitivity and credit risk could be pulling in different directions.

Colony Bankcorp (CBAN)
Colony Bankcorp leans directly into the higher for longer rates theme, since most of its earnings potential comes from classic lending and deposit banking while newer fee lines reshape how sensitive the overall profit mix is to the rate curve.
"The build out of fee-based businesses such as Colony Financial Advisors and Colony Insurance, including almost 15% quarter over quarter growth in assets under management to US$637 million and record pretax income in the insurance unit, positions Colony Bankcorp to generate more noninterest income and reduce reliance on spread revenue over time."
The real swing factor for Colony Bankcorp is how one pressure on future funding costs intersects with that evolving fee mix and merger scale.
That funding twist is exactly where the full narrative for Colony Bankcorp shows how Colony Bankcorp’s fee engine, merger story, and rate exposure could be quietly decoupling from the headline numbers.
Arrow Financial (AROW)
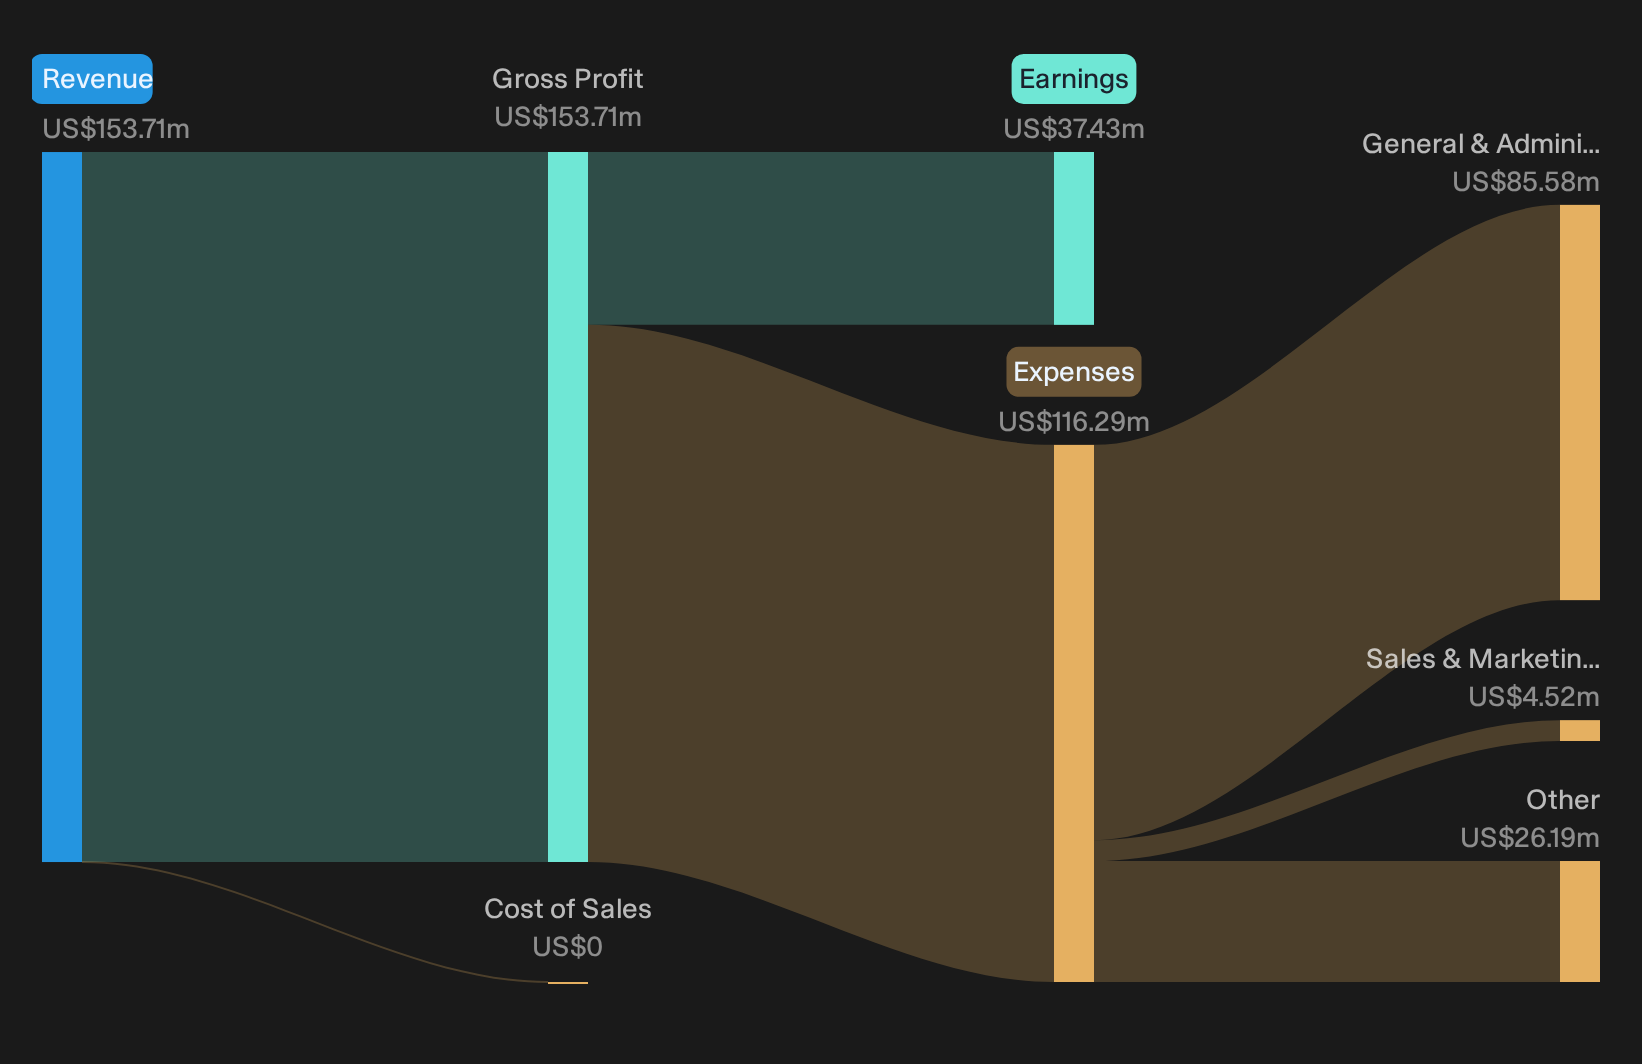
Arrow Financial is a Glens Falls based commercial and consumer bank that reflects the higher for longer rate theme, with core earnings tied to net interest income on loans and deposits. It generates about US$187 million from Community Banking in the United States and carries a market value near US$713 million.
Arrow Financial is firmly positioned in the higher for longer camp, with core earnings linked to net interest income and Q3 2026 net interest income at US$48.73 million. Solid profitability and a 3.12% dividend yield are notable features, while pressure on net income illustrates the impact when an unseen funding and credit pressure persists.
That hidden pressure on Arrow Financial’s funding and credit story makes the Arrow Financial financial health report a useful way to see what the headline numbers might be masking.

Seeking Alternatives Before The Crowd?
Fresh breakout stories move fast, momentum can vanish, and quiet winners get caught once attention floods in. Scan under the radar for now and act now.
- Spot underfollowed quality before momentum really flies by scanning a curated set of 19 high quality undiscovered gems while the window for calmer entry points is still open.
- Lock in your shortlist of resilient payers using a hand picked pool of 7 dividend fortresses before yields drop and everyone else chases the same income ideas.
- Explore the next wave of automation opportunities by filtering a focused basket of 90 robotics and automation stocks while these stories are still in quieter phases of the market.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com