


EN
East West Bancorp (EWBC) Expands Cross Border Payments, Is It Still 14% Below Fair Value?
East West Bancorp (EWBC) has drawn fresh attention after reports of deeper cross-border payment links in Hong Kong and a new mainland China solution, paired with a push into fee-based wealth management via its own registered investment adviser.
Despite the latest cross-border and wealth initiatives, East West Bancorp’s share price has moved more quietly, with a 30 day share price return of 2.64% and an 11.98% share price gain year to date. Total shareholder return over three years is up 146.40%, suggesting longer term momentum has been much stronger than the recent pullback over the past quarter.
Compare East West Bancorp’s cross border push with other banks that are positioning for fee growth and stronger balance sheets by scanning our hand picked list of solid balance sheet and fundamentals (25 results).
Bulls point to East West Bancorp’s cross border momentum and fee ambitions. Bears flag the quieter share price. The valuation work next shows which side the current numbers lean toward.
Most Popular Narrative: 14% Undervalued
East West Bancorp’s most followed narrative pegs fair value at $150, compared with a last close of $128.84. This puts the current share price at a clear discount while the market weighs cross border growth against fee swings and funding costs.
Very strong capital levels and efficiency, with East West Bancorp generating mid to high teens return on tangible common equity on a tangible common equity ratio above 10% and maintaining a sub 40% efficiency ratio, give it room to keep funding organic growth initiatives and product expansion that can support future earnings.
See why 24 investors see East West Bancorp as 14% undervalued.
Result: Fair Value of $150 (UNDERVALUED)
Still, the story around East West Bancorp can shift quickly if competition for deposits keeps funding costs elevated or if fee income remains choppy from quarter to quarter.
Find out about the key risks to this East West Bancorp narrative.
Another View: What East West Bancorp’s P/E Is Saying
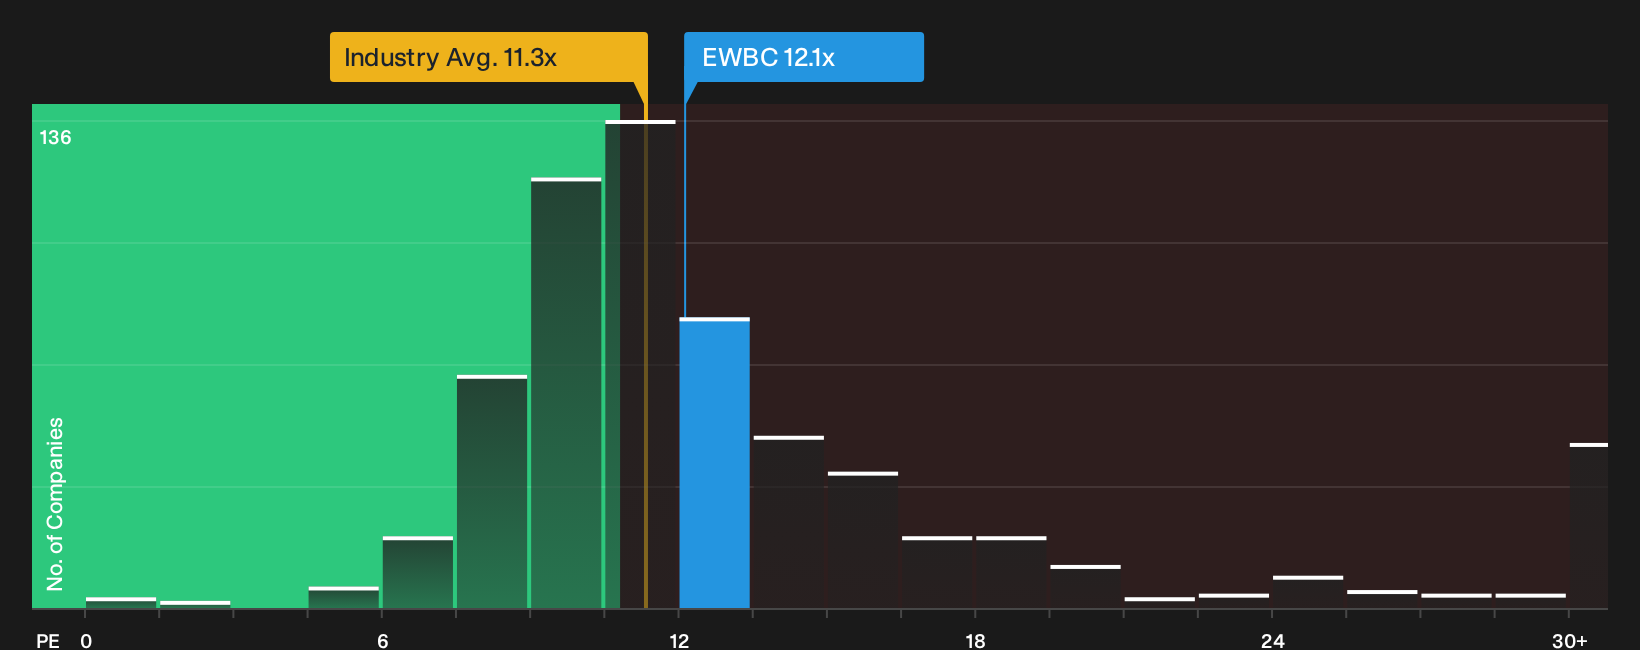
The SWS DCF work suggests East West Bancorp trades at a discount to its future cash flow value, yet the simple P/E tells a cooler story. At 12.1x earnings, the stock is slightly above the US Banks industry on 11.3x but below its own fair ratio of 12.9x. That mix hints at some valuation cushion but also less obvious upside than a pure DCF number might imply. Which signal do you put more weight on: the cash flow model, or the earnings multiple you can compare across every other bank on your list?
See what the numbers say about this price, find out in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty in this East West Bancorp story points to optimism, yet the real test is how you read the data on your own terms. Act quickly, weigh the moving parts for yourself, and then drill into the upside case by reviewing the 4 key rewards
Looking for more East West Bancorp style investment ideas?
If East West Bancorp has sharpened your focus on quality and price, do not stop here. Broaden your watchlist now so the next opportunity does not slip past.
- Target high quality potential by reviewing companies that screen well on value and fundamentals through the 38 high quality undervalued stocks.
- Prioritise resilience by scanning a 31 resilient stocks with low risk scores that highlights businesses with sturdier profiles when conditions get tougher.
- Hunt for under the radar potential by checking a 19 high quality undiscovered gems that many investors may not be watching yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com