


EN
Andersons (ANDE) Stock Still Looks Reasonable On Its 59% Five Year Run
Andersons has climbed over the past five years despite a recent pullback, and that mix of long term gains and short term weakness puts fresh focus on whether its current share price lines up with what its earnings can support.
- The stock has returned 58.9% over 5 years, which raises the question of how much of that gain is backed by the underlying profit engine of the business.
- The planned US$915 million purchase of Harvestone Low Carbon Partners may reshape Andersons' earnings profile as ethanol capacity, low carbon fuel exposure, and carbon capture projects feed into future profitability and capital needs.
- There is a second opinion on Andersons worth weighing. See what analysts think Andersons's shares could be worth.
The issue now is whether the earnings that Andersons generates today, and what investors expect them to look like over time, are enough to justify where the stock trades after this mix of long term gains and recent news.
If you want a second reference point while you assess Andersons around this acquisition and earnings story, run the same earnings lens across 38 high quality undervalued stocks.
Is Andersons a Bargain on Earnings?
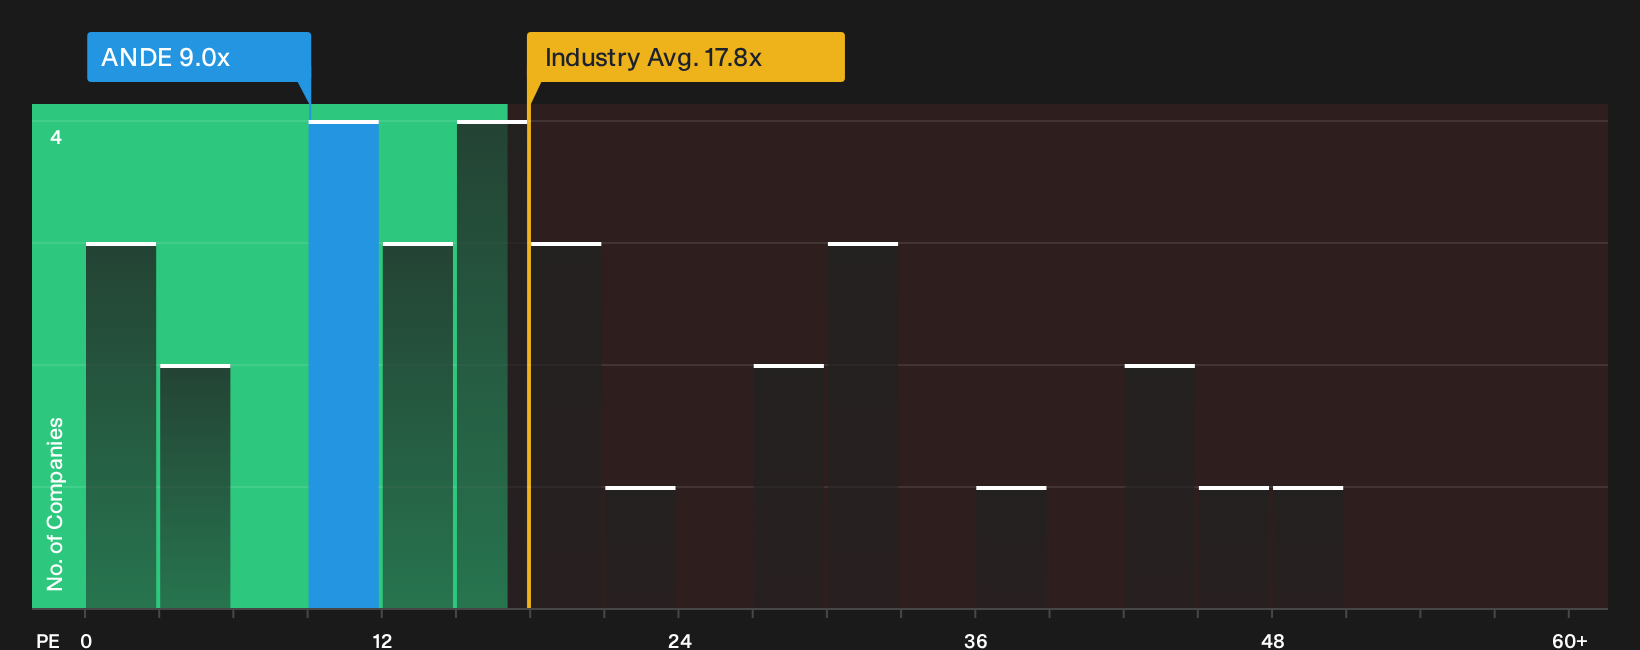
P/E fits Andersons well because earnings are a key reference point for a business that still leans on relatively mature grain and renewables operations. On that lens, the stock trades at about 9.0x earnings, versus roughly 17.8x for the broader Consumer Retailing group and close to 33.1x for peers flagged in this data. A tailored fair multiple that factors in Andersons' growth profile, profitability and risk sits higher than the current level, so this framework points to the shares looking undervalued on earnings.
Because the Harvestone deal is expected to add to earnings and cash flow, the gap between Andersons' 9.0x P/E and richer sector and peer valuations matters more than usual for anyone weighing the story around low carbon fuels. The key question for you is whether the integration and capital demands tied to ethanol, carbon capture and related projects justify that discount or leave room for the rating to close toward those benchmarks over time. Explore the numbers behind Andersons's P/E valuation.
The Andersons Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Andersons pick up where the P/E puzzle leaves off, and explain which earnings, margin and growth paths would need to hold for the stock to appear meaningfully cheaper or richer than today’s price on the Community page. Each scenario links a specific valuation to a clear set of potential catalysts and risks for Andersons' grain and renewables mix so you can track which version of the story is actually unfolding over time.
One of the top community narratives on Andersons: 35% undervalued
"The main thing that has to go right is that Andersons converts record renewables profitability, expanding premium ingredients capacity, and new export infrastructure…"
Discover why this Narrative puts Andersons at 35% undervalued.
One more Andersons check that sits next to the P/E story
Price comparisons tell you what the market is paying for Andersons today, but professional models that look a few years out give you a different lens on where expectations already sit. Explore where analysts expect Andersons to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com