


EN
Learn Why The Bull Case For Murphy Oil Stock Could Change Following Earnings Beat
- Murphy Oil reported third quarter 2026 revenue of US$854.97 million and net income of US$171.12 million, with basic earnings per share from continuing operations of US$1.19, alongside raised full year 2026 production guidance and new offshore Mauritania production sharing contracts.
- The combination of stronger profitability, higher 2026 production targets and a 90% operated interest in large Mauritanian offshore blocks gives Murphy Oil a broader set of cash flow and resource options to fund its multibasin program and manage future capital spending trade offs.
- We will now see how Murphy Oil’s investment narrative could shift as stronger earnings are reported together with higher production guidance for 2026.
Murphy Oil Investment Narrative Recap
For an investor to stay with Murphy Oil, the belief has to be that higher capital spending and multibasin exposure can translate into durable earnings and cash flow, not just one strong quarter. The latest results, with revenue of US$854.97 million and net income of US$171.12 million, support that view in the near term but do not remove execution risk.
The raised 2026 production guidance makes the short term catalyst very clear. You are essentially watching whether Murphy Oil can deliver those higher barrels at acceptable unit costs while funding a larger program. The main near term risk remains that expensive offshore and appraisal activity fails to meet volume or return expectations.
The guidance update on production is the announcement that ties closest to this earnings beat. Management now expects 176,000 to 178,000 BOEPD for full year 2026, compared with higher fourth quarter guidance of 174,000 to 182,000 BOEPD. That frames how much operational progress needs to show up quickly in the field.
For you as a shareholder, this tighter and higher range shapes the immediate catalyst. Stronger earnings give Murphy Oil more room to pursue Bubale, Vietnam, the Eagle Ford and now Mauritania. The trade off is straightforward. If project costs or geology disappoint, the same capital plan could pressure free cash flow and dividend cover.
Murphy Oil's current earnings of US$295.2 million are set against analyst forecasts for US$3.3b in revenue and US$679.5 million in earnings by 2029. This framework implies 3.6% yearly revenue growth and an earnings increase of roughly 2.3x from today's level by that same 2029 horizon.
Uncover how Murphy Oil's fair value indicates a 17% potential upside to its current price before the market closes that gap.
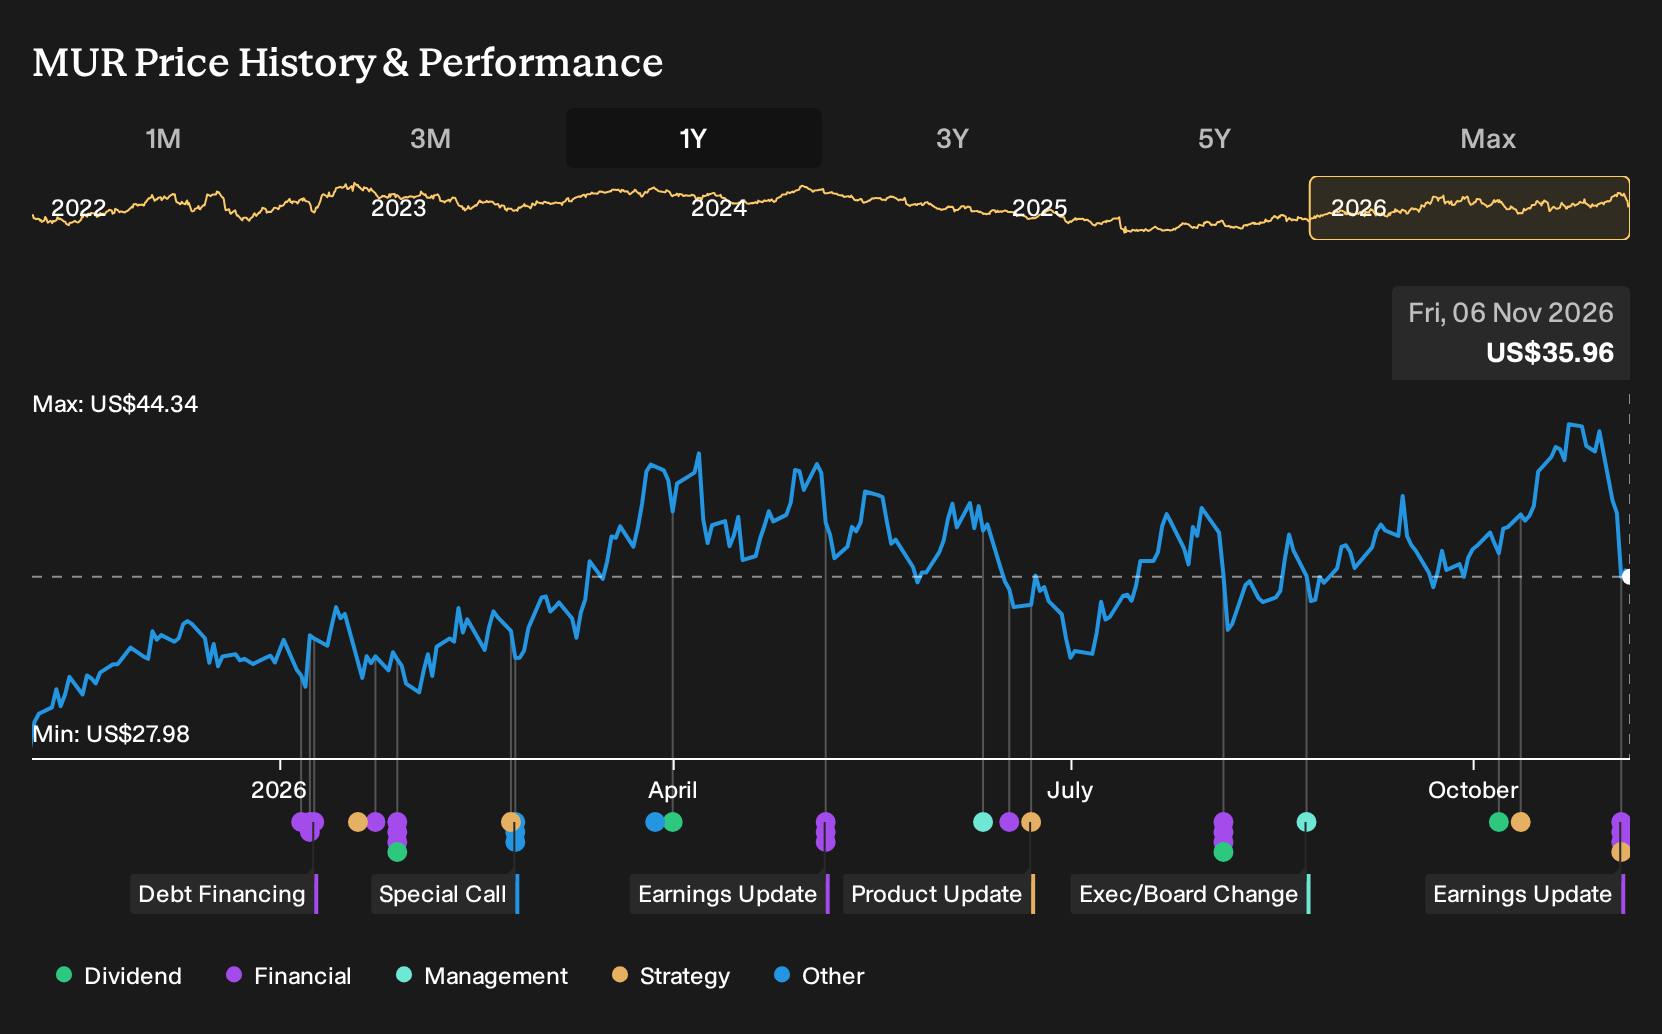
Exploring Other Perspectives
One alternate view focuses on Murphy Oil’s heavier capital plans as the key risk. The most cautious analysts were only pencilling in revenue of about US$3.3b and earnings of roughly US$504.7 million by 2029 before this report, which is well below the consensus path. That gap shows how sharply opinions can differ, so it can help to review both sets of forecasts and decide which story you find more convincing as the new Mauritania contracts and higher 2026 guidance filter into future models.
Explore 2 other Murphy Oil fair value estimates, including one that suggests it could be worth just $41.93.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Murphy Oil research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Murphy Oil. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Murphy Oil's overall financial health at a glance.
Looking for more investment ideas beyond Murphy Oil?
Once you have a clear view on Murphy Oil, it can help to widen the lens and see how other opportunities stack up on quality, income potential and risk.
- For investors who want resilient balance sheets and steady fundamentals, start with a focused list of solid balance sheet and fundamentals (25 results) that filters out weaker financial profiles.
- If dependable income is a priority, scan a hand picked set of high yield payers using the 7 dividend fortresses to see which payouts line up with your risk tolerance.
- When you are hunting for under followed quality, cast a wider net across a 19 high quality undiscovered gems that highlight stronger fundamentals without the heavy spotlight yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com