


EN
W.W. Grainger (GWW) Could Be 10% Undervalued After Strong Earnings And Higher Outlook
Why Grainger’s latest earnings matter for shareholders
W.W. Grainger (GWW) just posted third quarter results that showed higher sales, a larger net income figure and a sharp step up in earnings per share compared with a year earlier.
For the first nine months of 2026, the business also reported stronger figures, along with a higher full year outlook and a recently affirmed dividend. Together, these provide investors with fresh numbers to assess the stock.
On the market side, W.W. Grainger’s share price has climbed 43.52% year to date and 11.70% over the past month. The 1-year total shareholder return of 52.10% and 5-year total shareholder return of 208.02% indicate momentum that recent earnings and the October dividend affirmation appear to have reinforced.
Scan how W.W. Grainger’s move fits alongside other strong operators in similar niches by checking the hand picked list of solid balance sheet and fundamentals (25 results) in the current market.
Bulls point to W.W. Grainger’s earnings surge and upgraded outlook. Bears highlight a share price that already reflects a lot of that optimism. Which side do the current valuation metrics support next?
Most Popular Narrative: 10% Undervalued
At a last close of $1,440.70 versus a narrative fair value of $1,600, the most followed view sees W.W. Grainger trading at a discount that depends heavily on execution in its core platforms.
The main thing that has to go right is that W.W. Grainger keeps translating digital growth, large project activity, and new distribution and inventory management capabilities into sustained High-Touch and Endless Assortment profitability despite ongoing cost pressures.
See why 1 investors see W.W. Grainger as 10% undervalued.
Result: Fair Value of $1,600 (UNDERVALUED)
Still, the bullish W.W. Grainger story can crack if gross margin pressure persists or if the CFO transition leads to looser cost and capital discipline.
Find out about the key risks to this W.W. Grainger narrative.
Another View: What Grainger’s P/E Is Telling You
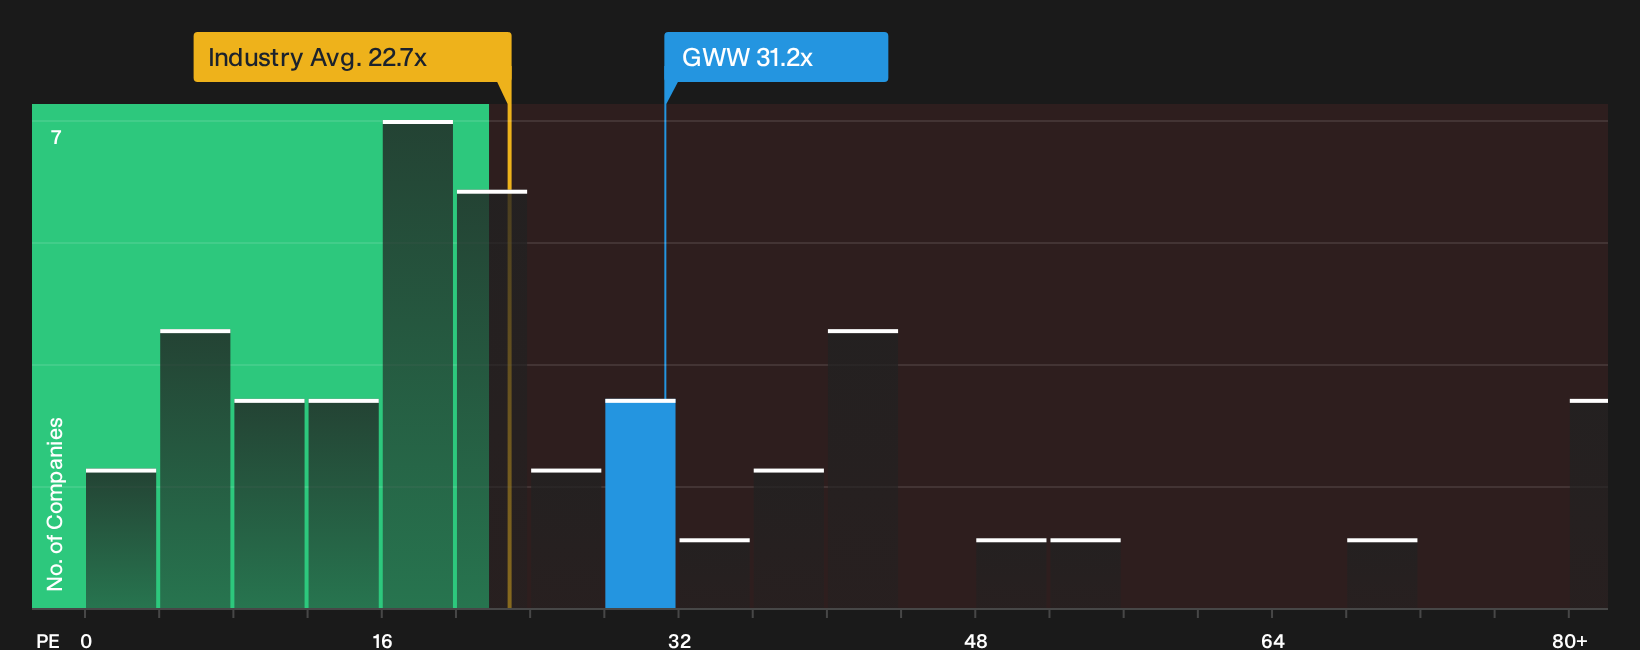
There is a very different message coming from W.W. Grainger’s current P/E of 31.2x. That figure sits above the US Trade Distributors industry on 22.7x and above peer averages of 27.8x, and it is also richer than the 25.4x fair ratio our model suggests the market could move toward over time.
A valuation that far ahead of both sector levels and the fair ratio can mean the stock price already bakes in strong execution. This raises the risk that even solid results do not translate into further upside if expectations cool. The question for you is whether that premium feels justified by the growth and profitability profile you see, or whether it simply narrows the margin for error from here.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on W.W. Grainger so far. If you want to move quickly and form your own view, compare the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond W.W. Grainger?
If W.W. Grainger’s story has you thinking harder about valuation and quality, do not stop with a single ticker when the wider market is full of contrasts.
- Target resilient balance sheets by scanning the list of solid balance sheet and fundamentals (25 results) that pair financial strength with fundamentals you can scrutinize in detail.
- Hunt for potential mispricing by reviewing the 38 high quality undervalued stocks that match solid business quality with prices that may not fully reflect it yet.
- Build a cash flow focused watchlist by using the 7 dividend fortresses that combine higher yields with businesses you can analyze side by side.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com