


EN
Did EZTEC's Fall Catch You Out? What Investors Missed
If you had seen the bullish and cautious cases on EZTEC Empreendimentos e Participações back in November 2025 and decided to stay on the sidelines, the next twelve months might now look different through the rear-view mirror. For EZTEC Empreendimentos e Participações shareholders, the loss over the past year was 31.8%, including dividends. With Q3 2026 showing lower revenue and a thinner net margin than Q3 2025, which early assumption would you revisit first?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
If the move has made EZTEC Empreendimentos e Participações harder to judge, start where the gap is still open and scan 223 high quality undervalued stocks.
The Argument You Would Have Been Weighing Up On EZTEC Empreendimentos e Participações
The shares cost R$18.6 at the start of the period, and any investor looking at EZTEC Empreendimentos e Participações then had to choose which story seemed more reasonable.
On the optimistic side, the bullish narrative pointed to a fair value of R$28, leaning on expectations that revenue could grow 11.7% a year and that a heavier push into middle-income projects and digital sales would support that expansion.
The more cautious view put fair value at R$17.35, with assumptions of 2.6% annual revenue growth and a risk that São Paulo concentration and rising construction costs could pressure margins.
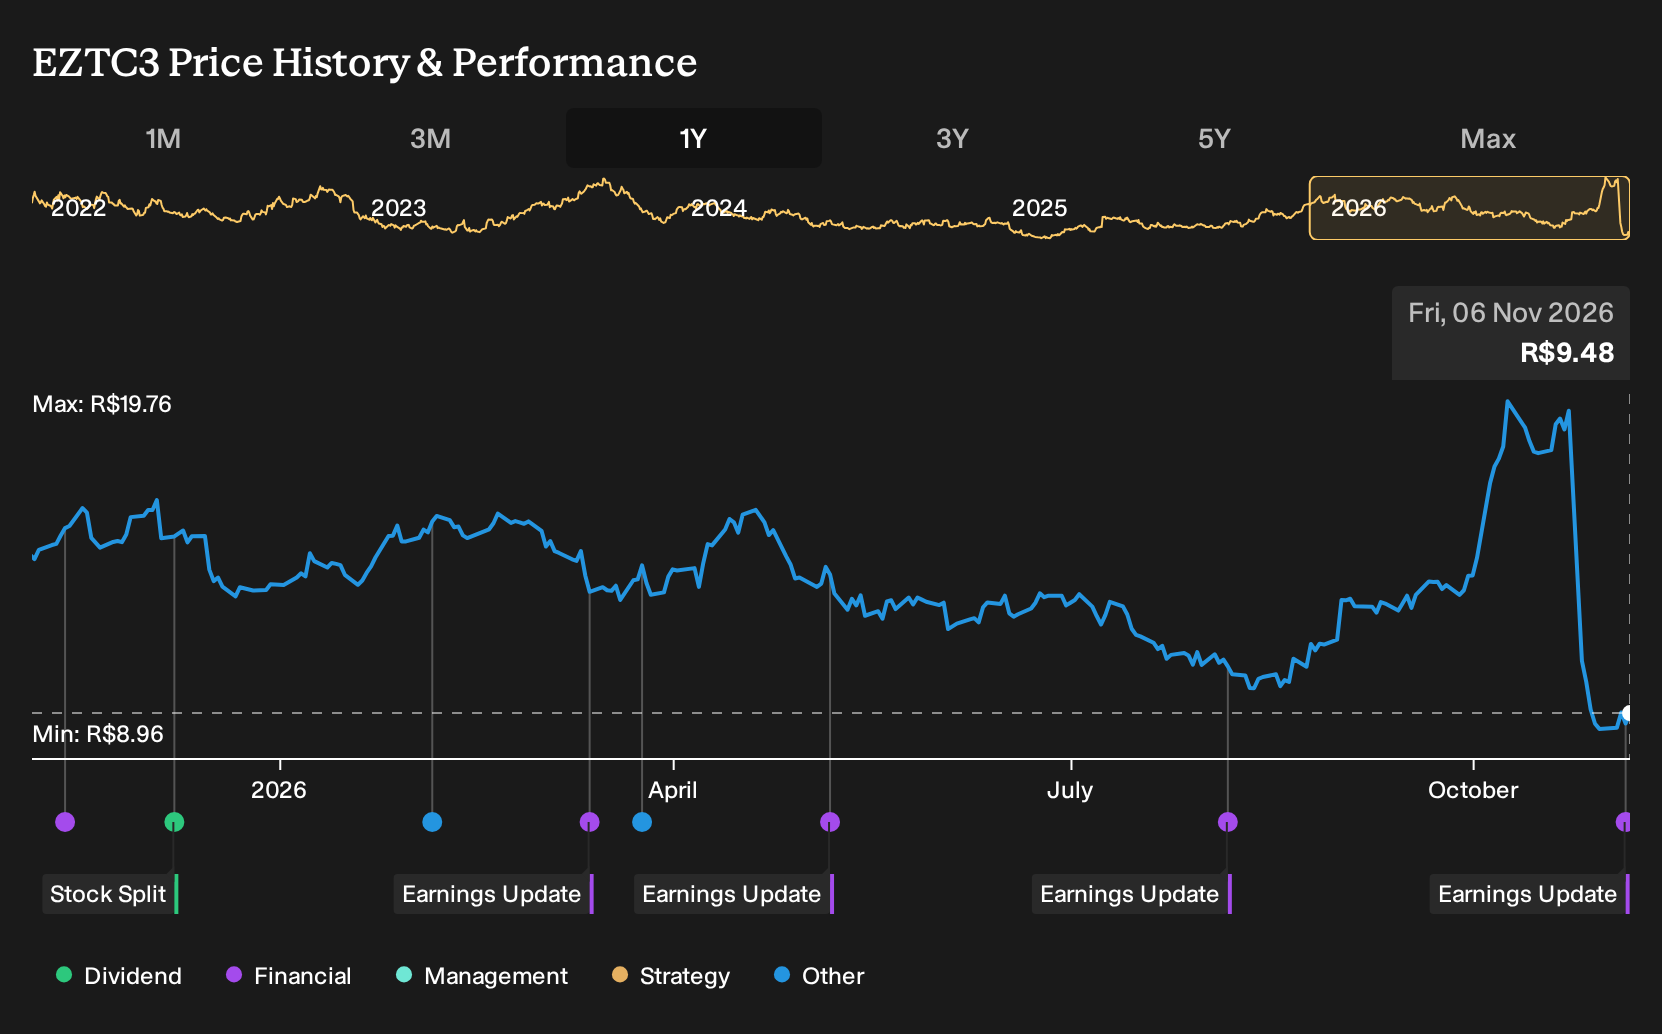
What The Results Changed For EZTEC Empreendimentos e Participações
Q3 2026 results gave EZTEC Empreendimentos e Participações investors a tougher fact pattern to weigh. Revenue moved from R$469.356m in Q3 2025 to R$346.41m in Q3 2026, and net income shifted from R$183.453m to R$85.421m. Net margin went from 39.1% to 24.7%, which leaned toward the cautious case on profitability resilience.
The practical takeaway is simple. When a thesis leans on strong and steady margins, you need to track the reported net margin each quarter and test whether it is holding near the level the story assumed.
What You Are Being Asked To Believe At Today's EZTEC Empreendimentos e Participações Price
EZTEC Empreendimentos e Participações now trades at R$9.48, and this selected Narrative’s Fair Value sits above that quoted level. The market is treating the one year fall of about 32% as a verdict on recent margins and launches.
The Narrative instead focuses on receivables income, heavier project launches and leasing potential. For that higher figure to be reached, a buyer today would need to assume EZTEC continues turning its land bank and receivables book into profitable cash generation.
"The main thing that has to go right is that EZTEC Empreendimentos e Participações keeps converting its large land bank and proprietary receivables portfolio into profitable launches and net cash generation even with high interest rates and construction cost pressure."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
One Step Beyond EZTEC
EZTEC is all about getting homes built in Brazil. Your next question might be where similar housing demand could surface elsewhere.
In another market, a major government housebuilding push has reshaped the rulebook. Planners want more affordable units and community infrastructure wrapped into each project.
That creates a clear problem for builders. Someone has to convert new planning rules and mixed-tenure requirements into real streets and finished homes.
One construction group has been doing exactly that, threading private sales together with different affordable housing tenures. Its outlook now depends less on policy headlines and more on how quickly permissions turn into actual completions.
One Narrative has already put a figure on it. → Uncover the company trading 20% below one Narrative's Fair Value
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com