


EN
Is Methanex (TSX:MX) Fully Priced Following Earnings, 2026 Guidance And Buyback Plan?
Why Methanex stock is back in focus
Methanex (TSX:MX) just packed a lot into one day. Fresh 2026 production guidance, detailed third quarter results, and a new share buyback plan all landed together on October 29, 2026.
All of this lands after a powerful run in Methanex, with the share price at CA$93.77, a 90 day share price return of 21.91% and a 1 year total shareholder return of 81.27%, suggesting momentum has been building even as the latest 7 day share price return has pulled back 6.09%.
Scan 7 high quality undervalued stocks that, like Methanex after this packed guidance, earnings, and buyback update, already have momentum on the chart and fresh news in the background.
Methanex just delivered stronger earnings, fresh production guidance, and a buyback plan after a big share price run. Does that mix still tilt the risk reward toward buyers at this valuation, or has most of the upside been front loaded?
Most Popular Methanex Narrative: 3% Overvalued
Methanex is trading at CA$93.77 against a widely followed fair value estimate of CA$91.07. This leaves the story leaning slightly rich and puts more pressure on the operating plan to keep supporting that premium.
Methanex expects methanol demand to grow in 2025, driven by traditional chemical and energy applications, which could boost revenues. Increased production at key facilities, such as Geismar and Chile, along with improved operational efficiency, positions the company to capitalize on favorable pricing, potentially enhancing net margins and earnings.
See why 15 investors see Methanex as 3% overvalued.
Result: Fair Value of CA$91.07 (OVERVALUED)
Still, the Methanex narrative hinges on reliable contracted gas supply and smooth OCI integration, and disruptions in either could quickly challenge those margin and earnings assumptions.
Find out about the key risks to this Methanex narrative.
Another View on Methanex valuation
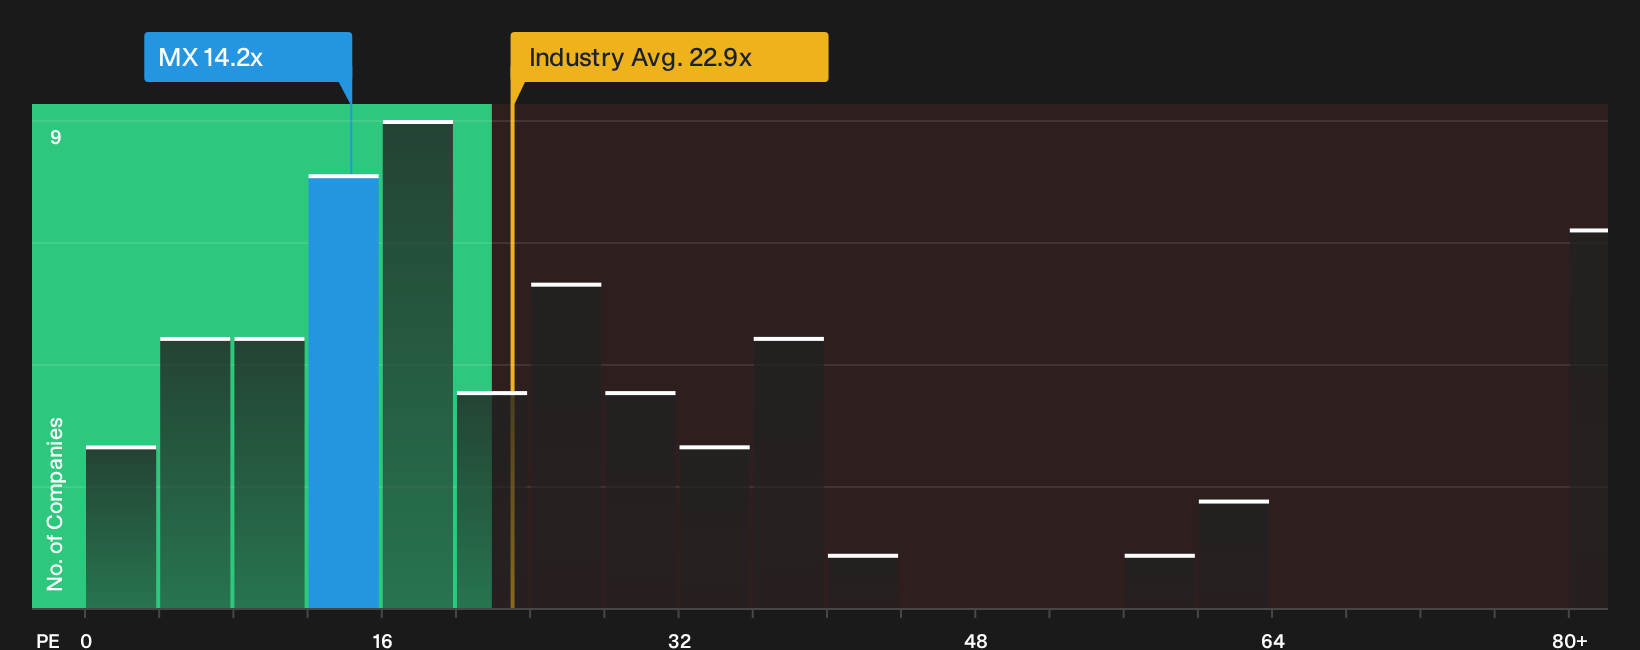
The fair value narrative says Methanex at CA$93.77 is slightly rich versus the CA$91.07 target. A different lens tells a softer story. On a P/E of 14.2x, MX trades cheaper than peers at 17x and the wider North American chemicals group at 22.9x.
The catch is that this multiple still sits above a fair ratio of 10.5x, which points to less cushion if sentiment turns. The question for you is whether the stronger past year in earnings justifies that premium or leaves less room for disappointment.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and caution around Methanex feels familiar, that is the point; the story is rarely all one way. Move quickly, review both the upside and downside signals in detail, and ground your own view in the full picture with the 2 key rewards and 3 important warning signs.
Hunting for more ideas beyond Methanex?
Do not stop with Methanex. Broaden your watchlist with fresh candidates that match your style, then pressure test each one before committing real capital.
- Target potential mispricing and filter for quality by reviewing the 7 high quality undervalued stocks that already stack strong fundamentals against their current market prices.
- Prioritise resilience and sleep better at night by scanning a list of solid balance sheet and fundamentals (5 results) built to handle tougher conditions without stretching their finances.
- Get ahead of the crowd and hunt for future leaders hiding in plain sight by studying a 8 high quality undiscovered gems before attention catches up.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com