


EN
What Investors Got Wrong About United Microelectronics Before A 108% Jump
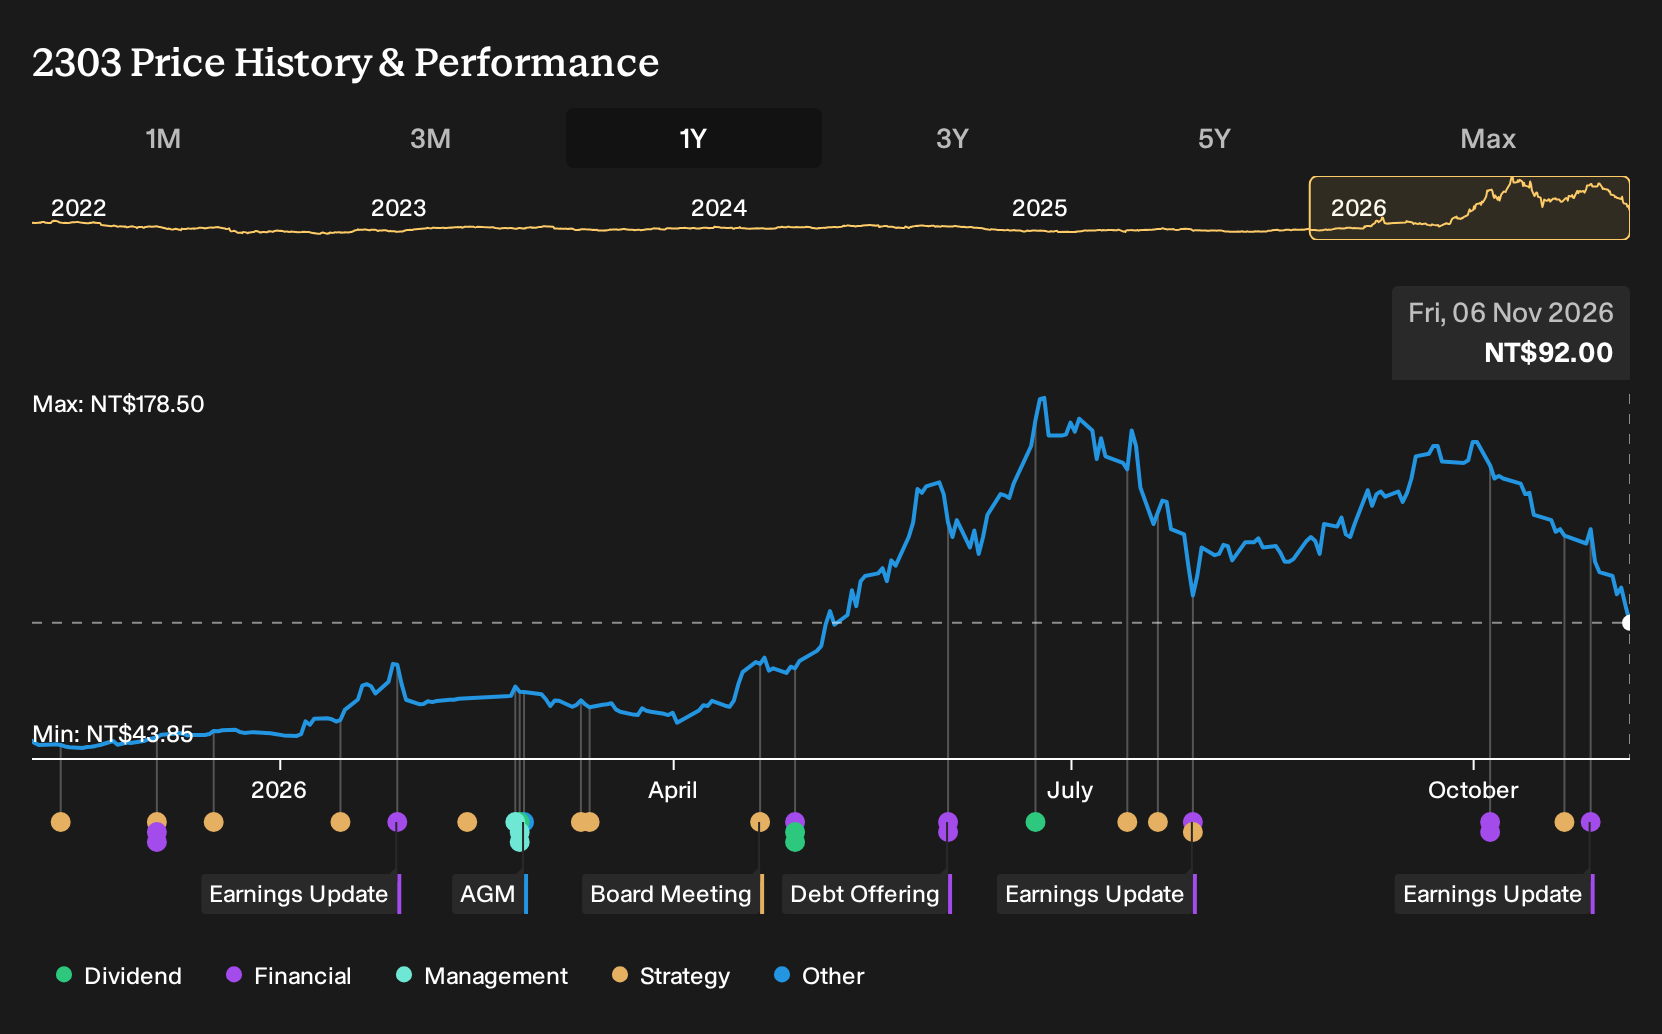
If United Microelectronics sat on your watchlist instead of in your portfolio, the move over the past year may feel like a missed shot. Investors who held United Microelectronics over the past year are up 107.9%, including dividends. That result now sits alongside fresh Q3 2026 numbers and new AI and high performance computing partnerships. What, exactly, in the earlier debate about mature 22 and 28 nanometer capacity and utilization could have hinted this business setup might work so well?
The easy part of this move is behind United Microelectronics. Zero in on 223 high quality undervalued stocks for companies trading below our estimates.
The Two Stories Investors Had To Weigh On United Microelectronics
The shares cost NT$45.85 at the start of the period, which left investors deciding whether United Microelectronics was priced for digitalization upside or for a tougher foundry cycle.
The bullish narrative pointed to a Fair Value of NT$60, a level that reflected confidence in 22 and 28 nanometer demand and in revenue growing 9.7% a year with margins rising from 16.7% to 19.4% by 2028.
The bearish view anchored on a Fair Value of NT$32, built on concern that mature nodes nearing 40% of revenue could face heavy pricing pressure and that earnings might settle near NT$37.5b on slimmer 15.0% margins.
What The Results Changed For United Microelectronics
United Microelectronics posted Q3 2026 revenue of NT$74.24b with capacity utilization at 92%, while 22nm reached a record 18.3% of wafer sales and management approved about US$3.2b in extra capex. Revenue and net income were higher than Q3 2025, yet net margin moved from 25.3% to 22.1%. The evidence cut both ways.
The whole episode turned on whether mature node demand would support both volume and profitability. When you look at another foundry, check if rising utilization and node mix line up with stable or improving net margin instead of only watching headline sales.
What United Microelectronics' Price Now Assumes
United Microelectronics now trades at NT$92 after a 107.9% gain over the past year. The selected Narrative places its own Fair Value below that level and argues the market price leans on optimistic execution rather than a clear margin cushion.
Investors at NT$92 are effectively betting that AI related and specialty revenues scale fast enough to absorb heavy capex and depreciation. The question the selected Narrative poses is how that assumption holds up if utilization or pricing fall short of present guidance.
"The main thing that has to go right for United Microelectronics is that growth from 22nm and 28nm specialty technologies, advanced packaging and silicon photonics is strong enough to offset ongoing margin pressure from rising depreciation. The numbers imply the share price already credits United Microelectronics with successfully scaling AI related and specialty revenues while absorbing higher capex and depreciation without a material hit to profitability."
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all
Go Straight To The Source
The story behind this run has already been told. The next one could be taking shape somewhere else. Where could you start looking before it becomes the headline?
- Company 1 - 15% below our estimate - keeps recruiting fee earners onto an asset light legal platform using surplus cash.
- Company 2 - 43% below our estimate - builds AI driven hiring and local services tools that monetise matching over media spend.
- Company 3 - 29% below our estimate - opens new boutiques and scales digital channels that reportedly repay build costs quickly.
Those are three of them. See the full list of 192 financially solid companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com