


EN
How Strong Earnings Guidance Will Impact Commerzbank (XTRA:CBK) Investors
- Commerzbank reported net income of €2,669 million for the nine months to 30 September 2026, with basic EPS from continuing operations at €2.25, and issued full year 2026 guidance for around €13.2b of total revenues and €3.4b of net income.
- The combination of higher year to date net income than a year earlier, together with quantified full year profit targets, gives investors a clearer view of Commerzbank's earnings power and how current operations are converting into per share results.
- We will look at how Commerzbank's investment narrative is affected by this explicit €3.4b net income target for 2026.
Commerzbank Investment Narrative Recap
To own Commerzbank, you need to be comfortable that its core German retail and corporate banking engine can keep turning current profitability into steady earnings per share, while funding remains reasonably priced and credit costs stay contained. The new guidance of about €13.2b in revenues and €3.4b in net income for 2026 mainly reinforces that operating story rather than rewriting it.
The near term swing factor still sits in funding and credit quality. Pressure on German deposits and a guided risk result of around €850m could squeeze net interest income and returns if conditions worsen. Governance complexity around UniCredit’s large stake and any delay in integration steps also remains a live execution risk that this guidance does not fully resolve.
The clearest operational data point in this news cluster is the nine month 2026 result. Commerzbank reported €2,669m of net income for the period, with basic EPS from continuing operations at €2.25 compared with €1.44 a year earlier. That gives you a tangible link between current conditions and the full year target, rather than just a long term story.
When you line that against the €3.4b net income ambition, the remaining quarters effectively become a test of how resilient deposit margins, fee income and credit costs really are. It also ties into the existing catalysts around AI spend, fee growth and UniCredit collaboration, because hitting or missing this target will shape how credible those longer range efficiency and capital return plans look to investors watching execution closely.
How Analyst Assumptions Frame Commerzbank’s Targets
Analysts sketch a fairly clear earnings path for Commerzbank over the next few years, and it is worth lining that up with the bank’s own 2026 net income guidance. The external models assume that revenue grows by about 8.6% a year over the next three years, that profit margins step up from 24.1% today to 30.7% in three years, and that earnings rise from €2.9b today to €4.7b by 2029, with earnings per share moving to €4.77 if the planned share count reduction plays out.
Those projections also rest on a valuation reset. The consensus view works off Commerzbank trading on a P/E of 9.2x by 2029 compared with 14.2x today, which is below the current 11.3x for the GB Banks industry in the same report. For that profile to line up with analyst price targets, investors would also need to be comfortable with a discount rate of around 6.2% to 6.24%, as used in the Simply Wall St modelling.
On top of that, the scenario builds in a shrinking share base, with the stock expected to reduce its number of shares outstanding by roughly 7.0% a year over the next three years. That interacts directly with the capital return framework and the guided 100% payout ratio while CET1 stays above 13.5%, since buybacks and dividends together drive whether earnings growth translates into higher earnings per share or simply sustains the current level.
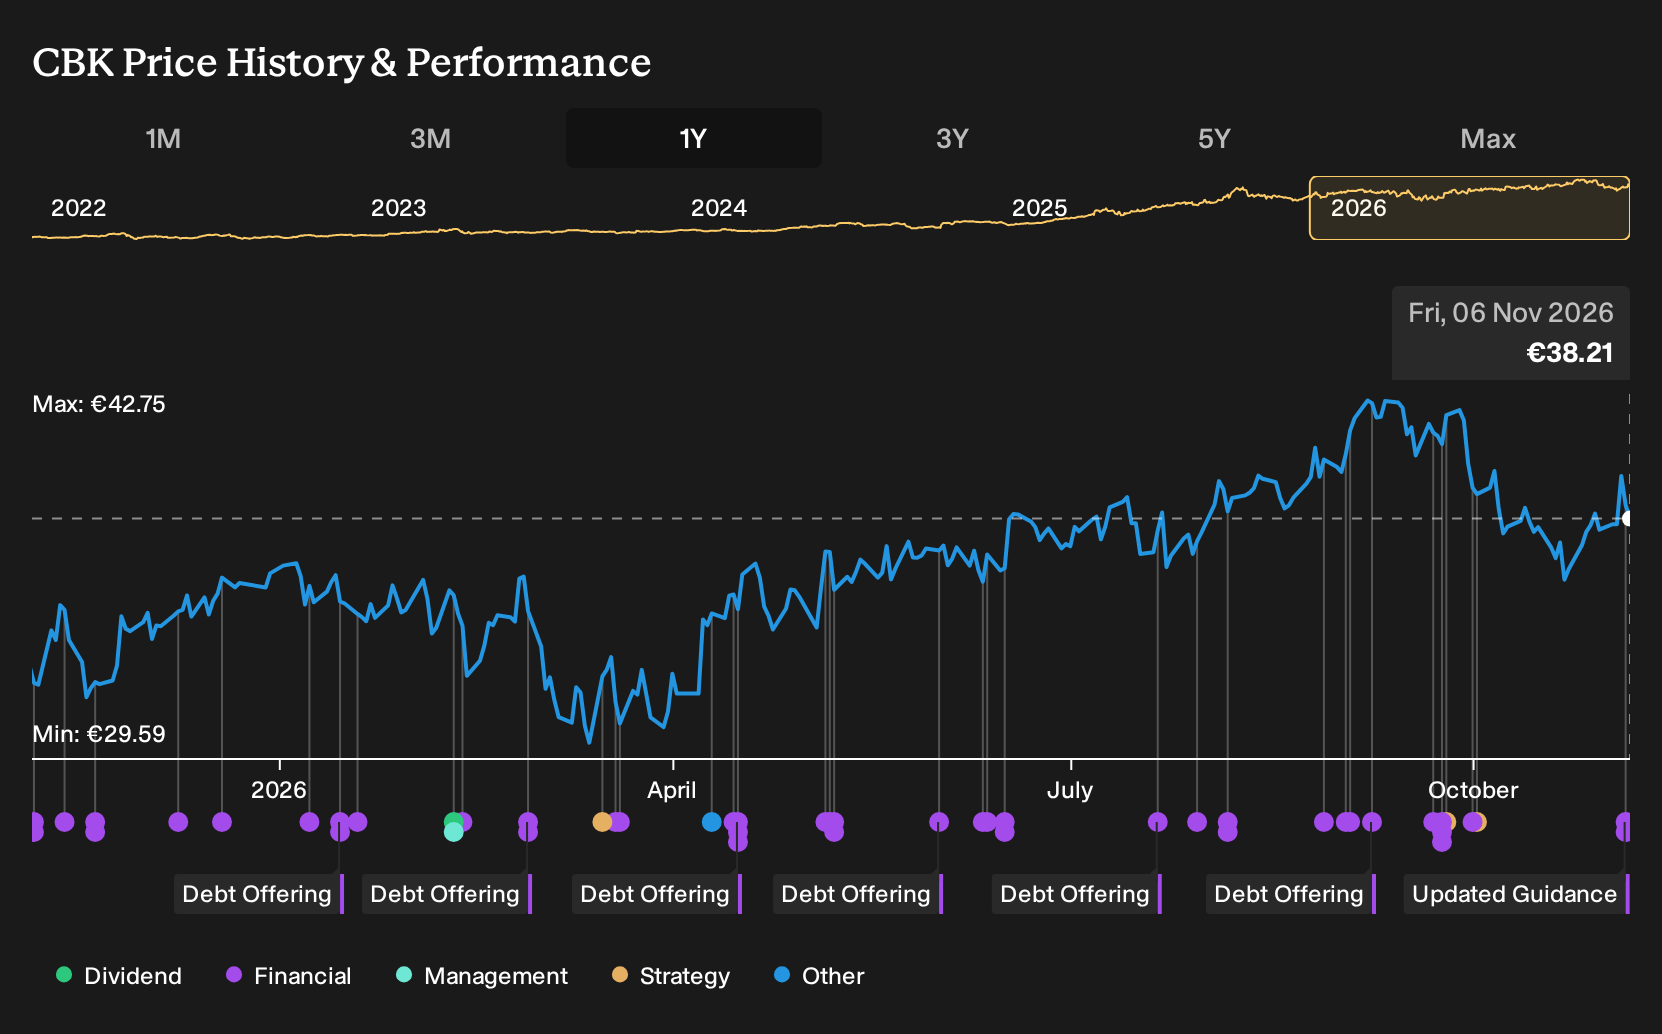
Valuation work in the consensus set ties these operating inputs to a concrete set of 2029 figures. The models assume that by that year revenues reach €15.2b and earnings land at €4.7b, again discounted using about a 6.2% rate. Against a current share price of €37.64, the analyst consensus target of €41.18, framed as about 8.6% higher in their material, points to a view that the market price already bakes in much of this earnings and payout story.
Commerzbank's narrative projects revenues of €15.2b and earnings of €4.7b by 2029, which lines up with analyst expectations of roughly 8.6% yearly revenue growth and an earnings increase of about €1.8b from current earnings of €2.9b.
Uncover how Commerzbank's fair value indicates an 8% potential upside to its current price, which could narrow quickly if sentiment catches up.
Exploring Other Perspectives
One place opinions really split is deposit pressure. The most bearish analysts already worked with tougher funding conditions and still pencilled in about €15.6b of revenue and €4.9b of earnings by 2029, using a P/E of 7.4x. You can treat today’s 2026 guidance as fresh input and weigh how far that pessimistic story might shift.
Explore 3 other Commerzbank fair value estimates, including one that suggests it could be worth just €41.18.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider aligning your choices with your own research and judgment.
- A great starting point for your Commerzbank research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Commerzbank. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Commerzbank's overall financial health at a glance.
Looking for more investment ideas beyond Commerzbank?
If you want to put Commerzbank in context, it helps to compare it with other businesses that share similar qualities around balance sheet strength, earnings quality and income potential. The Simply Wall St Screener offers several focused shortlists that can help you build that comparison set quickly, using consistent fundamentals rather than headlines or hype.
- If capital preservation is a priority, start with resilient businesses that screen with lower risk characteristics through the 209 resilient stocks with low risk scores.
- If you care most about financial strength and cleaner balance sheets, scan a list of solid balance sheet and fundamentals (192 results) that already filters for stronger fundamentals.
- If you want ideas where quality and valuation intersect, review a curated group of 581 high quality undiscovered gems that may not yet be widely followed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com