


EN
Penumbra (PEN), Why Is Its Latest Update Drawing Attention?
Penumbra (PEN) just posted its third quarter 2026 results, with sales of US$410.15 million and net income of US$42.28 million. These figures may influence how investors reassess the stock.
Penumbra shares trade at US$319.21, with recent 1-day and 90-day share price returns showing small declines that suggest some investors are reassessing risk after the mixed earnings line-up. Even so, the 1-year total shareholder return of 19.92% and 3-year total shareholder return of 75.93% indicate longer term holders have still seen strong compounding despite recent softer momentum.
Scan how Penumbra compares with other high‑growth but still under‑the‑radar opportunities by reviewing our hand picked 19 high quality undiscovered gems in a similar risk and return bracket.
Penumbra now trades below the average analyst target, even as cautious investors react to softer earnings. Is that discount a genuine opportunity, or a fair warning about the valuation risk ahead?
Most Popular Narrative: 12% Undervalued
Penumbra's most followed narrative pegs fair value at about $361.83, which sits above the last close of $319.21 and frames the current discount as a question of how durable its thrombectomy and embolization engines really are.
The embolization franchise, led by Ruby XL and Swift coils with strong middle meningeal artery embolization uptake and backed by a dedicated embolization sales team of more than 50 people, is emerging as a second pillar alongside thrombectomy. It can increasingly contribute to revenue diversification and operating margin leverage.
See why 5 investors see Penumbra as 12% undervalued.
Result: Fair Value of $361.83 (UNDERVALUED)
Still, the Penumbra story could shift quickly if the Boston Scientific integration proves more disruptive than expected, or if margin progress stalls after the Q1 2026 miss.
Find out about the key risks to this Penumbra narrative.
Another View: Penumbra Looks Expensive On Earnings
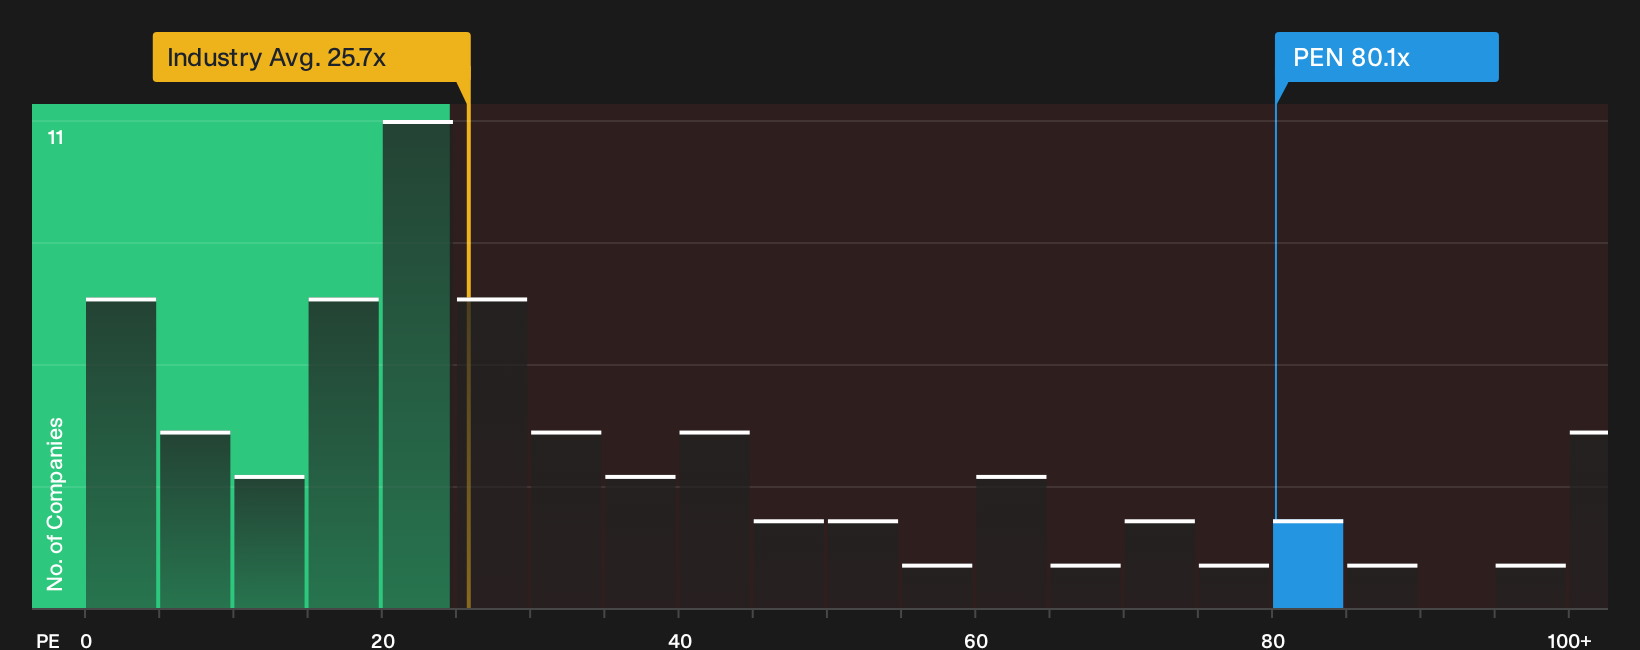
Switch the lens from that fair value narrative to simple earnings math and Penumbra looks pricey. The stock trades on a P/E of 80.1x, compared with about 25.7x for the wider US Medical Equipment group and 24.1x for close peers, while the fair ratio sits at 28.6x. That gap points to real valuation risk if sentiment cools or growth assumptions shift.
For a closer look at how this earnings multiple compares and what it could mean for future pricing pressure or upside, take a look at the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment on Penumbra is split, so it makes sense to look through the numbers yourself and stress test both bullish and cautious narratives. To see what optimistic investors are focusing on right now, review the 1 key reward.
Looking for more investment ideas beyond Penumbra?
If Penumbra is on your radar, broaden your opportunity set by lining it up against other stocks that share similar quality traits, income potential, or risk profiles.
- Target resilient balance sheets by scanning the list of solid balance sheet and fundamentals (25 results) that pair financial strength with fundamental support when markets get choppy.
- Hunt for mispriced quality and compare Penumbra with the 38 high quality undervalued stocks that combine strong cash generation with supportive valuations.
- Lock in potential income streams by sizing up the 7 dividend fortresses that aim for yields of 5% or more without losing sight of stability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com