


EN
Will Raised Earnings Guidance Change Hubbell (HUBB) Stock Narrative
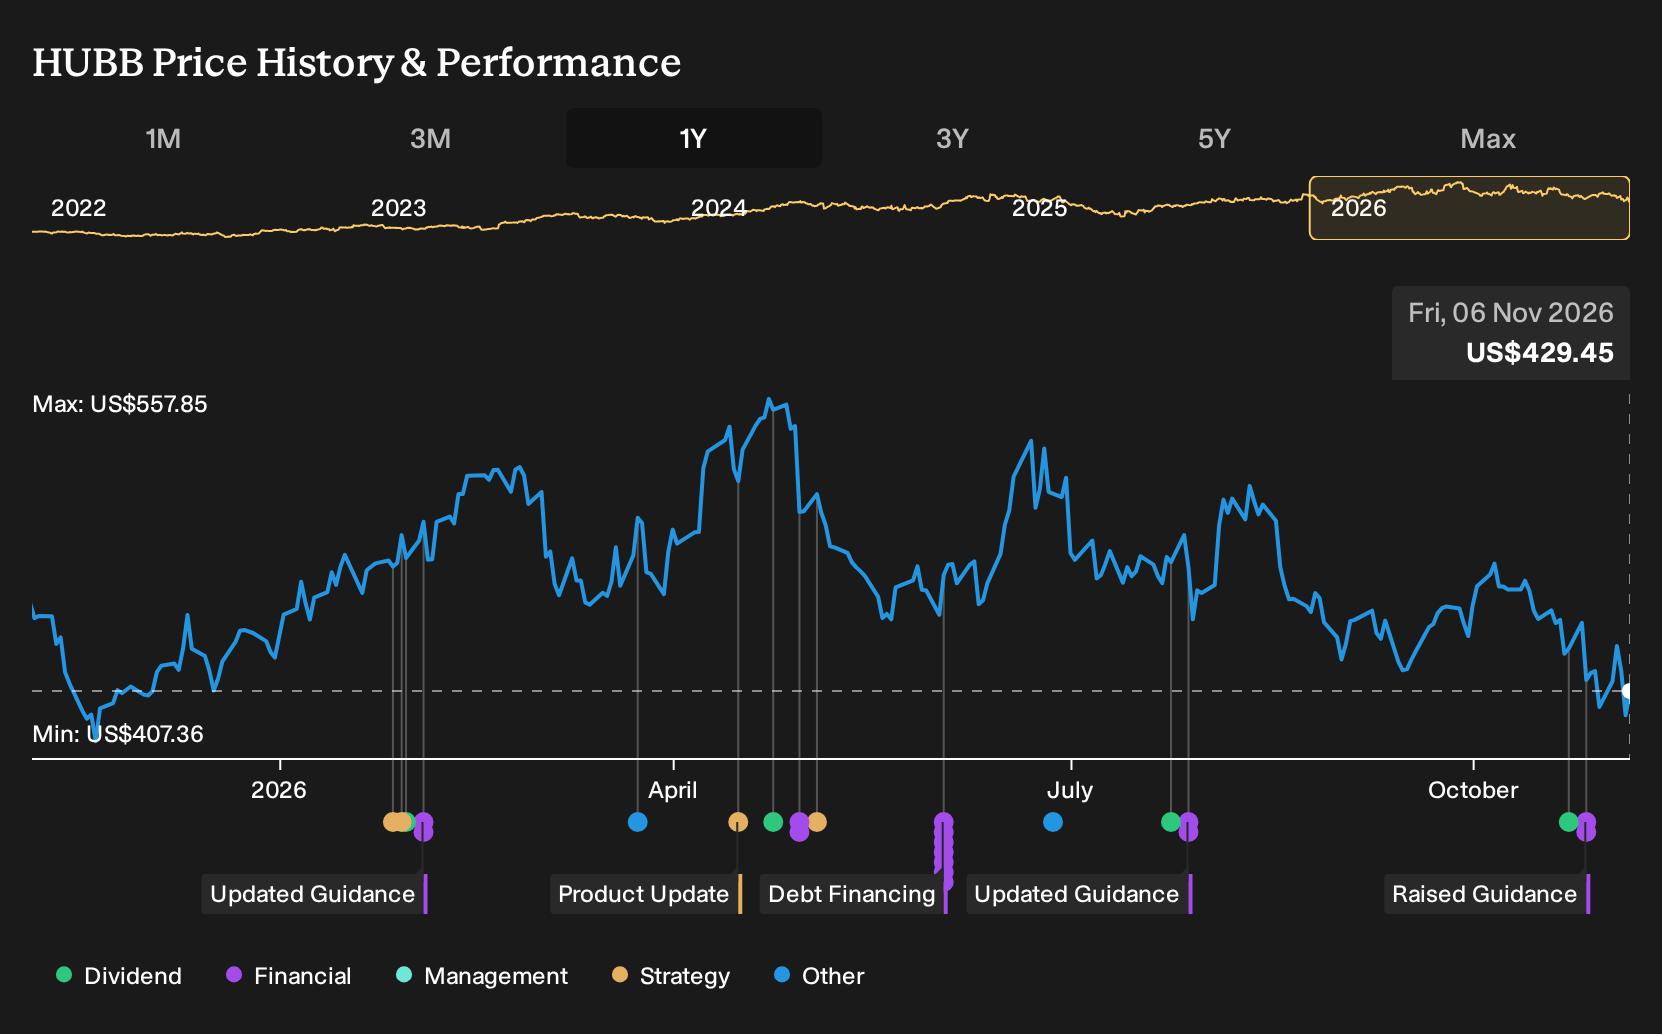
- Hubbell raised its full year 2026 outlook after posting third quarter sales of US$1,872.5 million and diluted EPS from continuing operations of US$4.94, with nine month sales of US$5,101 million and diluted EPS of US$12.86.
- The new 2026 guidance, which calls for total sales growth of 18% to 19% including 10% to 11% organic growth and GAAP diluted EPS of US$17.30 to US$17.50, gives investors a clearer line of sight into how grid related demand is feeding into Hubbell’s earnings profile.
- We will now look at how Hubbell’s raised full year earnings guidance could reshape the longer term investment narrative around grid spending.
Scan how Hubbell’s grid focused story compares with other potential beneficiaries of power infrastructure spending by reviewing the hand picked 41 power grid technology and infrastructure stocks in the same theme.
Hubbell Investment Narrative Recap
To own Hubbell, you need to be comfortable tying your thesis to long dated grid hardening, high voltage transmission and data center spending, and to the firm’s ability to convert that work into consistent earnings. The higher 2026 outlook sharpens that story but does not remove the key near term swing factor, which is execution on margins in Electrical Solutions and Grid Automation.
The biggest operational risk still sits on the balance sheet and in profitability. Debt linked to NSI and roughly US$170 million of extra 2026 interest expense keep pressure on cash generation and deleveraging. If grid related mix, pricing and cost controls do not improve net margins, raised guidance could prove demanding.
The raised 2026 guidance is the headline, because it explicitly ties expected 18% to 19% total sales growth, 10% to 11% organic, and GAAP EPS of US$17.30 to US$17.50 to the current order book. That directly connects Hubbell’s grid thesis, including projects stretching into 2027, with near term earnings delivery.
For you, the key question is whether that new range feels achievable given Q3 and nine month trends. Sales of US$1,872.5 million in the quarter and US$5,101 million year to date, along with diluted EPS from continuing operations of US$4.94 in Q3 and US$12.86 for nine months, show the firm operating at a scale where any stumble in integration, pricing or grid demand would quickly show up in earnings against that higher bar.
Hubbell's narrative projects US$8.4b revenue and US$1.3b earnings by 2029. This implies revenue growth of 8.6% per year and an earnings increase of about US$392 million from current earnings of US$907.6 million.
Uncover why Hubbell's fair value indicates a 27% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Some of the most bullish analysts frame Hubbell’s higher grid and data center exposure as a catalyst rather than a risk. Before this guidance raise, they were already penciling in roughly 11.1% annual revenue growth and about US$1.3b of earnings by 2029. You can treat today’s update as a fresh reason to compare those optimistic views with more cautious takes.
Explore 2 other Hubbell fair value estimates, including one that suggests as much as 27% upside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Hubbell research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Hubbell. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Hubbell's overall financial health at a glance.
Looking for more investment ideas beyond Hubbell?
If the Hubbell story has sharpened your thinking about grid spending and earnings quality, use that same lens to scan a wider bench of opportunities with the Simply Wall St Screener.
- If capital protection sits high on your list, start with companies that pair resilient operations with muted risk scores through the 31 resilient stocks with low risk scores.
- For investors who care most about quality and valuation working together, look through the 38 high quality undervalued stocks to see businesses combining stronger cash flows with steadier balance sheets.
- If the goal is to find underfollowed stories before they are widely talked about, filter for stronger fundamentals using the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com