


EN
How Lowered Guidance At Vistance Networks (VISN) Has Changed Its Investment Story
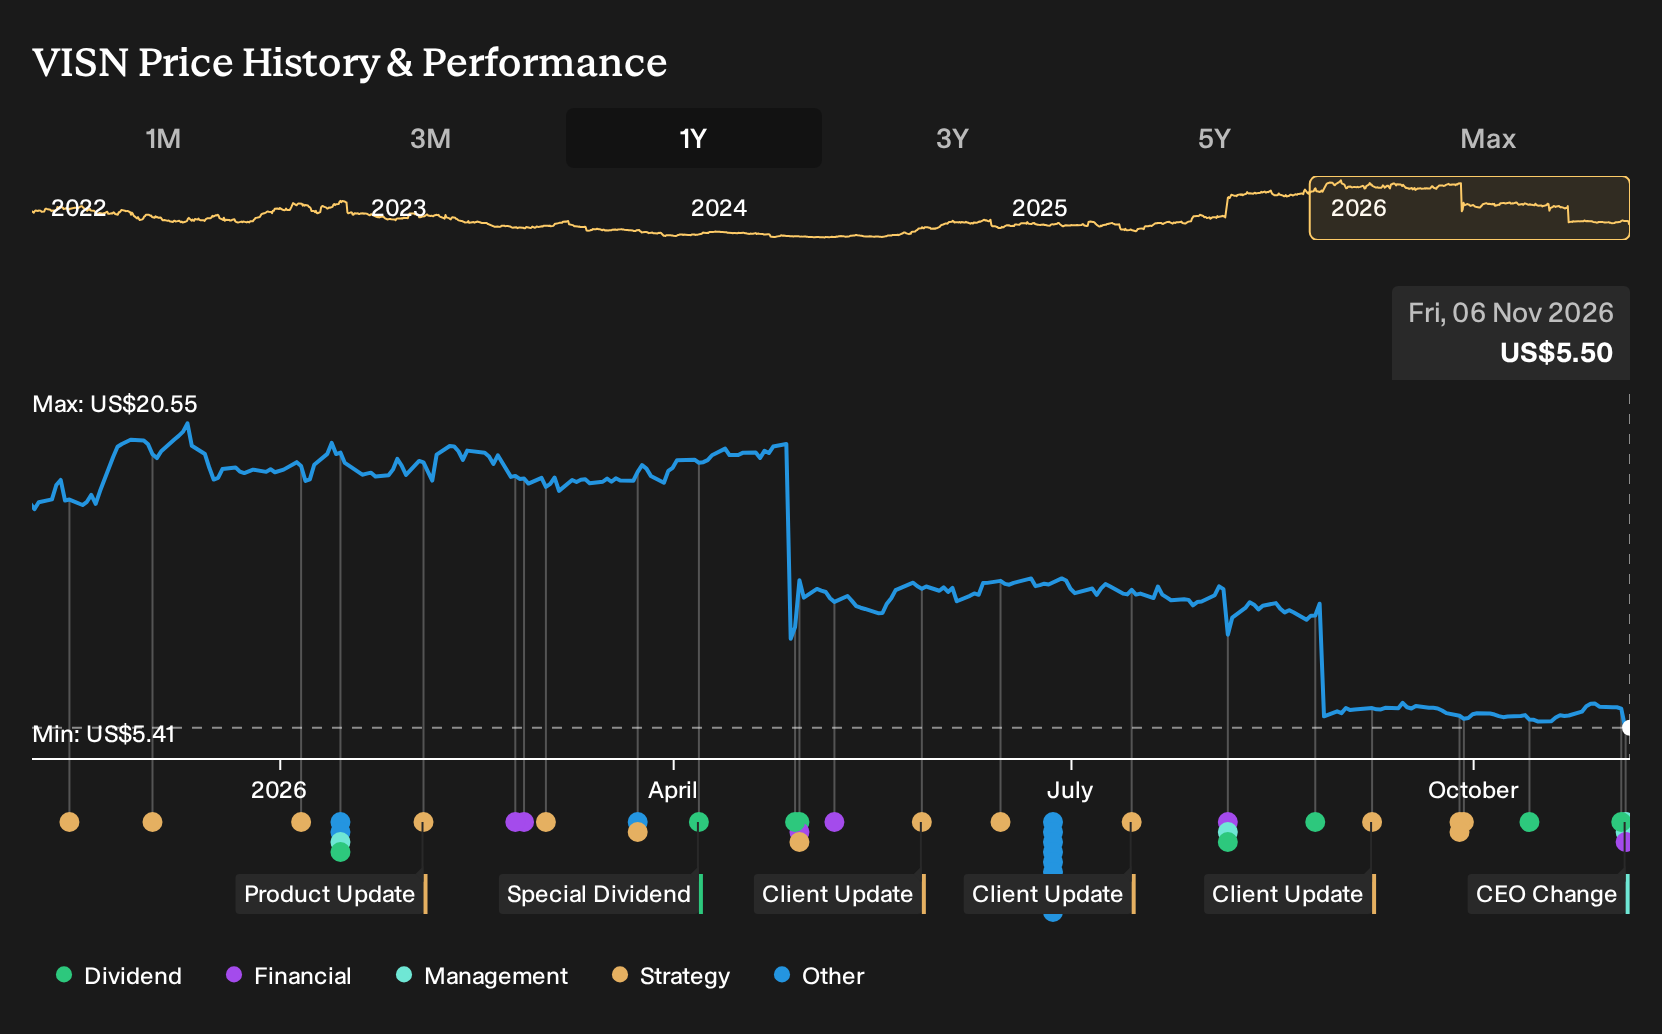
- Vistance Networks reported Q3 2026 sales of US$319.7 million and sharply higher net income, paired with an expanded share repurchase authorization to US$350 million and lower full year adjusted EBITDA guidance due to timing shifts in customer demand and memory pricing.
- The business has already returned roughly US$4b to investors in 2026 through special cash distributions and buybacks, while holding US$683 million in cash and carrying no debt, leaving Vistance Networks with substantial balance sheet flexibility as it concentrates on its Aurora Networks platform.
- Next, the focus turns to how Vistance Networks' heavier cash returns and reduced 2026 EBITDA guidance may reshape its longer term investment narrative.
Scan how Vistance Networks' capital returns and balance sheet stack up against a hand picked list of solid balance sheet and fundamentals (25 results) in similar cash rich situations.
Vistance Networks Investment Narrative Recap
To stay invested in Vistance Networks, you need to be comfortable with a focused Aurora Networks and RUCKUS story that leans on DOCSIS 4.0 upgrades, Wi Fi transitions and project based spending from a concentrated set of cable and enterprise customers. The near term swing factor is execution on Aurora deployments and backlog conversion, while the key risk is that operator rollouts or memory driven projects keep slipping.
The latest EBITDA guidance cut points to some timing pressure on that catalyst but does not fundamentally change it. What could matter more is whether current DOCSIS 4.0 wins, including at Comcast and Ziggo, turn into steady, repeatable volume as legacy HFC demand tapers.
The CEO transition announcement is the most important development around this news. Chuck Treadway is set to step down as CEO and President on February 1, 2027, after leading the transformation that repaid all debt, redeemed preferred equity and reshaped Vistance Networks into a pure network solutions business centered on Aurora Networks.
The board has already launched a search for the next chief executive, supported by an external firm, which keeps succession on a defined path. For you, the watchpoints are continuity on capital allocation after roughly US$4b of returns in 2026, the priority given to DOCSIS 4.0 and Aurora investment, and how a new leader manages customer concentration and lumpier project demand.
Vistance Networks' current analyst narrative points to revenues of US$2.4b and earnings of US$89.6 million by 2029, based on a projected 7.6% yearly revenue growth rate and a decline in earnings of about US$165.8 million from US$255.4 million today.
Uncover why Vistance Networks' fair value indicates a 321% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts frame the CEO transition and heavy cash returns at Vistance Networks as a potential contract win catalyst, not a risk. Before this news, the bullish camp was already modeling roughly US$2.5b of revenue and US$79.4 million of earnings by 2029. That is a very different storyline. It shows how sharply opinion can split and why it helps to compare several viewpoints that have not yet reflected this latest update.
Explore 5 other Vistance Networks fair value estimates, including one that suggests potential upside of up to 355% from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider conducting your own research.
- A great starting point for your Vistance Networks research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Vistance Networks. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to review Vistance Networks' overall financial health at a glance.
Looking for more investment ideas beyond Vistance Networks?
If you like the capital return profile and balance sheet strength at Vistance Networks but want a broader watchlist, the Simply Wall St Screener can help you scan for other opportunities that fit your own risk and income preferences.
- If capital preservation and steadier profiles matter most to you, start with a 31 resilient stocks with low risk scores that could help anchor your portfolio.
- If you want potential mispricings with strong fundamentals, sort through a curated 19 high quality undiscovered gems that may not yet be widely followed.
- If reliable cash flows and income are a priority, filter for a focused 7 dividend fortresses that puts yield and resilience front and center.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com