


EN
Profit Turnaround Might Change The Case For Investing In Quaker Chemical Stock (KWR)
- Quaker Chemical reported third quarter 2026 sales of US$544.55 million with net income of US$29.98 million, and nine month 2026 sales of US$1.56b with net income of US$76.48 million after a loss in the prior year period.
- The company also completed a share repurchase of 167,072 shares for US$23.92 million, a modest reduction in share count that slightly concentrates future earnings among remaining investors.
- Next, the focus turns to how Quaker Chemical's shift from a year ago loss to year to date profit shapes the existing investment narrative.
Scan how Quaker Chemical's earnings swing compares with peers by lining it up against 38 high quality undervalued stocks that combine solid fundamentals with compressed expectations.
Quaker Chemical Investment Narrative Recap
To own Quaker Chemical, you need to be comfortable with a specialty chemicals business that is leaning heavily on volume growth in Asia Pacific, higher value Fluid Intelligence offerings, and a multi year cost transformation to support earnings. The swing from a prior year loss to a nine month profit shows the model can generate income, although Q3 profit stayed roughly flat year on year.
The key near term catalyst remains execution on cost savings and network optimization, which are aimed at lifting EBITDA margins. The biggest near term risk is that raw material and logistics costs, especially for crude linked inputs and shipping routes, stay elevated and keep Americas margins under pressure. The latest quarter does not fundamentally change either side of that equation.
The most relevant update for that thesis is the third quarter 2026 report itself. Sales reached US$544.55 million for the quarter and US$1.56b for the nine months, with net income of US$29.98 million in Q3 and US$76.48 million year to date after a loss in the prior period. That earnings profile gives you a cleaner base to judge the cost program after the earlier one off loss.
In the short term, investors watching Quaker Chemical are likely to focus on how this profitability run rate interacts with the planned US$20m to US$30m structural savings, Asia Pacific capacity from Zhangjiagang, and any lingering Americas cost drag. With debt not well covered by operating cash flow and the dividend not fully backed by free cash, consistent execution on margins and cash generation remains the hinge for the current catalysts.
Quaker Chemical's analyst narrative points to forecast revenue of US$2.3b and expected earnings of US$215.8 million by 2029, based on an assumed 4.6% yearly revenue growth rate and a move in profit from US$97.5 million today to the US$215.8 million consensus, which represents roughly a 2.2x earnings increase.
Uncover why Quaker Chemical's fair value indicates a 28% potential upside to its current price that may not last much longer.
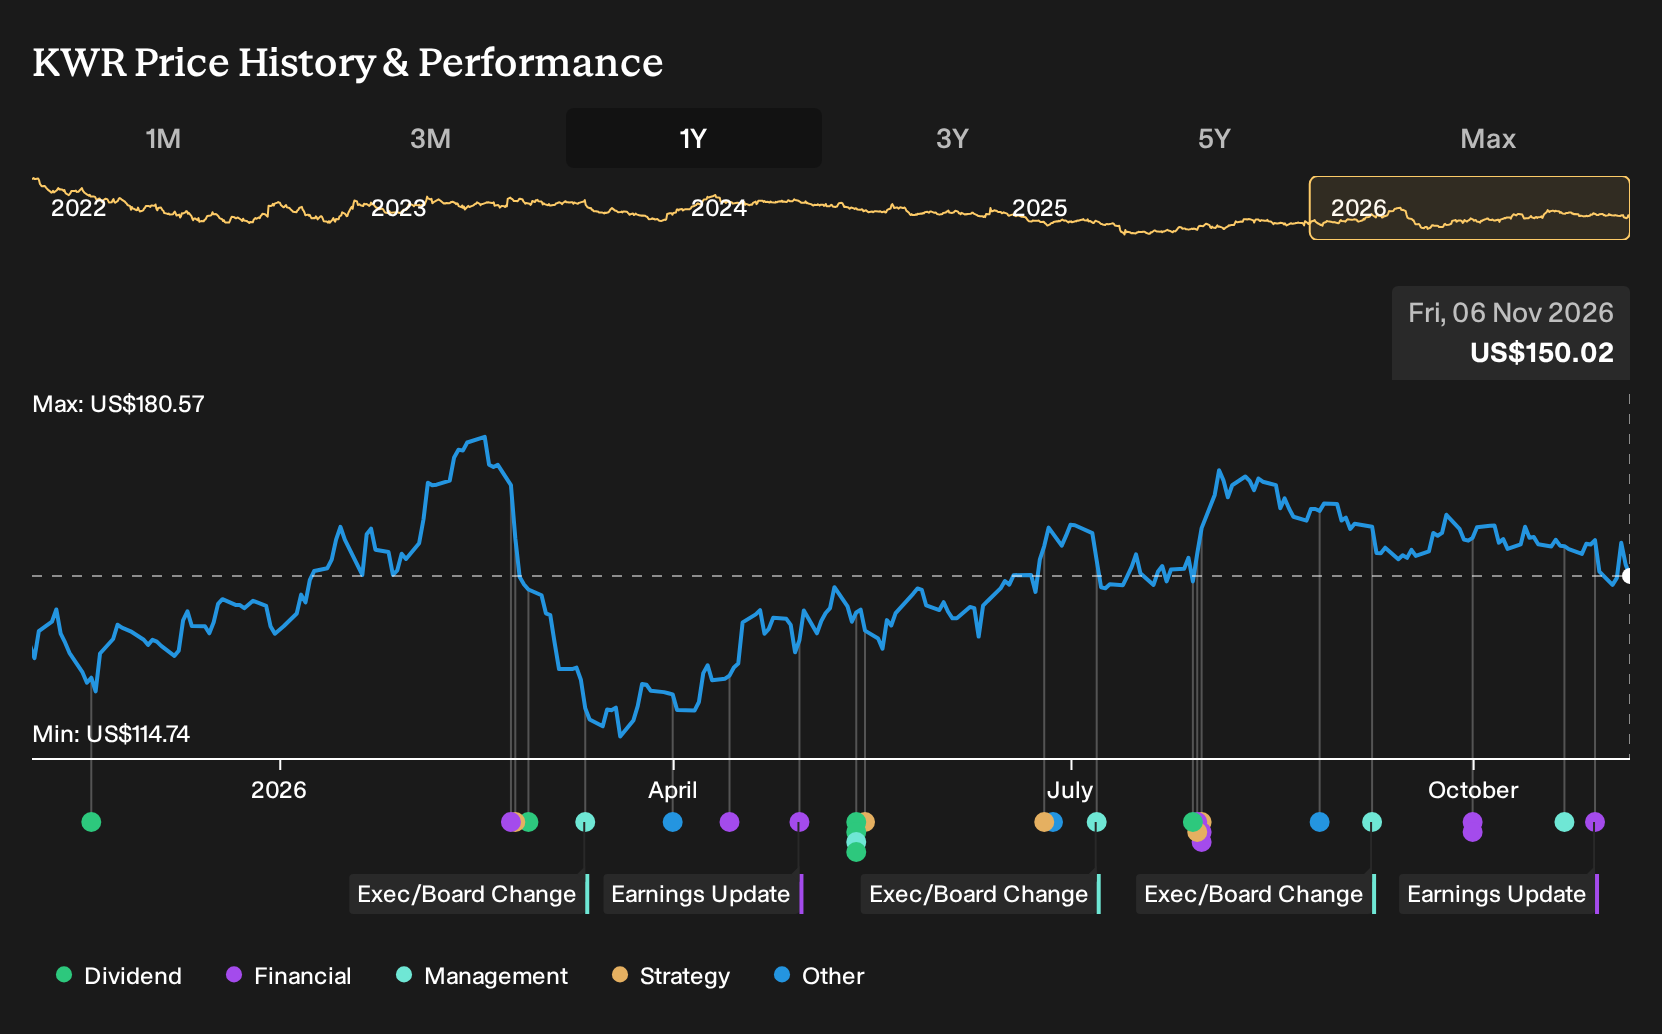
Exploring Other Perspectives
Some of the most optimistic analysts were already leaning hard into the Zhangjiagang expansion as a key upside catalyst for Quaker Chemical, assuming roughly US$2.3b of revenue and about US$216.2 million of earnings by 2029. You now have fresh earnings and a completed buyback that those forecasts did not yet factor in, so it is worth comparing several viewpoints before deciding which story you find most convincing.
Explore 2 other Quaker Chemical fair value estimates, including one that suggests there could be as much as 33% potential upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis and judgment.
- A great starting point for your Quaker Chemical research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Quaker Chemical. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Quaker Chemical's overall financial health at a glance.
Looking for more investment ideas beyond Quaker Chemical?
If you want to stress test your thesis on Quaker Chemical against a wider opportunity set, the Simply Wall St Screener can help you line up other businesses with similar or better fundamentals in a few clicks.
- If capital preservation sits high on your priority list, start by scanning a set of 31 resilient stocks with low risk scores that score well on resilience and downside protection.
- For investors who want financial strength front and center, filter the market using a list of solid balance sheet and fundamentals (25 results) so you focus on companies with healthier leverage and liquidity.
- If you would rather hunt for lesser known opportunities with cleaner fundamentals, cast a wider net with a 19 high quality undiscovered gems that highlights quality businesses still under the radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com