


EN
How Investors May Respond To Cooper (COO) CEO Exit And Board Reshuffle
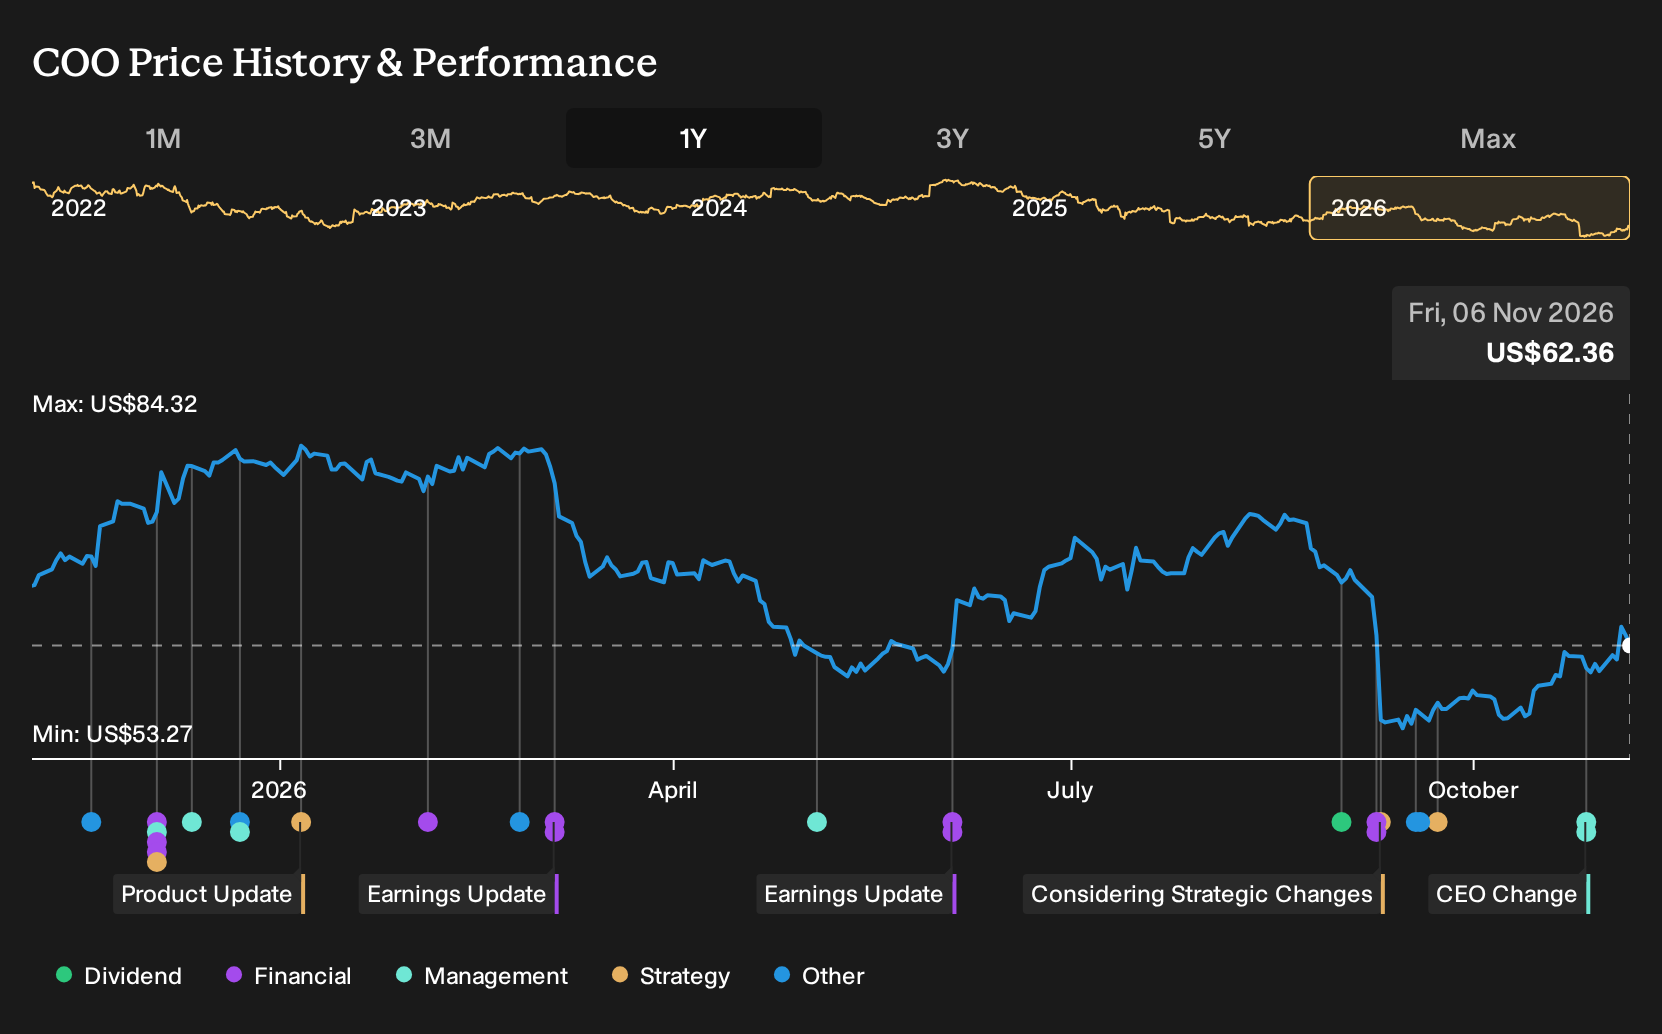
- Cooper Companies reported that long serving CEO and President Albert White III stepped down from both roles and the Board on 27 October 2026. Director Walter Rosebrough Jr became Executive Chair and took day to day operational oversight while a Board led search for a permanent chief executive progresses.
- The leadership reshuffle, including Rosebrough’s expanded role and further Board changes, comes as Cooper Companies continues to work through product mix shifts, legal issues at CooperSurgical, and cost discipline efforts that many investors already view as central to its longer term earnings power.
- We will now look at how Cooper Companies investment narrative could be affected by Rosebrough taking interim operational control during the CEO search.
Scan how other listed healthcare groups are reshaping leadership and product portfolios by reviewing the hand picked 35 healthcare AI stocks that could also be reacting to similar boardroom and technology shifts.
Cooper Companies Investment Narrative Recap
For Cooper Companies, the core belief is that premium daily silicone hydrogel and myopia management products can gradually reshape the mix and support healthier margins, while CooperSurgical fertility offerings add a second leg of growth. Walt Rosebrough stepping in as Executive Chair with operational oversight does not change these product-level goals, but it concentrates execution risk at the top.
The key short-term catalyst remains stabilizing CooperSurgical after the embryo culture media recall and turning improving contact lens mix into cleaner reported revenue. The biggest risk remains that Asia Pacific softness, legal costs, and legacy hydrogel rationalization continue to blunt that premium lens and fertility story despite leadership changes.
The most relevant recent announcement is Rosebrough taking direct operational oversight as Executive Chair while the Board and Russell Reynolds run the CEO search. This matters for you because the main levers analysts focus on (premium lens mix, fertility volume, cost discipline, and capital deployment) now run through an interim structure that leans heavily on one individual’s track record.
Rosebrough’s background at STERIS and Hill Rom, plus his current governance roles, gives Cooper Companies access to deep medical device experience while it works through product, legal, and portfolio questions. For catalysts such as MyDay and MiSight expansion or potential changes around CooperSurgical, your attention likely shifts to how quickly this Executive Chair model converts Board-level intent into clean, repeatable operational execution.
Cooper Companies' narrative projects US$4.9b revenue and US$779.8m earnings by 2029. This is based on an assumed 4.8% yearly revenue growth and an earnings increase of about US$209.5m from US$570.3m today.
Uncover how Cooper Companies' fair value indicates a 6% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts frame the real catalyst for Cooper Companies as margin expansion, not just premium lens volume. Before this CEO shake up, the bullish camp was modeling revenue of about US$4.9b and earnings near US$918.6m by 2029. You can now ask whether this leadership change nudges those expectations up or down.
Explore 5 other Cooper Companies fair value estimates, including one that suggests as much as 105% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis carefully.
- A great starting point for your Cooper Companies research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Cooper Companies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cooper Companies' overall financial health at a glance.
Looking for more Cooper Companies investment ideas?
If this Cooper Companies leadership reset has you rethinking your watchlist, it can help to line it up against other opportunities with different risk and income profiles.
- For investors who want a focus on quality at a potentially discounted entry point, scan a curated 38 high quality undervalued stocks that pair fundamentals with more modest pricing.
- If capital preservation matters as much as upside for you, filter for resilience with a 31 resilient stocks with low risk scores that screens for sturdier balance sheets and business profiles.
- When you want to back sturdier finances first and refine your picks from there, start with a list of solid balance sheet and fundamentals (25 results) that already clears basic strength and fundamentals checks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com