


EN
How Investors May Respond To Amgen (AMGN) Earnings Beat
- Amgen reported third quarter 2026 revenue of US$10.365b and net income of US$3.864b, alongside fresh real world data showing Repatha cut heart attack risk by 20% versus ezetimibe in more than 544,000 adults with atherosclerotic cardiovascular disease and prior statin use.
- The combination of higher earnings, expanded regulatory approvals for Repatha in the U.S. and Europe, and advancing late stage assets such as dazodalibep highlights how Amgen is leaning on established cash generators while building out future cardiometabolic and autoimmune franchises.
- This article examines how Amgen's broader investment narrative is affected by the strong Q3 earnings beat and the large Repatha outcomes study.
Scan how Amgen's cardiometabolic push compares with other large-cap healthcare cash generators by reviewing the handpicked list of solid balance sheet and fundamentals (25 results) in this space.
Amgen Investment Narrative Recap
An investor in Amgen needs to believe that the cardiometabolic, oncology and rare disease portfolios can keep offsetting pricing pressure and biosimilar headwinds. The Q3 2026 report, with US$10.365b in revenue and US$3.864b in net income, reinforces that the current mix of therapies is supporting earnings and cash generation today.
The short term catalyst is whether Repatha and other growth drivers can sustain volume and margin support as older drugs face competition. The real world Repatha data strengthens that case. The biggest near term risk still comes from drug pricing pressure and loss of exclusivity, which the latest results do not remove.
The fresh real world evidence for Repatha is the most relevant announcement. A 20% lower risk of fatal or nonfatal heart attacks versus ezetimibe across more than 544,000 adults gives prescribers and payers practical data on outcomes, not just LDL lowering. That is important for the cardiometabolic story investors are already watching.
This evidence, combined with broader U.S. and European label expansions over 2025 and 2026, could support Amgen as it builds a fuller cardiometabolic franchise around Repatha, olpasiran and MariTide. Execution risk does not disappear, especially with drug pricing scrutiny and biosimilar competition, but the Repatha dataset narrows one key uncertainty on clinical impact.
Amgen's current earnings of US$9.4b are set against analyst expectations for revenue to grow at 4.0% per year, with consensus pointing to US$43.7b in revenue and US$11.0b in earnings by 2029. This implies an earnings increase of about US$1.6b from today.
Discover why Amgen's fair value indicates a 12% potential downside to its current price, a premium that may not be sustained.
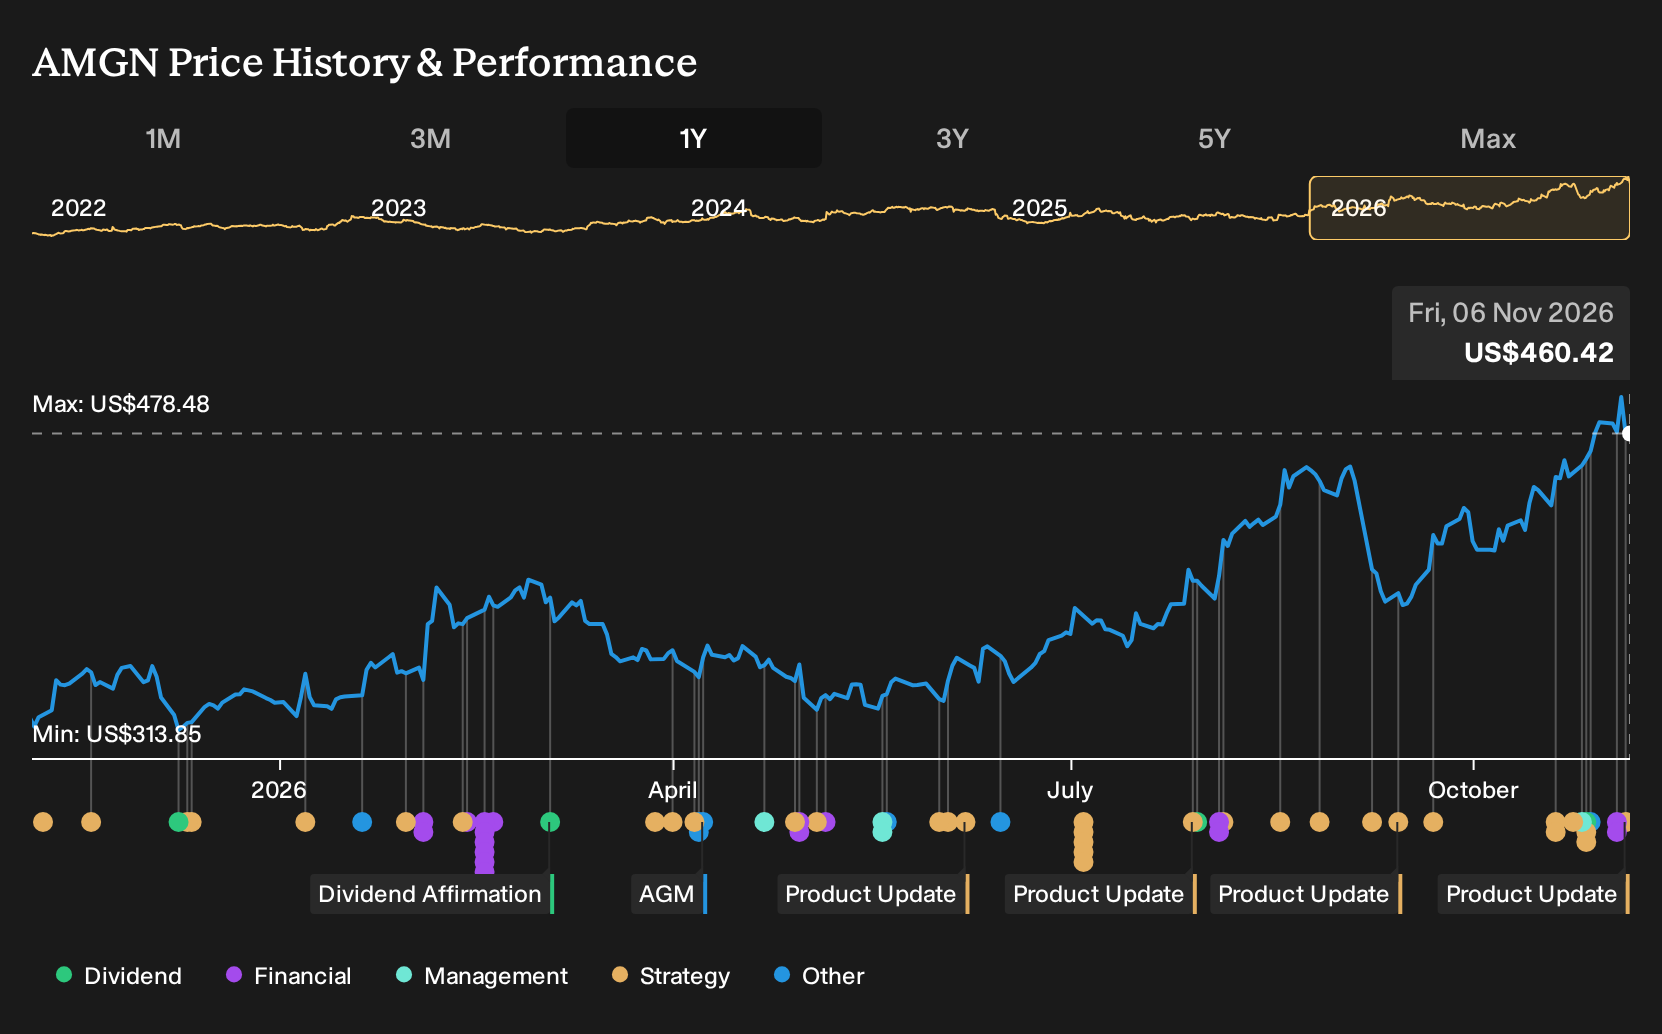
Exploring Other Perspectives
Some of the lowest Amgen forecasts leaned hard into pricing and biosimilar risk. Those analysts were only pencilling in about US$39.3b of revenue and US$9.0b of earnings by 2029, versus the US$43.7b and US$11.0b consensus. The new Repatha outcomes data and Q3 beat may nudge that cautious story, so it can be useful to explore several viewpoints before deciding how you feel.
Explore 5 other Amgen fair value estimates, including one that suggests as much as 22% downside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Amgen research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Amgen. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Amgen's overall financial health at a glance.
Looking For More Investment Ideas Beyond Amgen?
Once you have a view on Amgen, it can help to widen the lens and see how other businesses with different risk and income profiles line up side by side in the Simply Wall St Screener.
- If you want potential value opportunities with quality fundamentals, scan the market using the 38 high quality undervalued stocks.
- For investors who care most about income resilience, focus on companies in the 7 dividend fortresses to see where yields and balance sheets line up.
- If capital protection is front of mind, concentrate on the 31 resilient stocks with low risk scores and compare how their risk scores stack up against your current holdings.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com