


EN
Nova (NVDA) Could Be 39% Below Fair Value On Record Q3 Results
Nova (NasdaqGS:NVMI) shook up expectations this week after record third quarter 2026 results topped guidance and arrived alongside new fourth quarter revenue and earnings targets that reflect management’s confidence despite ongoing supply chain constraints.
Nova’s latest earnings release landed alongside a sharp move in the share price, with a 1 day share price return of 11.73% that partly offsets a 30 day share price decline of 11.28% and a 90 day fall of 18.61%, leaving the stock at $313.18. Over a longer horizon, the total shareholder return of 1.82% over the past year and a very large 3 year total shareholder return of 180.25% suggest the recent pullback follows a much stronger multi year run. Investors may see this as a reset in expectations as they weigh record results against supply chain pressures and sector wide risk concerns.
Scan beyond Nova and see how other metrology and chip equipment plays stack up using our curated list of 19 high quality undiscovered gems.
Nova just printed record numbers while the share price only partially recovered from a recent slide. Is this move really about the business, or is sentiment doing most of the work as valuation comes into focus next?
Most Popular Narrative: 39% Undervalued
Against Nova’s last close at $313.18, the most followed narrative pins fair value at $515.13 using a 14.71% discount rate, which frames the recent pullback as a potential mismatch between share price and long term expectations.
The accelerating complexity of semiconductor devices driven by AI workloads, larger die sizes, advanced nodes and heterogeneous packaging continues to fuel demand for Nova’s advanced metrology solutions across logic, foundry and memory, which can support higher revenue and earnings as customers expand metrology intensity.
Ongoing global investments in semiconductor manufacturing capacity, including new fabs and regional diversification, are broadening Nova’s customer base and spreading exposure across more geographies, which can support a more resilient revenue mix and smoother operating margins over time.
See why 23 investors see Nova as 39% undervalued.
Result: Fair Value of $515.13 (UNDERVALUED)
Still, high exposure to China and pressure from local metrology rivals, along with sector wide multiple compression, could quickly challenge this thesis that the stock is 39% undervalued.
Find out about the key risks to this Nova narrative.
Another View On Nova’s Valuation
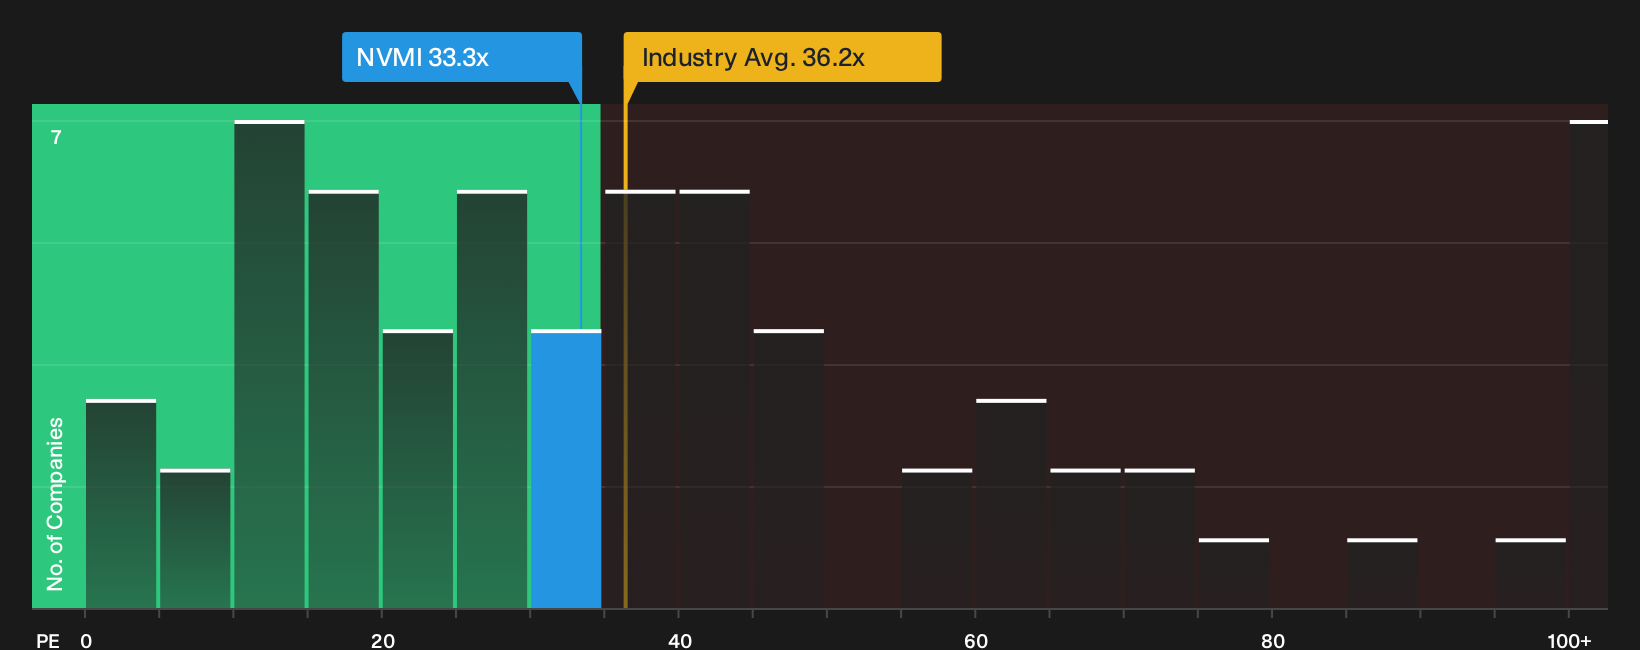
That 39% undervalued narrative leans heavily on long term earnings forecasts. A simple P/E check paints a more cautious picture. Nova trades at 33.3x earnings, below the US Semiconductor industry on 36.2x and just under peers at 33.9x, yet above a fair ratio of 29.9x. That mix hints at some valuation risk if sentiment cools.
The market already prices Nova at a premium to its own fair ratio even though it sits slightly cheaper than sector and peer averages. As a result, anyone leaning on the underpriced story needs to decide which anchor matters more for them. See what the numbers say about this price — find out in our valuation breakdown.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Nova for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 38 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on Nova is split, with record figures and supply chain concerns pulling in opposite directions. It may be useful to move quickly and stress test the story yourself using the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Nova?
If Nova has you thinking harder about price, risk, and quality, do not stop here. The next move often comes from a stock you have not checked yet.
- Target potential mispricings by scanning a focused set of quality ideas using the 38 high quality undervalued stocks.
- Strengthen capital preservation by reviewing a 31 resilient stocks with low risk scores that filters for businesses with more resilient profiles when conditions change.
- Upgrade portfolio quality by running through a list of solid balance sheet and fundamentals (25 results) that highlights companies with sturdier finances backing their earnings story.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com