


EN
3 High Quality Dividend Stocks For Higher Rates and Passive Income
Interest rates are climbing, inflation pressures are sticky, and the Federal Reserve is signalling that higher borrowing costs could stick around for years. That mix can unsettle investors, yet it also shines a spotlight on dividend stocks that already pay shareholders to wait. This article examines how that backdrop connects to three high quality dividend stocks from our screener, and how their exposure to the latest Fed narrative may factor into your portfolio decisions.
The three dividend ideas covered below are only a sample, and the full screen surfaced 16 more U.S. companies with similar income potential and balance sheet quality that are not discussed in this article.
To see the complete list and start narrowing it down to your own highest conviction income plays, go straight to the High-Quality Dividend Stocks screener
Sun Communities (SUI)
Sun Communities fits this high quality dividend list as a large U.S. REIT focused on recurring site rents from manufactured housing and RV communities. This can appeal if you want income backed by long term tenant relationships rather than short term trading swings.
Sun Communities is a U.S. based REIT that owns and operates manufactured housing and RV communities. It generates about US$1.2b from manufactured home sites and US$675 million from RV resorts, with a market value around US$14.6b.
Ongoing structural U.S. housing affordability pressures and limited new manufactured housing supply, combined with occupancy above 98% in Sun Communities’ manufactured housing portfolio, support the potential for sustained rent growth and stable site revenue that can feed into long term NOI and earnings.
The real test for Sun Communities is how one unresolved cost and funding pressure shapes cash flow resilience if rates stay elevated longer than expected.
If that funding squeeze is what you keep circling back to, read the full narrative for Sun Communities to see how Sun Communities could still compound through an extended high rate cycle.
Gold.com (GOLD)
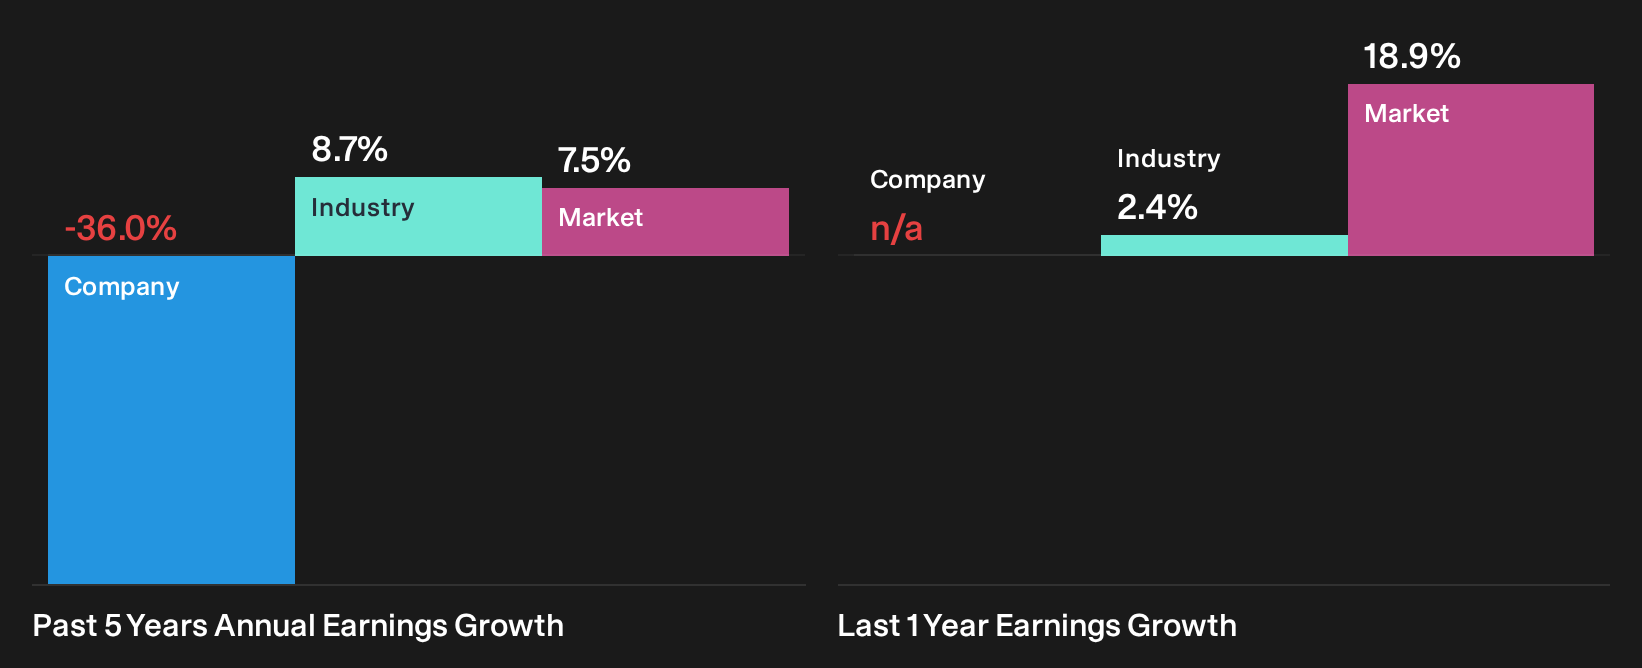
Gold.com brings a different flavour to this dividend shortlist, pairing a precious metals platform with shareholder payouts that can add income and diversification for investors who want exposure beyond traditional equity and real estate cash generators.
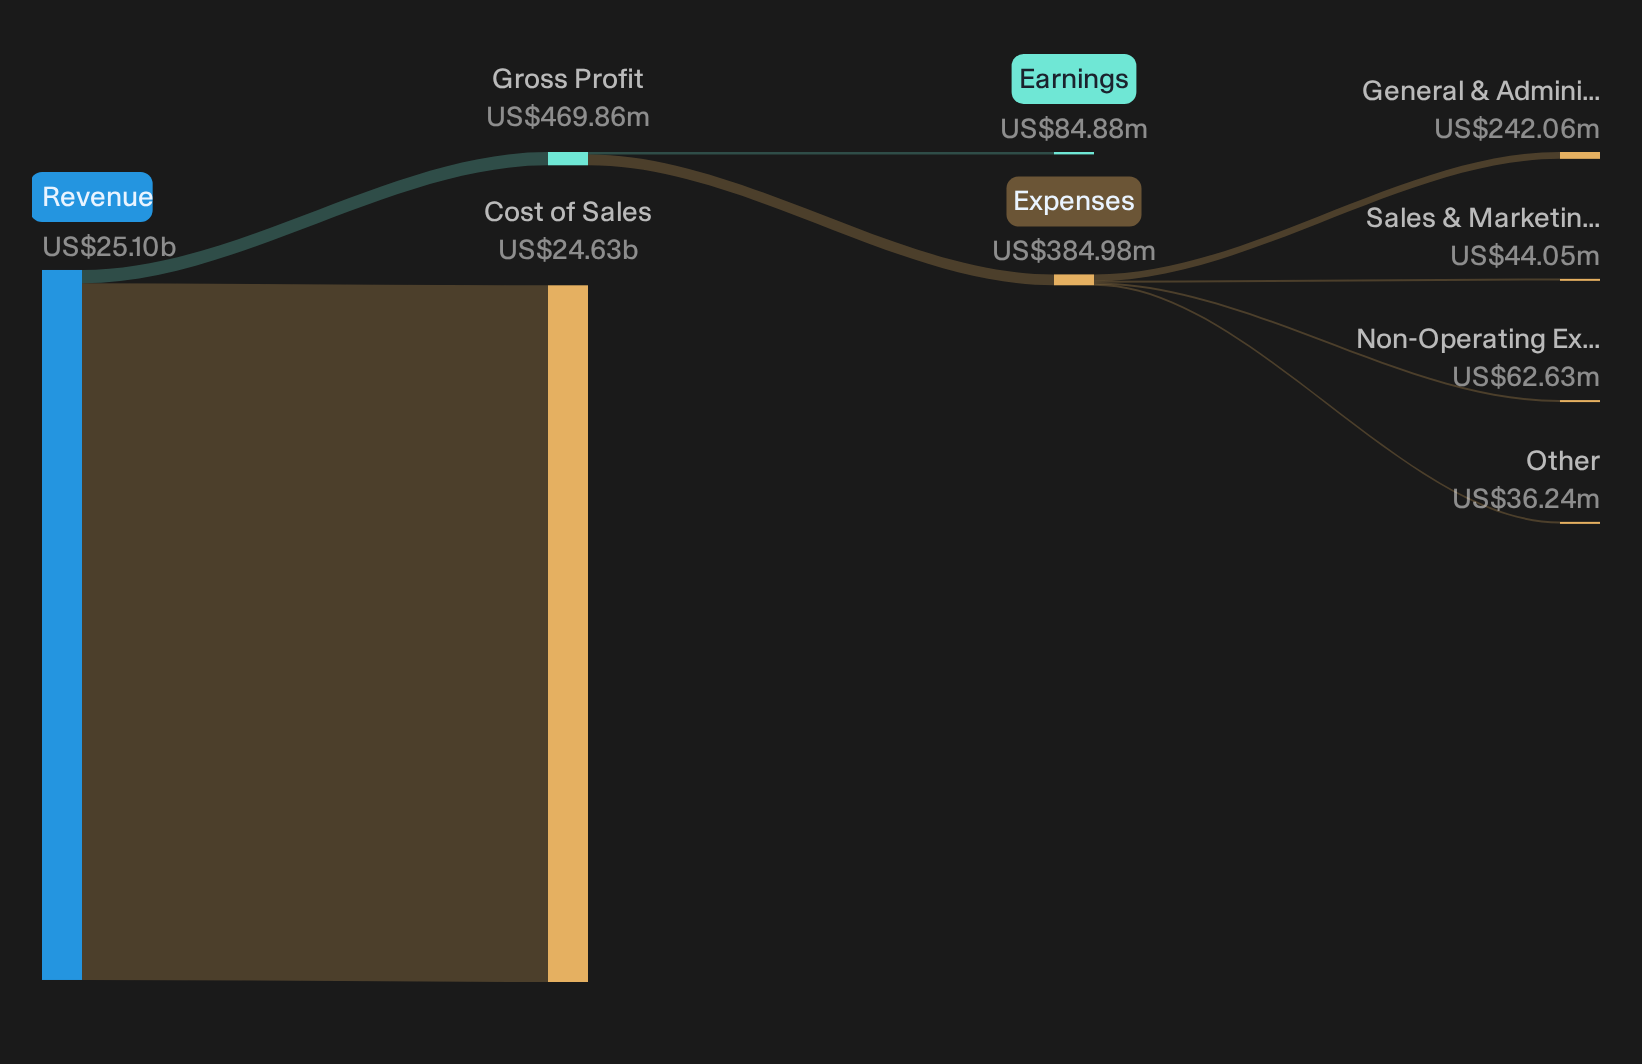
Gold.com operates a global precious metals platform spanning wholesale bullion distribution, direct-to-consumer sales, and secured lending against bullion and collectibles, with a market value around US$1.1b.
The recent string of acquisitions that have been folded into Gold.com, including Sunshine Mint, SGI, Pinehurst, AMS, Monex and others, has already taken reported FY2026 revenue to $25.5b and materially lifted production capacity. As integration, cross selling and operational efficiencies develop across this larger platform, these changes can affect net margins and earnings power.
What really matters from here is how one quiet shift in the earnings mix reshapes both margin resilience and the reliability of future dividends.
That shift is exactly what full narrative for Gold.com unpacks, showing how Gold.com’s enlarged platform could reshape earnings quality, capital returns, and dividend headroom.
Gaming and Leisure Properties (GLPI)
Gaming and Leisure Properties brings a pure-play, triple-net casino real estate angle to the High-Quality Dividend Stocks screener, offering lease-backed income exposure that is designed to feel more like long term rent collection than short term trading.
Gaming and Leisure Properties is a US based REIT that acquires and leases gaming real estate on triple net terms, generating about US$1.7b from investments in real estate in the United States, with a market value near US$11.6b.
Income focused investors often look at Gaming and Leisure Properties when they want a steadier rent check profile tied to long leases, and this higher for longer rate backdrop puts more attention on how durable that payout really is.
The ongoing development and deployment of committed capital into projects such as Bally’s Chicago, Penn’s Aurora, Bally’s Lincoln and Live! Virginia is now backed by about US$1.8b of future funding expected to be deployed by year end 2027. Significant financial exposure to Bally's, a tenant with a downgraded credit profile and ongoing cash flow and leverage concerns, remains a concentration risk for Gaming and Leisure Properties, and any further weakening in Bally's credit quality could disrupt rent collections, reduce real estate income and put pressure on net margins.
What happens if one quiet shift in tenant health subtly alters how much of that high headline yield ultimately flows through to your pocket?
If you want to see how that tenant risk could be masking upside, read the full narrative for Gaming and Leisure Properties to see where Gaming and Leisure Properties’ payout profile could be heading.

Seeking Fresh Alternatives Before They Fly
Fresh ideas move first. By the time every screen lights up with the same tickers, the cleanest entry points are often gone. Scan what others miss while it still matters and act now.
- Hunt for fast movers with real balance sheet strength using the 19 high quality undiscovered gems before the crowd focuses on the next breakout wave.
- Position for the next leg of the energy transition with the curated 17 nuclear energy infrastructure stocks while many investors are still looking the other way.
- Explore structural demand for critical metals through the focused 16 top copper producer stocks while quality producers remain under the radar for now.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com