


EN
DT Midstream (DTM), The Latest Update Raises A Bigger Question
DT Midstream (DTM) just delivered third quarter earnings alongside a fresh dividend decision, giving investors new data on both profitability and income. The latest results and the affirmed payout arrive as trading heads into year end.
Despite the fresh earnings and dividend update, DT Midstream’s share price has been under pressure, with a 7 day share price return of down 8.6% and a 90 day move of down 15.3%, even as the 3 year total shareholder return of about 132% reflects a very different long term experience for holders.
Scan beyond DT Midstream and compare this earnings and dividend story with a curated 7 dividend fortresses that has been filtered for income strength and resilience.
DT Midstream now trades well below analyst targets after a sharp pullback, even as earnings and the dividend policy remain intact. Is this caution sensible, or has pricing drifted too far from fair value?
Most Popular Narrative: 24% Undervalued
On the widely followed narrative framework, DT Midstream’s fair value sits at about $149.73 compared with a last close of $113.66. This puts recent share weakness against a much higher long run assessment of the project backlog and cash generation potential.
Modernization and expansion programs are being pursued alongside a conservative balance sheet, with leverage guided around 2.9x in 2026 and higher downgrade thresholds from credit agencies. Together these factors support funding of the $3.4b organic backlog from internal cash flow and debt capacity and can translate into higher future EBITDA and distributable cash flow without relying on equity issuance.
See why 5 investors see DT Midstream as 24% undervalued.
Result: Fair Value of $149.73 (UNDERVALUED)
Still, the narrative can break if DT Midstream faces slower permitting on pipeline projects, or if long term natural gas demand softens and leaves assets underused.
Find out about the key risks to this DT Midstream narrative.
Another View: DT Midstream Looks Expensive on Earnings
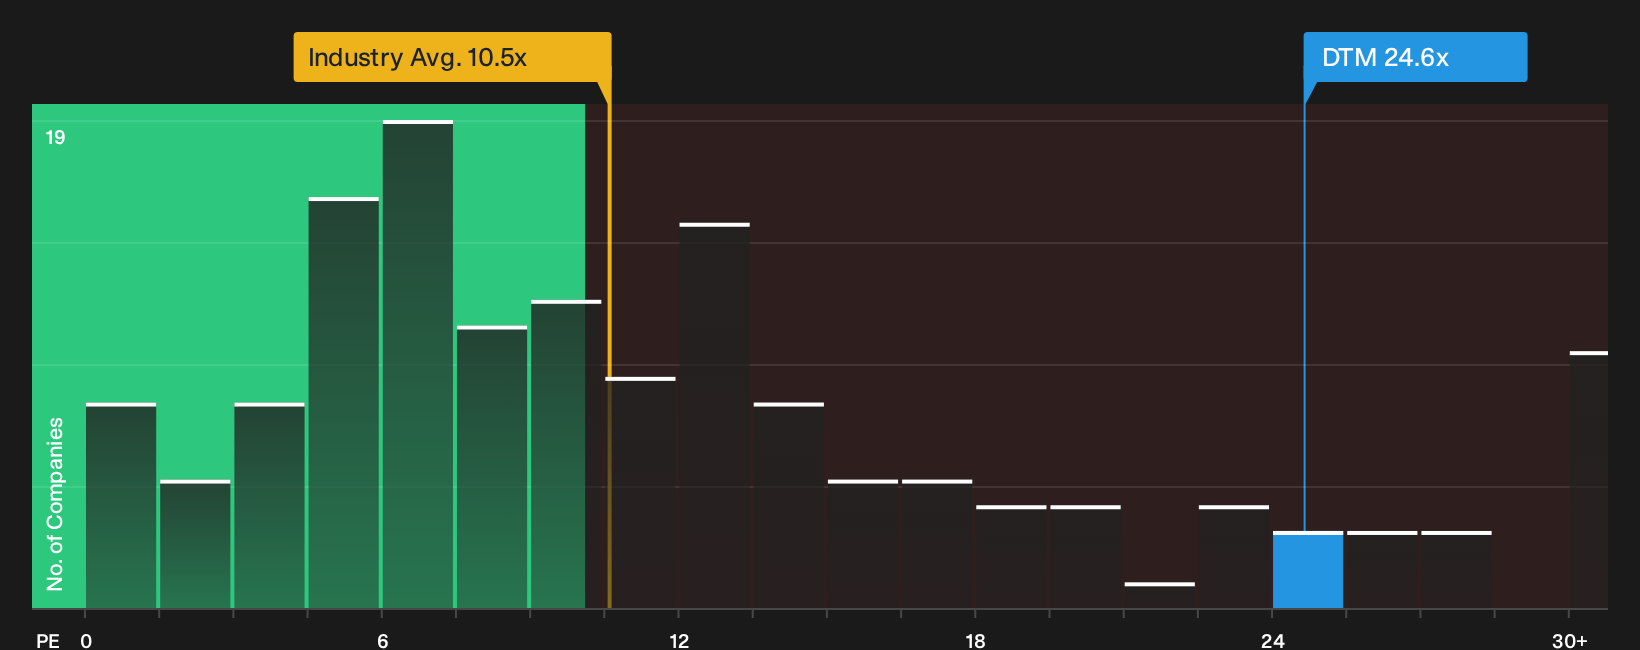
That $149.73 fair value narrative leans on long term forecasts and cash flow potential. A simpler earnings lens paints a different picture. DT Midstream trades on a P/E of 24.6x, while the US Oil and Gas industry sits near 10.3x and peers around 13.2x. The fair ratio is 18.3x, which is the level the multiple could drift toward if optimism cools. Is the premium a cushion or a risk if projects slip?
To see how this earnings based view lines up with the rest of the valuation work, including detailed peer checks and assumptions, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If you are conflicted about whether DT Midstream’s recent pullback signals opportunity or risk and want to move before sentiment shifts again, then weigh the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond DT Midstream?
Do not stop your research with DT Midstream. Broaden your watchlist with fresh ideas built from clear data so you are not reacting after the market moves.
- Target potential mispricings by scanning a curated pool of companies that pair quality with attractive entry points using the 38 high quality undervalued stocks.
- Reinforce your income stream by focusing on businesses that combine yield with balance sheet strength inside the 7 dividend fortresses.
- Reduce portfolio stress by concentrating on companies screened for resilient financial profiles through the 31 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com