


EN
Floor & Decor Holdings (FND) Just Gave Investors Something To Think About
Floor & Decor Holdings (FND) just paired fresh earnings numbers with more bricks and mortar. Management reported higher sales, net income and earnings per share, and then followed up with new warehouse openings in Maryland and Florida.
Investors have rewarded the recent earnings beat and store openings with a 7.69% 7 day share price gain and a 12.64% 30 day share price return, although momentum looks fragile given the 90 day share price decline of 13.39% and a 1 year total shareholder return that is down 13.52%.
Scan how Floor & Decor Holdings compares with other retailers showing resilient balance sheets and cash generation by reviewing our hand-picked list of solid balance sheet and fundamentals (25 results)
Floor & Decor Holdings has fresh earnings and new stores on the ground, yet the share price has swung between sharp rallies and longer declines. Is this latest bounce about business strength or sentiment snapping back, and what might that imply for valuation next?
Most Popular Narrative: 9% Undervalued
Floor & Decor Holdings closed at $51.25, while the most followed narrative pegs fair value at $56.45, leaving a modest upside gap that hinges on how new stores, Pro customers and digital sales translate into long term earnings power.
The evolution toward a more capital efficient footprint, with average new store costs declining from roughly US$11.7 million in 2023 to about US$10.2 million for the 2025 class and an expected range of US$7.5 to US$8.0 million in 2026, together with infill locations in denser markets, creates room for higher returns on invested capital and more free cash flow that can support earnings growth.
See why 13 investors see Floor & Decor Holdings as 9% undervalued.
Result: Fair Value of $56.45 (UNDERVALUED)
Still, the Floor & Decor Holdings story can break if comparable sales stay weak while new store openings keep climbing, or if vinyl and laminate pricing pressure keeps squeezing gross margins.
Find out about the key risks to this Floor & Decor Holdings narrative.
Another View: Floor & Decor Holdings Through The P/E Lens
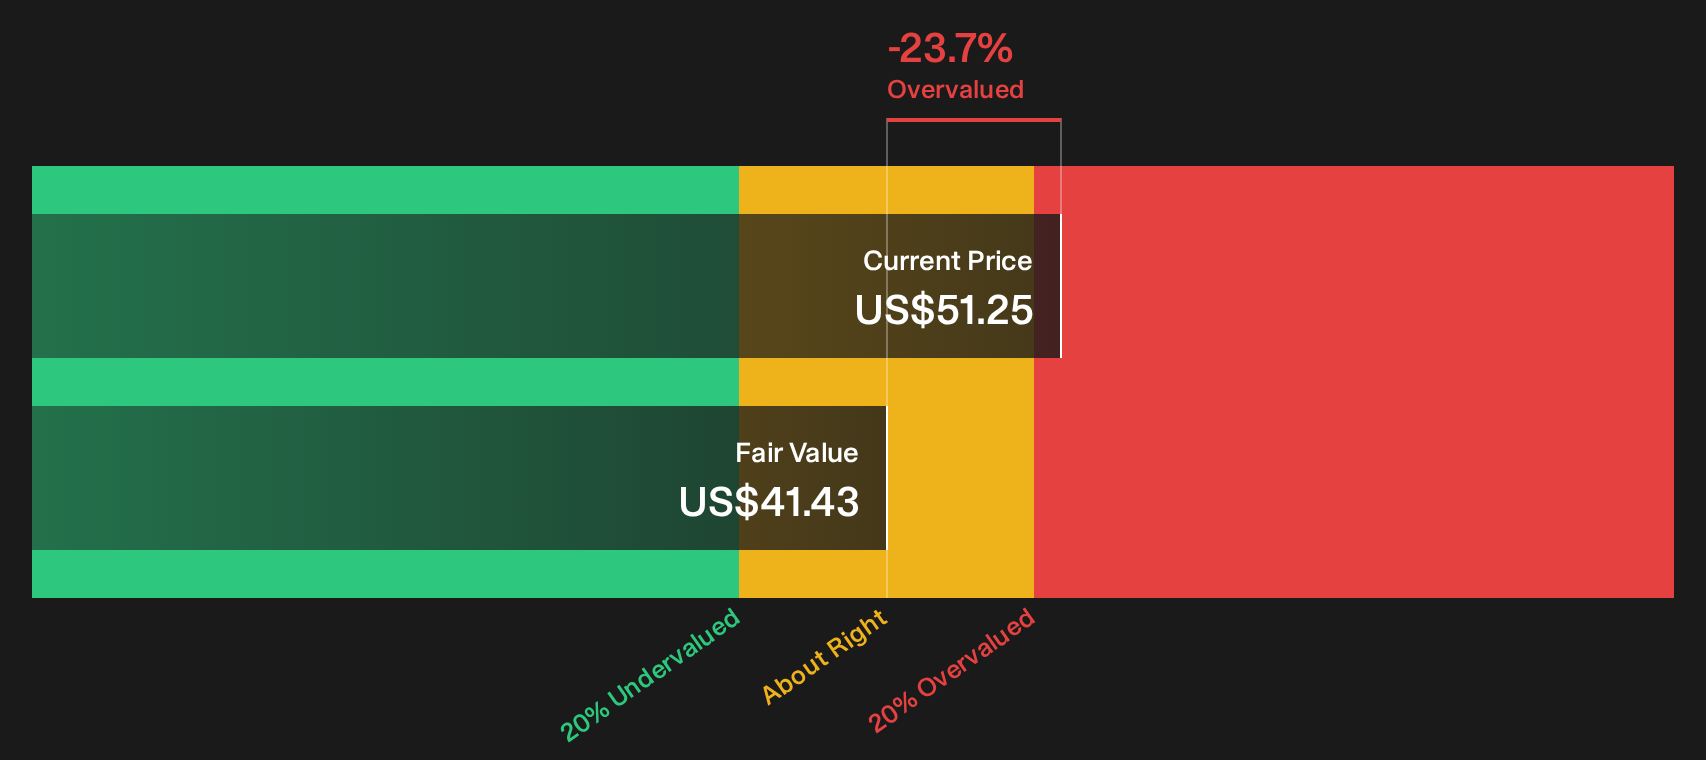
The SWS DCF model flags Floor & Decor Holdings as expensive at $51.25 versus an estimated future cash flow value of $41.43, which contrasts with the earlier fair value of $56.45. That gap suggests investors are paying up for the story today. The question is whether you agree with the cash flow assumptions sitting underneath that call.
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Sentiment around Floor & Decor Holdings feels finely balanced right now, so move quickly, review the data for yourself, and weigh how the 1 important warning sign fits into your view.
Looking For More Investment Ideas Beyond Floor & Decor Holdings?
If you stop with just one stock, you risk missing out on ideas that better match your risk tolerance, income needs, or long term goals.
- Target resilient portfolios by scanning a curated 31 resilient stocks with low risk scores that focuses on companies with steadier profiles when markets feel choppy.
- Hunt for potential mispricings with a hand picked 38 high quality undervalued stocks that blends solid fundamentals with more attractive entry points.
- Build a watchlist of potential future leaders by checking a focused 19 high quality undiscovered gems that highlights quality businesses still off most investors' radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com