


EN
3 Canadian Growth Stocks With Earnings Growth Up To 58%
Higher interest rates are expected to stick around through 2027, so cash in the bank is unlikely to do the heavy lifting for your future wealth. That puts fast growing Canadian businesses with meaningful insider ownership in the spotlight, because management has clear skin in the game. This article walks through three such stocks from our high growth, high insider alignment screen so you can decide which belong on your watchlist.
The three stocks highlighted here offer a compelling starting point if you want exposure to fast growing businesses where insiders have substantial skin in the game. However, if you want the strongest names, these 9 high growth high conviction stocks are the top of the list.
Bombardier (TSX:BBD.B)
Bombardier is a pure play on business jets, with its Challenger and Global aircraft and related services forming the growth engine that aligns it with the Fast Growing Stocks With High Insider Ownership theme.
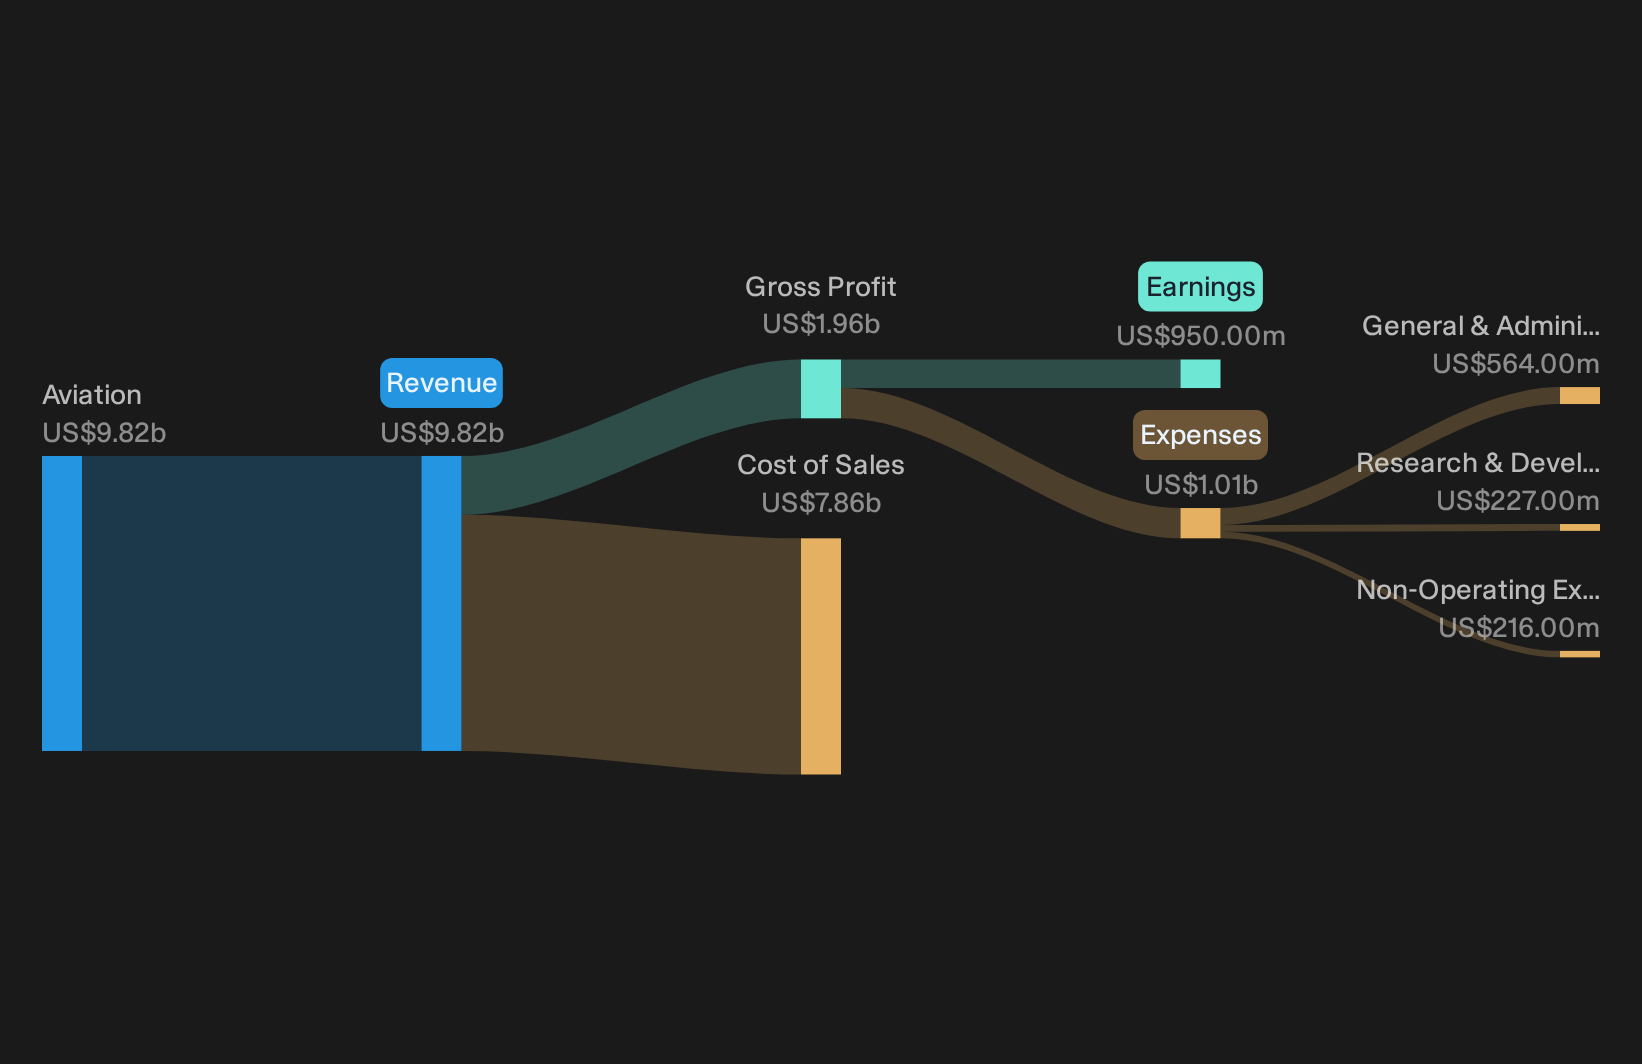
Bombardier generates about US$9.8b in Aviation revenue, essentially all from its business aircraft activities and related services, and has a market value of roughly CA$31.4b, which puts it firmly in large cap territory on the TSX.
For this screener, Bombardier matters because its growing fleet of Challenger and Global jets feeds a larger installed base that can support recurring, higher margin services revenue over time.
"Record Services revenue of US$674 million in Q2 2026 and double digit growth in the first half of the year, with Services now over one third of total revenue and supported by programs like Smart Services that cover more than 1,500 aircraft, points to a growing base of recurring, higher margin activity that can support revenue mix and margins over time."
What investors need to watch closely now is how one unresolved funding pressure shapes the balance between that margin potential and future growth capacity.
That funding question is exactly what the full narrative for Bombardier unpacks in detail, including how Bombardier’s service engine and leverage could be decoupling faster than headlines suggest.
Colliers International Group (TSX:CIGI)
Colliers International Group runs a broad commercial real estate and engineering platform, but its fee-based capital markets and investment management work ties it most closely to the Fast Growing Stocks With High Insider Ownership theme. This is supported by services that scale with property transactions and long-dated fund mandates.
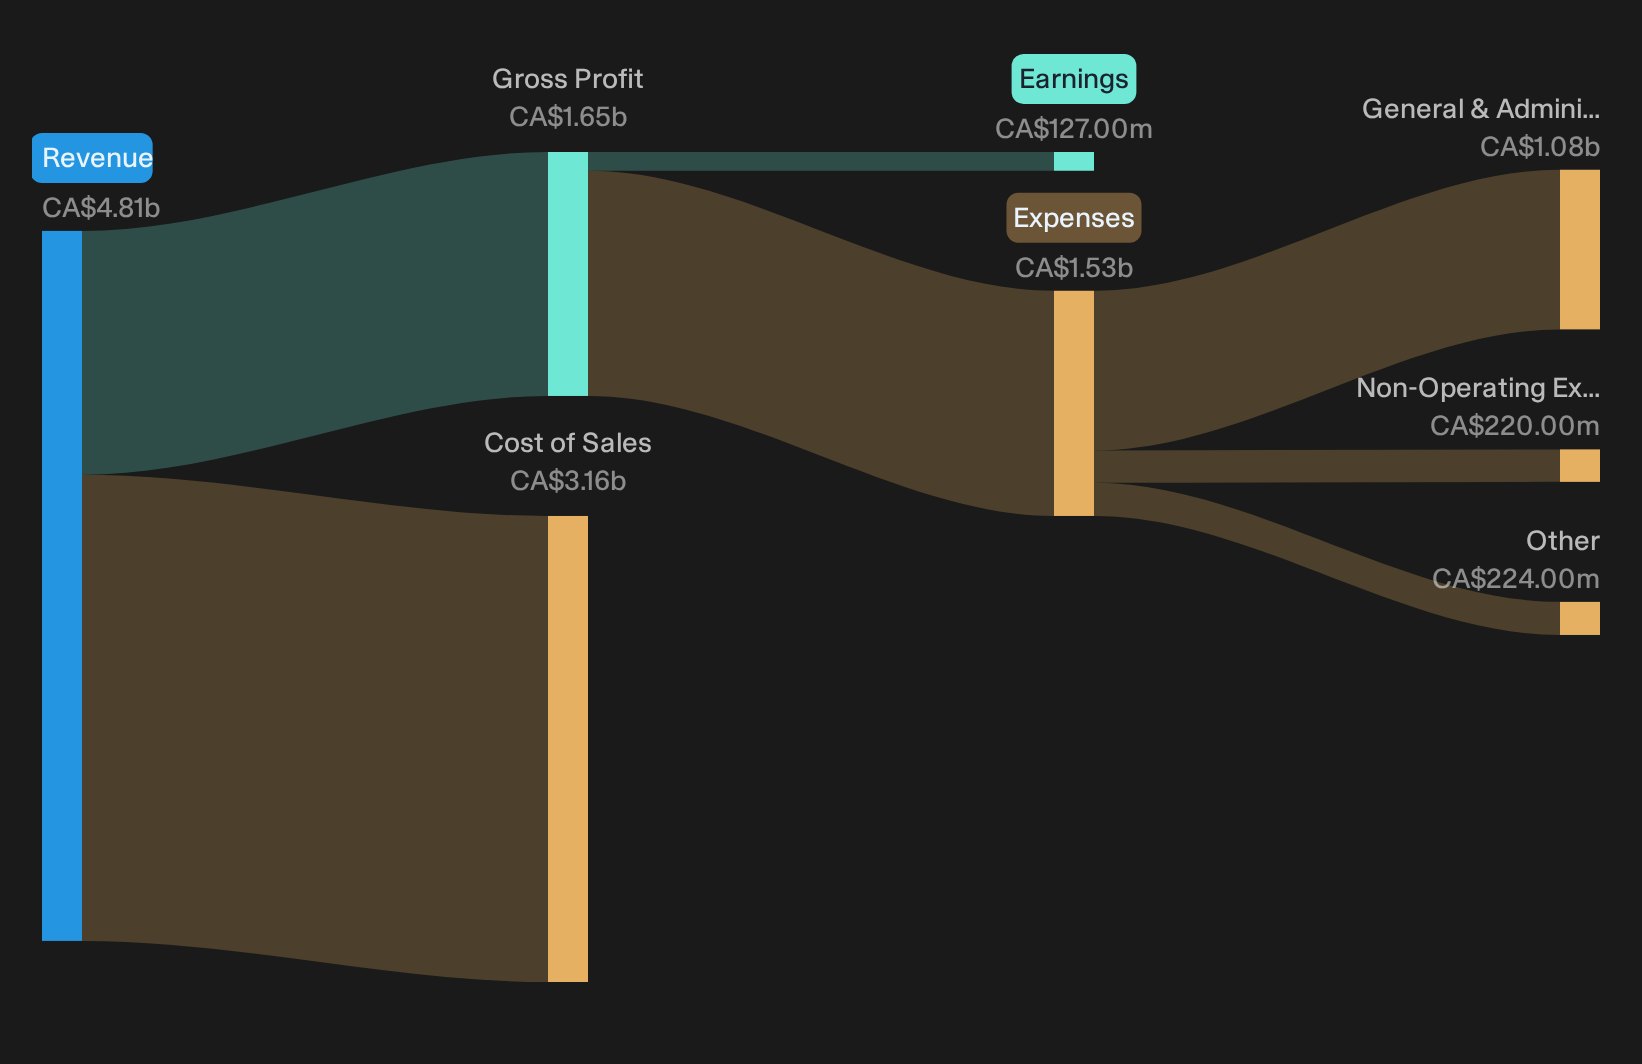
Real estate services contribute about US$3.5b in revenue, engineering roughly US$2b, and investment management about US$571 million, with the group valued at roughly CA$6.8b.
Colliers International Group matters here because its advisory, brokerage, and long-horizon fund management combine growth-focused fee streams with meaningful insider alignment. This links management optimism to the same capital markets and investment performance levers investors are watching in this screener.
"The growing interest from institutional and private wealth channels in alternative asset classes such as data centers, student housing, infrastructure, and credit solutions is driving segment diversification and AUM growth in the investment management business, supporting future recurring fee revenue and higher net margins."
What could really move the needle for Colliers International Group now is how one unseen pressure shapes the balance between future earnings growth and margin resilience.
That pressure point is exactly where the full narrative for Colliers International Group shows whether Colliers International Group’s fee engine is quietly accelerating or if hidden risks are masking the story.

Cascades (TSX:CAS)
Cascades is a CA$1.6b packaging and tissue group that supplies boxes, trays, mailers, tissue and recycled paperboard. Its e-commerce focused Packaging Products arm links the business directly to fast-growing online retail and food-service demand.
Cascades gives you a very different angle on the Fast Growing Stocks With High Insider Ownership theme, because its core packaging work ties everyday cardboard boxes and mailers directly to rising online retail and food-service activity.
"Continued ramp up at the Bear Island mill toward Greenpac level efficiencies, combined with targeted reductions in chemical and material usage, should lift Packaging segment productivity and support structurally higher EBITDA margins."
What happens to Cascades’ earnings profile now largely depends on how one quiet shift in its pricing and cost backdrop plays out.
If that shift is what you care about, the full narrative for Cascades shows whether Cascades’ efficiency push is quietly accelerating or if cost pressures are still masking it.
Seeking Fresh Alternatives Before They Fly
New ideas move first, prices move next. Scan fresh breakout candidates under the radar for now, before the crowd catches on and the gap closes. Consider moving earlier in the process.
- Spot potential turnaround income plays by scanning a curated 3 dividend fortresses that focus on durability, cash coverage, and yields that could matter if rates stay higher for longer.
- Track the next infrastructure momentum wave with a focused group of 41 power grid technology and infrastructure stocks that connect directly to grid upgrades, electrification demand, and long-cycle capital spending.
- Zero in on future compute themes through a tight universe of 25 quantum computing stocks that sit at the intersection of advanced hardware, algorithms, and real-world commercialization.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com