


EN
Yelp Stock What Changed After Revenue Guidance Cut
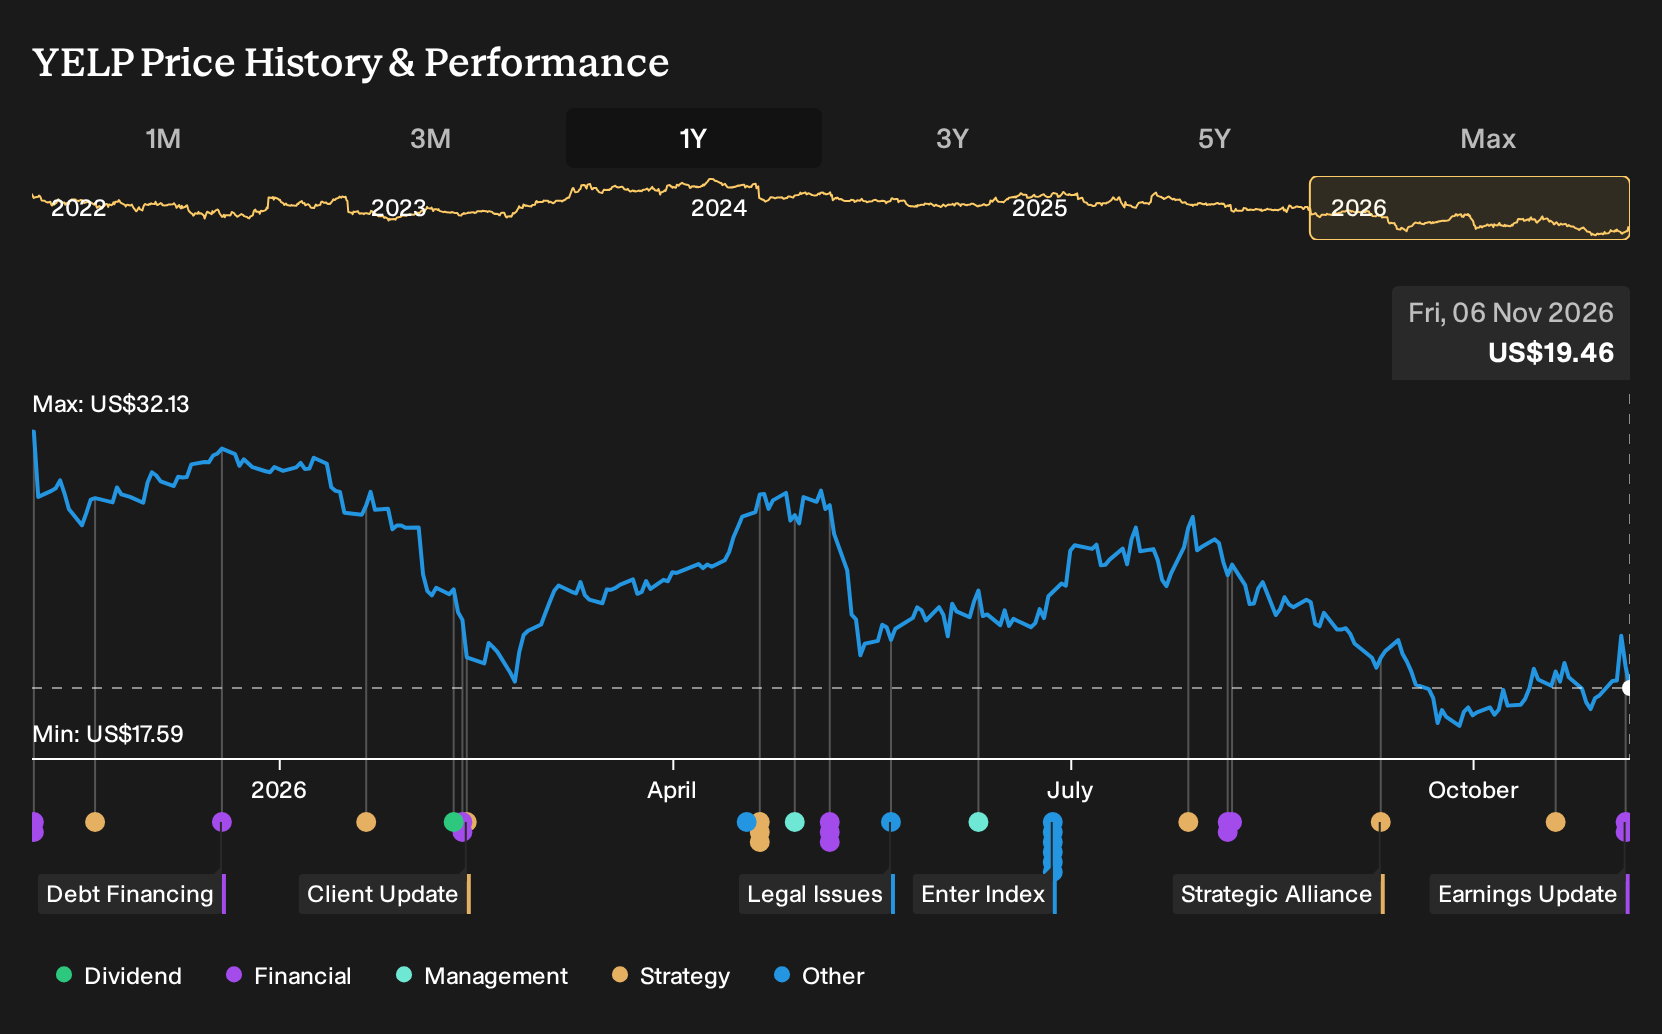
- Yelp reported third quarter 2026 sales of US$370.92 million and net income of US$34.55 million, with full year 2026 net revenue guidance reduced to a range of US$1.455 billion to US$1.460 billion after softer local advertising demand.
- The pressure on Yelp's core ads business contrasts with rapid growth in AI driven tools and data licensing, where new high margin agreements and products are starting to build a second revenue engine. Management is positioning this as a partial offset to weaker local marketing budgets.
- The focus now turns to how Yelp's investment narrative could be reshaped by this cut to full year revenue guidance.
Scan beyond Yelp and size up other platforms reshaping online discovery with AI by reviewing the hand picked 40 profitable AI stocks that aren't just burning cash that already pair real revenue with meaningful profitability.
Yelp Investment Narrative Recap
To own Yelp, you need to believe the local ads engine can stabilize while AI tools, subscription products and high margin data licensing grow into a more meaningful second leg. The Q3 revenue slip and lower 2026 guidance put the near term spotlight on whether local advertising demand finds a floor. That is the main short term catalyst.
The biggest risk sits on the other side of the same coin. If ad weakness in restaurants, retail and services lingers while Yelp keeps spending on AI, Hatch and marketing, margin pressure can stick around. The latest quarter reinforces that this risk is real, not theoretical.
The most relevant announcement is Yelp’s updated 2026 net revenue guidance of US$1.455b to US$1.460b. That range is below 2025 levels and frames expectations around a tougher year for local marketing budgets. It also sets a clearer hurdle for how much AI search API, Host, Hatch and data licensing need to contribute.
This guidance reset feeds directly into the key catalyst. Execution now means converting partner deals with OpenAI, Apple Maps, Amazon Alexa, Microsoft Bing, Meta.ai and Yahoo, plus AI powered tools inside Yelp, into dependable, higher margin revenue. If these newer streams do not scale fast enough, the guidance cut highlights how exposed Yelp remains to local ad cycles.
Yelp's current analyst narrative points to US$1.6b in revenue and US$157.9 million in earnings by 2029, based on an assumed 2.1% yearly revenue growth rate and an earnings increase of about US$31 million from US$126.5 million today.
Uncover how Yelp's fair value indicates a 29% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
You now see just how different opinions on Yelp can be. The lowest analysts lean into a more cautious catalyst. They worry that AI tools and Hatch style products may struggle to offset pressure on local ads, even though they were still modeling about US$1.5b in revenue and US$153.9 million in earnings by 2029 before this guidance cut. That is a notably cooler view than the baseline, and this latest report could influence those expectations. Use that gap to test where your own outlook really sits along the spectrum.
Explore 4 other Yelp fair value estimates, including one that suggests it could be worth just $23.25.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Yelp research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Yelp. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Yelp's overall financial health at a glance.
Looking For More Ideas Beyond Yelp?
Once you have a view on Yelp, it can help to widen the lens and compare it with other businesses that match different risk, income and quality profiles. Use the Simply Wall St Screener to line up alternatives side by side and assess whether Yelp still earns a place in your watchlist against other opportunities.
- If capital protection matters most to you, start by scanning companies with sturdier profiles through the 31 resilient stocks with low risk scores.
- For investors hunting for resilient balance sheets and solid fundamentals, broaden your watchlist by reviewing the list of solid balance sheet and fundamentals (25 results).
- Those searching for potential future standouts can sift through underfollowed opportunities using the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com