


EN
Wingstop Inc. (NASDAQ:WING) Passed Our Checks, And It's About To Pay A US$0.33 Dividend
Some investors rely on dividends for growing their wealth, and if you're one of those dividend sleuths, you might be intrigued to know that Wingstop Inc. (NASDAQ:WING) is about to go ex-dividend in just four days. The ex-dividend date is one business day before a company's record date, which is the date on which the company determines which shareholders are entitled to receive a dividend. The ex-dividend date is an important date to be aware of as any purchase of the stock made on or after this date might mean a late settlement that doesn't show on the record date. This means that investors who purchase Wingstop's shares on or after the 13th of November will not receive the dividend, which will be paid on the 4th of December.
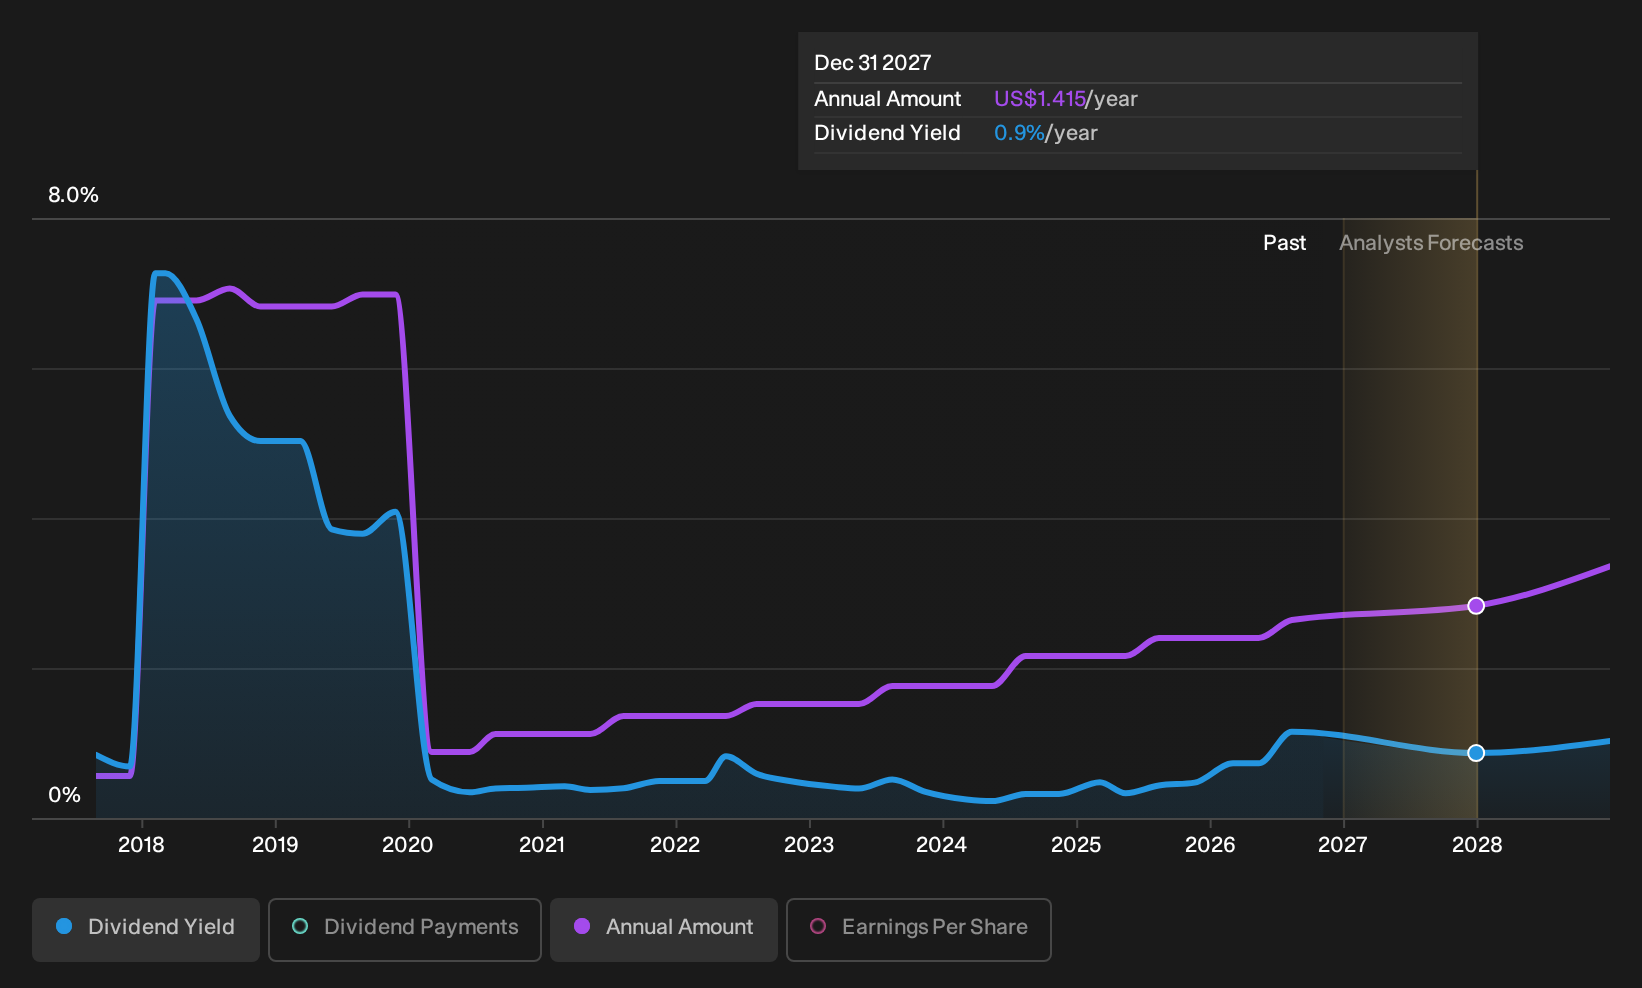
The company's upcoming dividend is US$0.33 a share, following on from the last 12 months, when the company distributed a total of US$1.32 per share to shareholders. Last year's total dividend payments show that Wingstop has a trailing yield of 0.8% on the current share price of US$163.28. If you buy this business for its dividend, you should have an idea of whether Wingstop's dividend is reliable and sustainable. That's why we should always check whether the dividend payments appear sustainable, and if the company is growing.
Dividends are typically paid out of company income, so if a company pays out more than it earned, its dividend is usually at a higher risk of being cut. Fortunately Wingstop's payout ratio is modest, at just 29% of profit. That said, even highly profitable companies sometimes might not generate enough cash to pay the dividend, which is why we should always check if the dividend is covered by cash flow. It distributed 29% of its free cash flow as dividends, a comfortable payout level for most companies.
It's positive to see that Wingstop's dividend is covered by both profits and cash flow, since this is generally a sign that the dividend is sustainable, and a lower payout ratio usually suggests a greater margin of safety before the dividend gets cut.
See our latest analysis for Wingstop
Click here to see the company's payout ratio, plus analyst estimates of its future dividends.
Have Earnings And Dividends Been Growing?
Businesses with strong growth prospects usually make the best dividend payers, because it's easier to grow dividends when earnings per share are improving. If earnings fall far enough, the company could be forced to cut its dividend. That's why it's comforting to see Wingstop's earnings have been skyrocketing, up 41% per annum for the past five years. Wingstop is paying out less than half its earnings and cash flow, while simultaneously growing earnings per share at a rapid clip. This is a very favourable combination that can often lead to the dividend multiplying over the long term, if earnings grow and the company pays out a higher percentage of its earnings.
Many investors will assess a company's dividend performance by evaluating how much the dividend payments have changed over time. Wingstop has delivered an average of 19% per year annual increase in its dividend, based on the past nine years of dividend payments. It's great to see earnings per share growing rapidly over several years, and dividends per share growing right along with it.
To Sum It Up
From a dividend perspective, should investors buy or avoid Wingstop? Wingstop has grown its earnings per share while simultaneously reinvesting in the business. Unfortunately it's cut the dividend at least once in the past nine years, but the conservative payout ratio makes the current dividend look sustainable. Overall we think this is an attractive combination and worthy of further research.
In light of that, while Wingstop has an appealing dividend, it's worth knowing the risks involved with this stock. We've identified 4 warning signs with Wingstop (at least 2 which don't sit too well with us), and understanding them should be part of your investment process.
A common investing mistake is buying the first interesting stock you see. Here you can find a full list of high-yield dividend stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.