


EN
HCA Healthcare (HCA) Faces A 28% Fair Value Gap As Earnings Beat
HCA Healthcare (HCA) just cleared third quarter 2026 earnings expectations, with stronger patient admissions, firmer insured revenue per admission, and cost control efforts shaping how investors read the latest move in the stock.
Recent price action has been strong. HCA Healthcare’s share price has gained 19.55% over the past 90 days and 9.73% over the past month, while a 3-year total shareholder return of 117.52% signals momentum that investors are weighing against fresh bond issuance, buybacks, and the latest dividend affirmation.
Spot other hospital and healthcare operators that pair balance sheet firepower with earnings momentum by scanning our curated list of list of solid balance sheet and fundamentals (25 results).After a sharp run to about $495 and fresh bond issuance in the background, the real test for HCA Healthcare now is simple: Does the current price still compensate you for the risks on admissions mix and reimbursement?
Most Popular Narrative: 28% Overvalued
Compared with HCA Healthcare’s last close of $494.99, the most followed fair value narrative of about $388 suggests the share price is running ahead of that framework. That view puts more weight on payer mix risk, Medicaid variability, and a lower future earnings multiple.
There is higher acuity in areas like cardiac care, trauma and rehab. However, payer mix shifts tied to exchanges, growth in uninsured equivalent admissions and slower Medicaid conversions could keep uncompensated care and patient balance collections elevated, placing a ceiling on revenue yield and adjusted EBITDA margins.
See why 0 investors see HCA Healthcare as 28% overvalued.
Result: Fair Value of $388 (OVERVALUED)
Still, a more generous backdrop for Medicaid supplemental programs, or faster payoffs from HCA Healthcare’s digital and AI rollout, could quickly challenge this overvaluation story.
Find out about the key risks to this HCA Healthcare narrative.
Another View on HCA Healthcare’s valuation
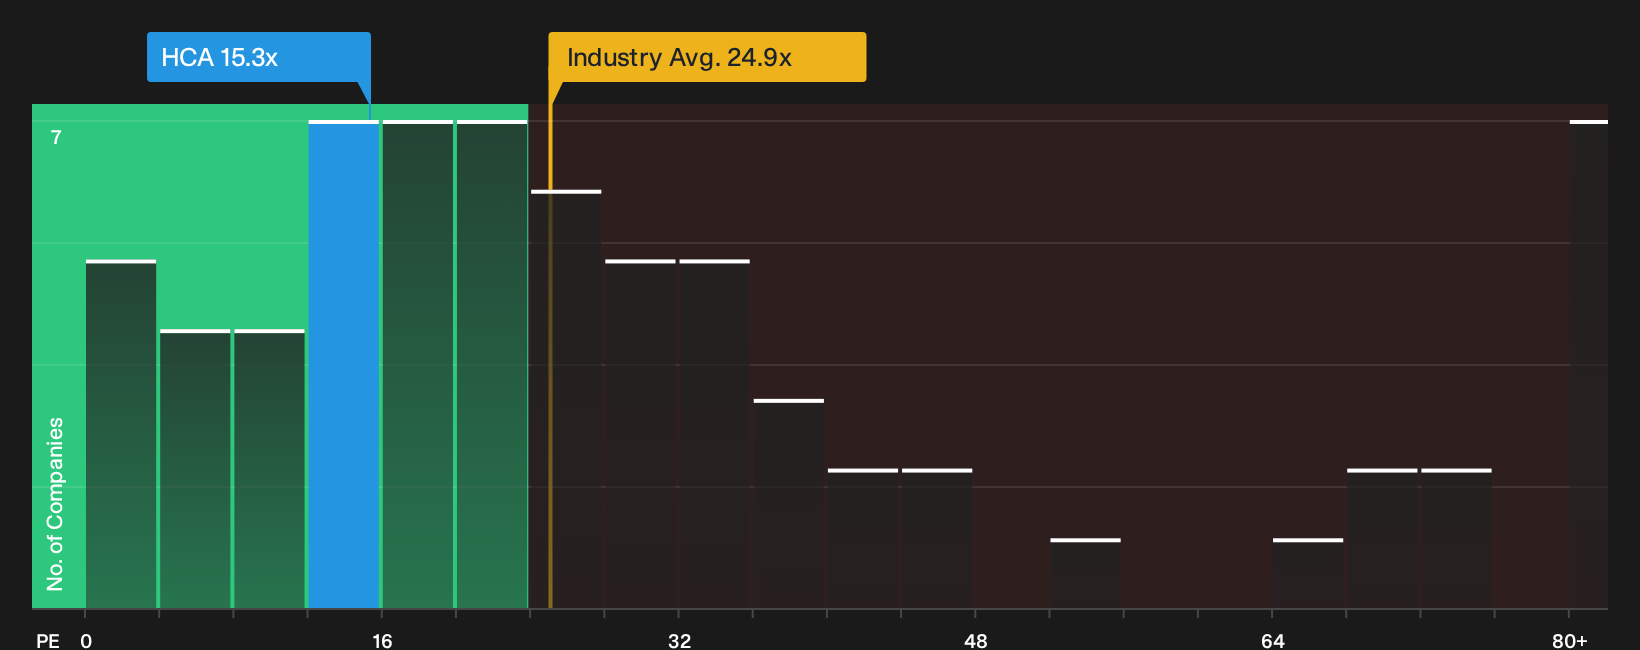
The fair value narrative around $388 paints HCA Healthcare as 28% overvalued, yet the current P/E of 15.3x looks far less demanding next to the US Healthcare sector on 24.9x and an estimated fair ratio of 29.2x. If the market edges closer to that fair ratio instead, this comparison could look very different.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on HCA Healthcare’s valuation so far. Now is the moment to review the numbers yourself, pressure test the assumptions, and weigh both sides of the story with 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond HCA Healthcare?
If HCA Healthcare has sharpened your focus on quality and price, you can use that same lens to sift through other opportunities before the market moves without you.
- Target resilient cash generators by scanning a curated group of strong balance sheet businesses through the list of solid balance sheet and fundamentals (25 results).
- Zero in on value by filtering for companies that pair quality fundamentals with modest pricing using the 38 high quality undervalued stocks.
- Build a steadier income stream by reviewing rock solid payout candidates through the 7 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com