


EN
Earnings Release Could Be A Turning Point For PTC Stock (PTC)
- PTC reported fourth quarter 2026 revenue of US$673.25 million and net income of US$157.26 million, with full year revenue of US$2.73 billion and net income of US$1.03 billion for the period ended September 30, 2026.
- The sharp contrast between softer fourth quarter results and higher full year earnings per share points to meaningful shifts in cost discipline, mix, or one off factors across PTC's fiscal 2026.
- We will now examine how PTC's weaker fourth quarter against a stronger full year earnings profile could reshape its broader investment narrative.
Scan beyond PTC's mixed quarter and full year to review a curated set of software peers with sturdier trends using the 31 resilient stocks with low risk scores.
PTC Investment Narrative Recap
To stay comfortable holding PTC, you need to believe the core subscription engines in PLM, CAD and service software can keep compounding through product upgrades and AI features like Creo AI and ServiceMax AI. The latest quarter showed softer revenue and earnings than a year ago, while the full year still delivered US$1.03b in net income and higher EPS.
In the near term, the key swing factor remains how consistently PTC translates its AI portfolio and CPP contracts into dependable ARR and free cash flow. The main operational risk is that elevated churn and weaker upsell in ServiceMax persist, which could drag on group growth even if flagship platforms such as Windchill and Arena stay healthy.
The most important fresh data point for this narrative is the full year 2026 earnings print. Sales of US$2.62b and revenue of US$2.73b were broadly stable against the prior year figure provided, yet net income reached US$1.03b with basic EPS from continuing operations at US$8.97.
That combination gives you a clearer read on execution around pricing, cost discipline and AI led products than any commentary alone. It also sharpens the risk reward trade off. PTC’s plan leans heavily on sustained ARR monetisation and stable ServiceMax retention, so any future updates on churn, renewals or AI consumption will matter more than short term quarter to quarter noise in reported revenue.
PTC's current consensus narrative assumes revenue will increase to US$3.3b and earnings will reach US$907.5m by 2029, based on analysts using a 4.1% yearly revenue growth rate and an earnings decline of about US$292.5m from US$1.2b today to the 2029 forecast level.
Uncover how PTC's fair value indicates a 3% potential upside to its current price, which could narrow quickly if sentiment catches up.
Exploring Other Perspectives
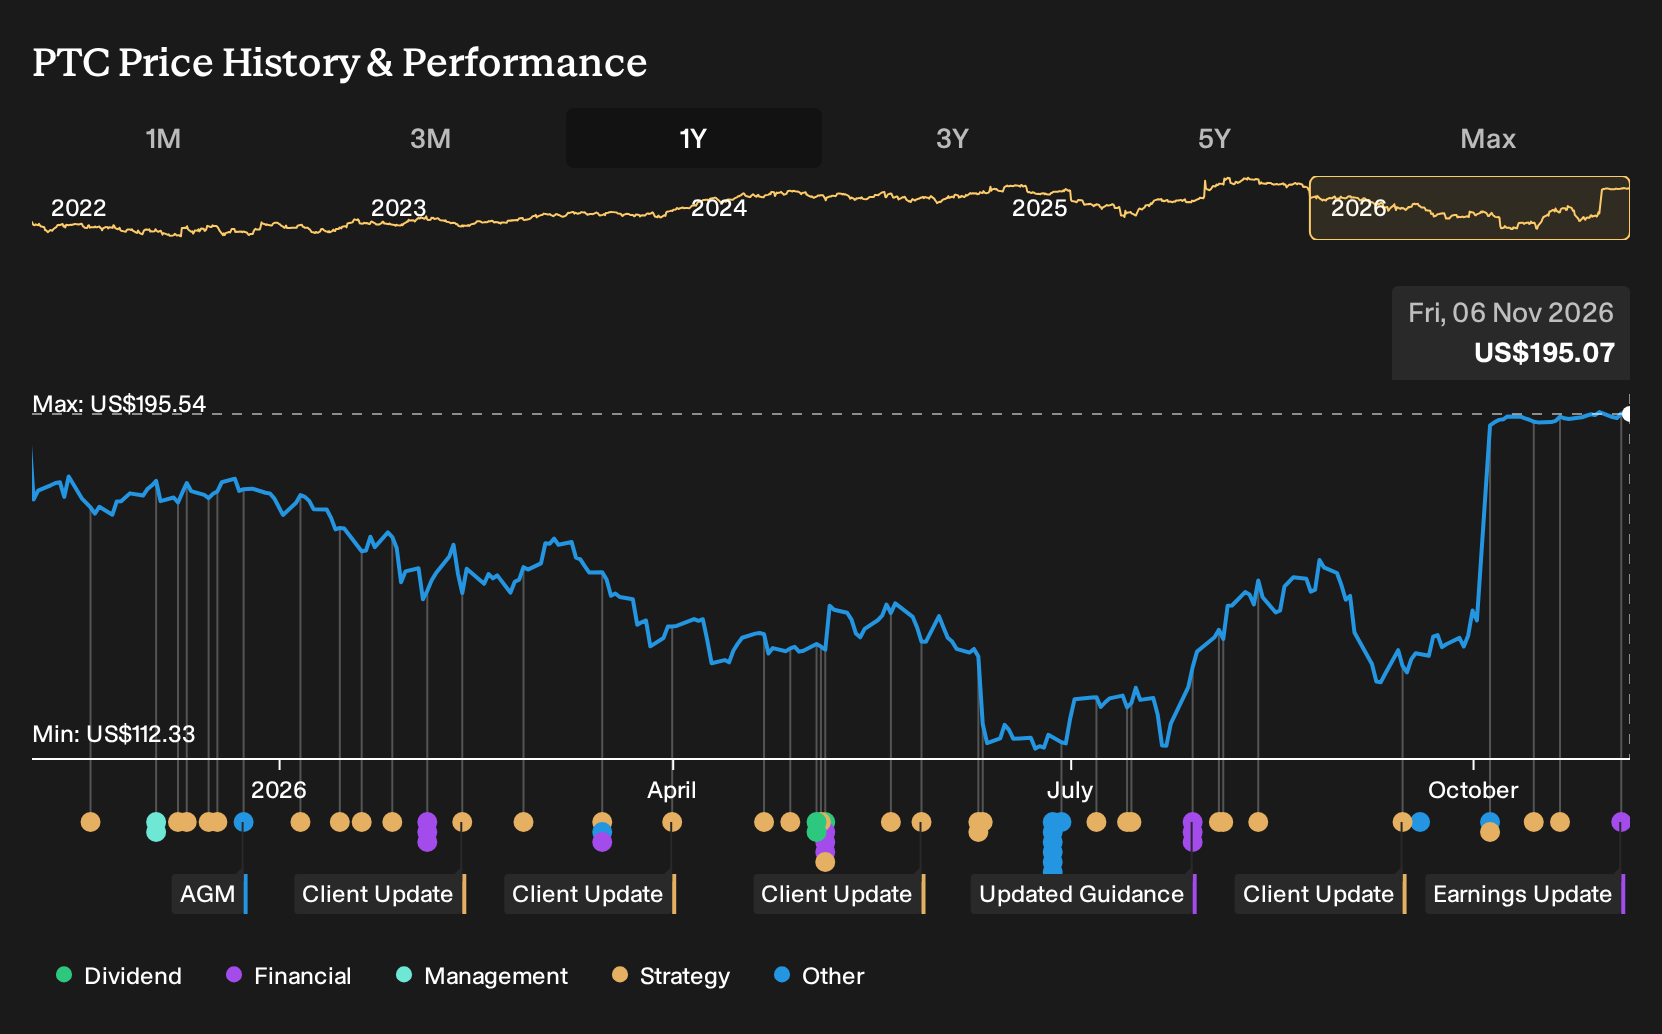
Some of the most optimistic analysts frame Schneider Electric’s planned acquisition of PTC as the real catalyst to watch, with models that previously penciled in revenue of about US$3.4b and earnings of roughly US$936.2m by 2029. You can read those far more upbeat assumptions as one end of a wide opinion range that may shift again after this earnings report.
Explore 6 other PTC fair value estimates, including one that suggests as much as 108% potential upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd. Trust your own analysis and instincts.
- A great starting point for your PTC research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for PTC. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate PTC's overall financial health at a glance.
Looking for more investment ideas beyond PTC?
Once you have a view on PTC, cast the net wider and line it up against other opportunities that better match your own risk, income, and quality preferences using the Simply Wall St Screener.
- If resilience and capital preservation sit high on your list, scan a curated 31 resilient stocks with low risk scores that score well on our internal risk checks.
- If you are hunting for value with quality fundamentals, sort through a focused 38 high quality undervalued stocks that combine stronger balance sheets with attractive valuation metrics.
- If reliable income matters more than rapid growth, filter for companies in the 7 dividend fortresses that currently offer higher yields backed by underlying fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com