


EN
Corpay (CPAY) Raised Full Year Guidance, Is The Stock Fully Priced?
Corpay (CPAY) just posted fresh third quarter numbers and raised its full year outlook, a combination that often puts a stock firmly on investor watchlists.
The fresh guidance appears to be feeding into strong momentum in Corpay’s stock, with a 7 day share price return of 13.52% and a 30 day gain of 14.38%, topping off a 51.42% year to date share price return and a 64.60% total shareholder return over the past year.
Scan how Corpay's earnings upgrade compares with other payment and fintech players lighting up the tape in our hand picked 38 high quality undervalued stocks.
Corpay now appears to be a powerful payments platform backed by fresh guidance and a surging share price. The real test is whether that recent strength still leaves room at today’s valuation.
Most Popular Narrative: 1% Undervalued
Corpay closed at $455.16 compared with a most followed fair value view of $461, so the narrative is effectively calling the stock about in line while still seeing a small gap to intrinsic worth at a 7.97% discount rate.
Corpay's portfolio simplification, including completed and announced divestitures of non-core Vehicle Payments assets such as PayByPhone and Epyx, with proceeds earmarked for share repurchases, continues to move mix toward corporate payments activities that management targets for higher growth and retention. This can support blended net margins and cash EPS.
See why 15 investors see Corpay as 1% undervalued.
Result: Fair Value of $461 (UNDERVALUED)
Still, the Corpay story relies on ongoing buybacks and cross-border expansion, while regulatory constraints and any slowdown in key segments could quickly challenge that narrative.
Find out about the key risks to this Corpay narrative.
Another View: Corpay Through The Earnings Lens
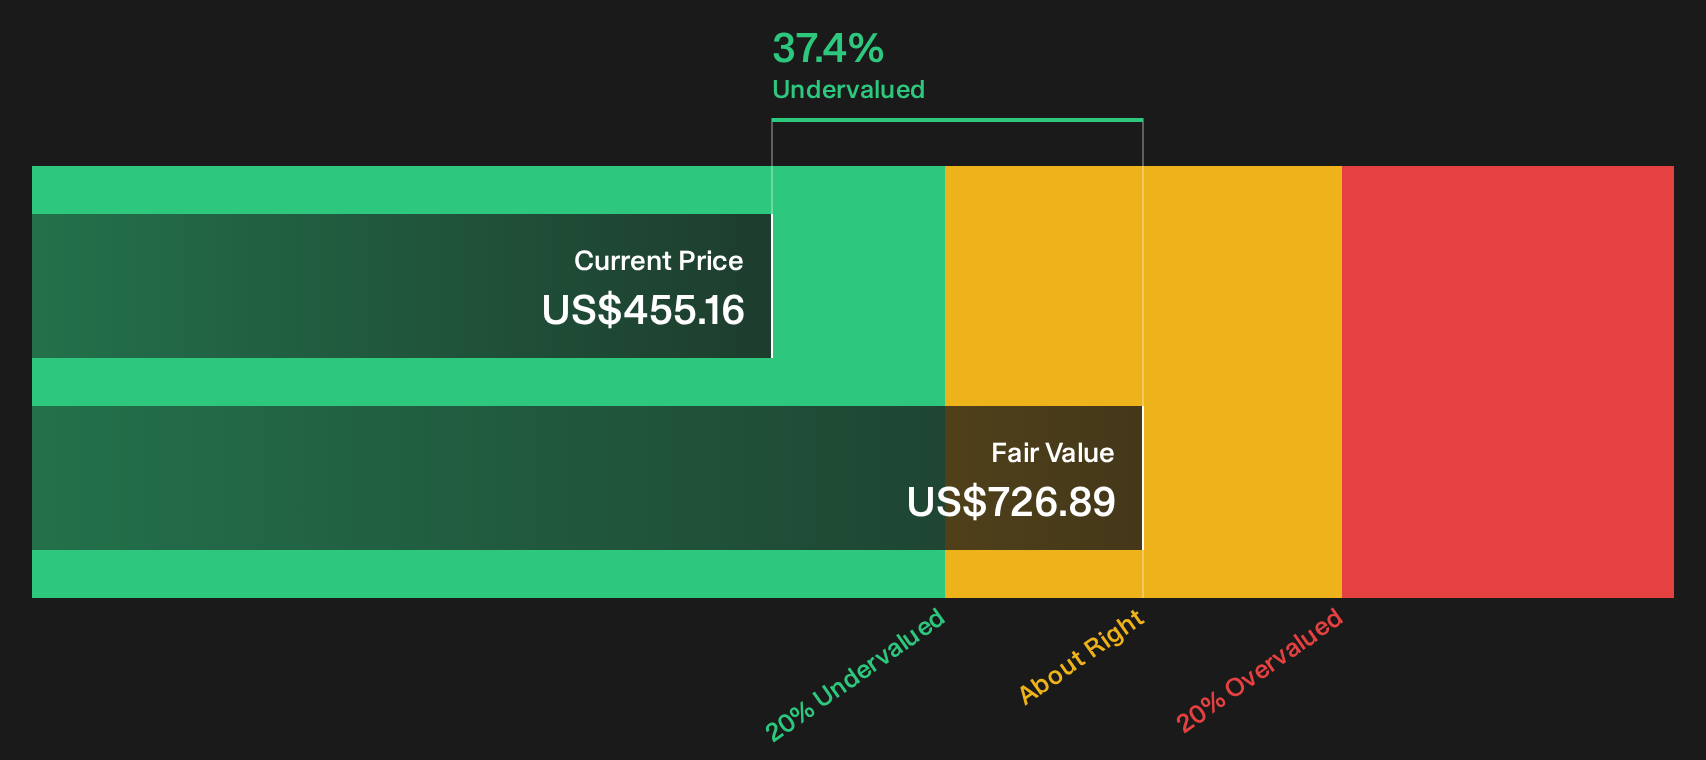
The SWS DCF model paints a much richer picture for Corpay. On that approach, the estimated future cash flow value sits at $726.89 per share versus the recent $455.16 price, which is flagged as undervalued. That is a wide gap. Does it reflect upside or just very optimistic cash flow assumptions?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed on Corpay so far or already leaning one way? Act while the data is fresh and stress test the thesis by weighing the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Corpay?
If Corpay has sharpened your view on pricing power and execution, do not stop there. Broaden your watchlist now and avoid missing the next opportunity.
- Target durable upside by focusing on quality companies trading below what their fundamentals suggest through our 38 high quality undervalued stocks.
- Strengthen your income stream and keep cash flow working for you with a curated set of resilient payers in the 7 dividend fortresses.
- Guard against unwanted surprises by concentrating on financially robust businesses using the list of solid balance sheet and fundamentals (25 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com