


EN
Did KNR Constructions Fall Catch You Out? What Investors Missed
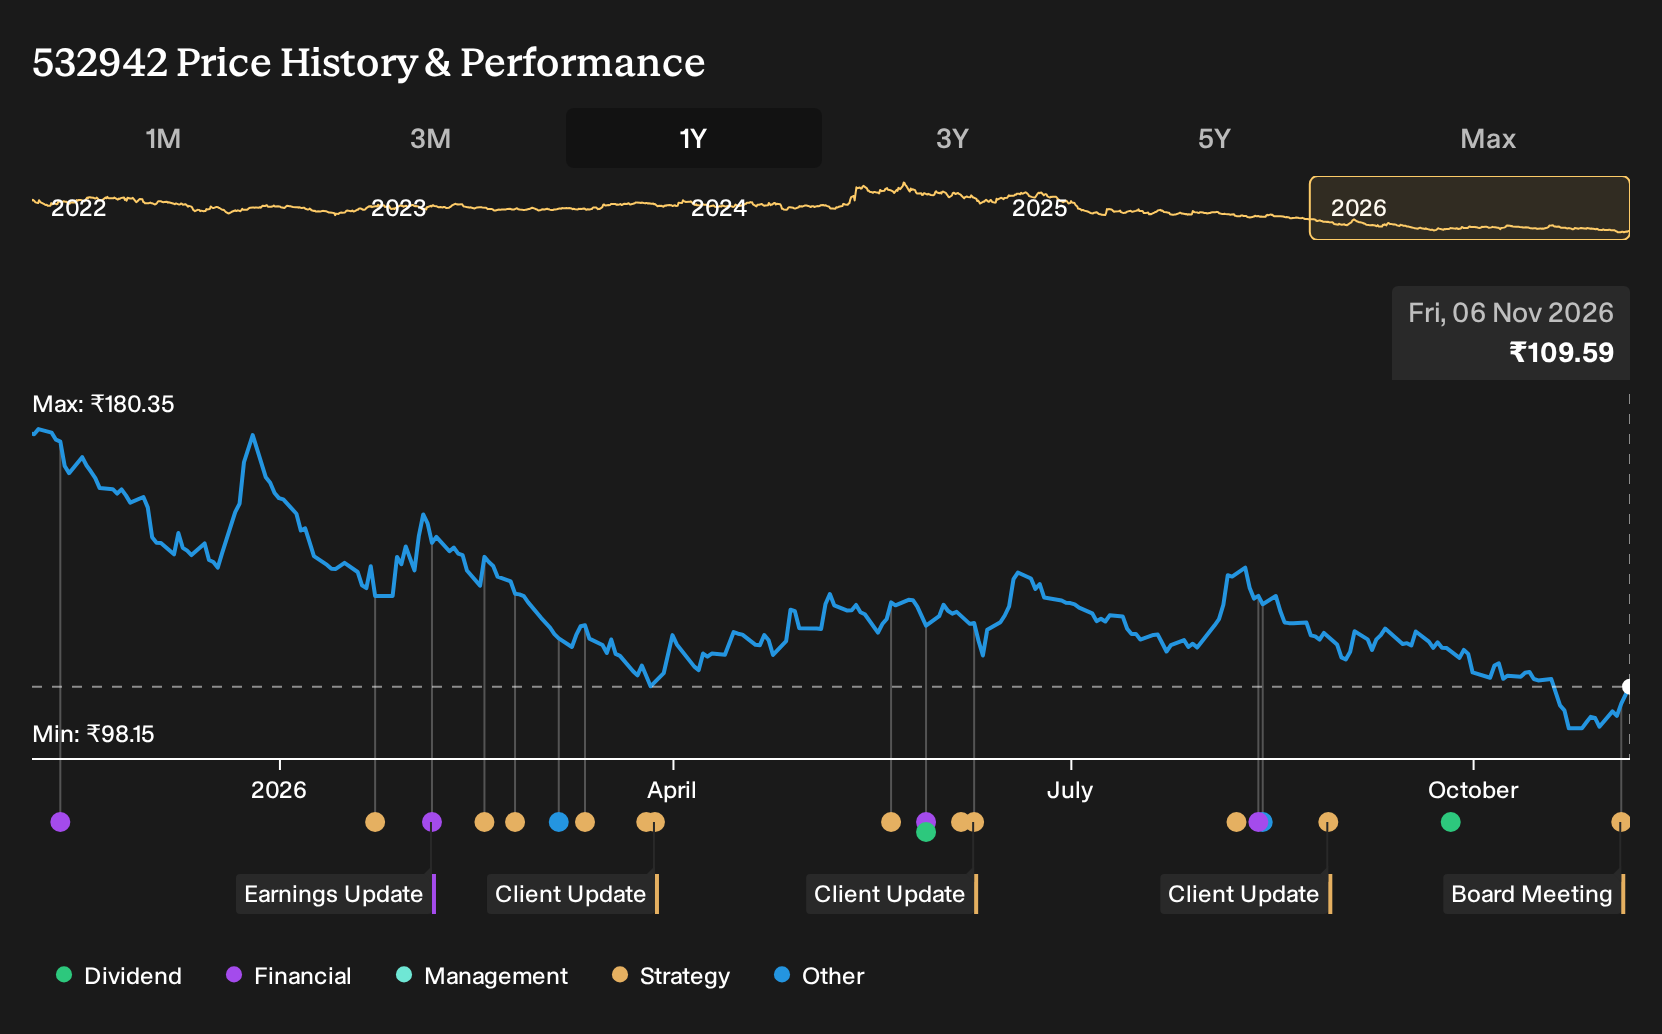
If you only skimmed the story on KNR Constructions, the early debate between bullish talk of Bharatmala upside and bearish warnings on delayed payments might have felt like noise. Holding KNR Constructions over the past year would have meant a 39.1% loss, including dividends. If you had been weighing that decision a year ago, what was already visible about falling revenue, weaker profit and a shrinking net margin that could have signalled this risk?
If the move has made KNR Constructions harder to judge, start where the gap is still open and scan 222 high quality undervalued stocks.
The Two Stories Investors Were Really Arguing About On KNR Constructions
The shares cost ₹179 at the start of the period, so anyone looking at KNR Constructions had to decide which story felt more plausible.
The bullish narrative saw government programs like Bharatmala and PM Gati Shakti feeding a stronger order book, with a Fair Value of ₹340. This reflected a higher implied price based on those assumptions and a belief that diversification into mining, metro, rail and solar could support long projects even with profit margins shrinking to 7.9%.
The bearish view argued that payment delays, higher input costs and weaker order inflows could have a stronger impact, backing a Fair Value of ₹156. This scenario assumed revenue declining 5.8% a year and margins slipping to 7.4% while KNR Constructions remained heavily exposed to government and Hybrid Annuity Model work.
What The Results Changed For KNR Constructions
The clearest new fact was KNR Constructions reporting Q1 2027 revenue of ₹5,879.447m versus ₹6,127.228m a year earlier, with net income also lower and net margin slipping from 20.1% to 13.7%. That shift in profitability challenged the bullish case that expected strong earnings resilience and gave more weight to the cautious thesis.
The lesson is simple. When a story leans heavily on margin strength, keep checking whether net margin trends match the promise, not just where the share price moves.
What You Are Paying For In KNR Constructions Today
With the share price now at ₹110, the selected Narrative argues that Fair Value sits above the current level because KNR Constructions has a large, diversified order book and potential cash coming from mining and HAM asset monetisation.
On that view, anyone buying today would be assuming KNR Constructions executes mining projects and recycles HAM capital closely in line with current guidance.
"The thesis on KNR Constructions has been reviewed and reaffirmed. The updated view gives more weight to the role of long tenor mining projects, HAM asset monetisation, and the impact of management’s revenue and margin guidance on how the existing order book could translate into future earnings quality."
The price and this Narrative do not agree. → Uncover what this Narrative says KNR Constructions is actually worth
Which Company Could Surprise You Next?
The next headline does not have to be where your research begins. Go straight to the companies and see whether a contrarian opportunity could be taking shape.
- Company 1 - 18% below our estimate - supplies high bandwidth memory and storage that relieve capacity bottlenecks in AI data centers.
- Company 2 - 20% below our estimate - sells antibiotic eluting bone grafts surgeons adopt to shorten systemic drug courses in infections.
- Company 3 - 49% below our estimate - runs franchised upper midscale hotels that feed a fast growing consumer retail platform.
That is three of the list. See every one of the 192 solid balance sheet companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com